What a Fake Credit Report Template Actually Is
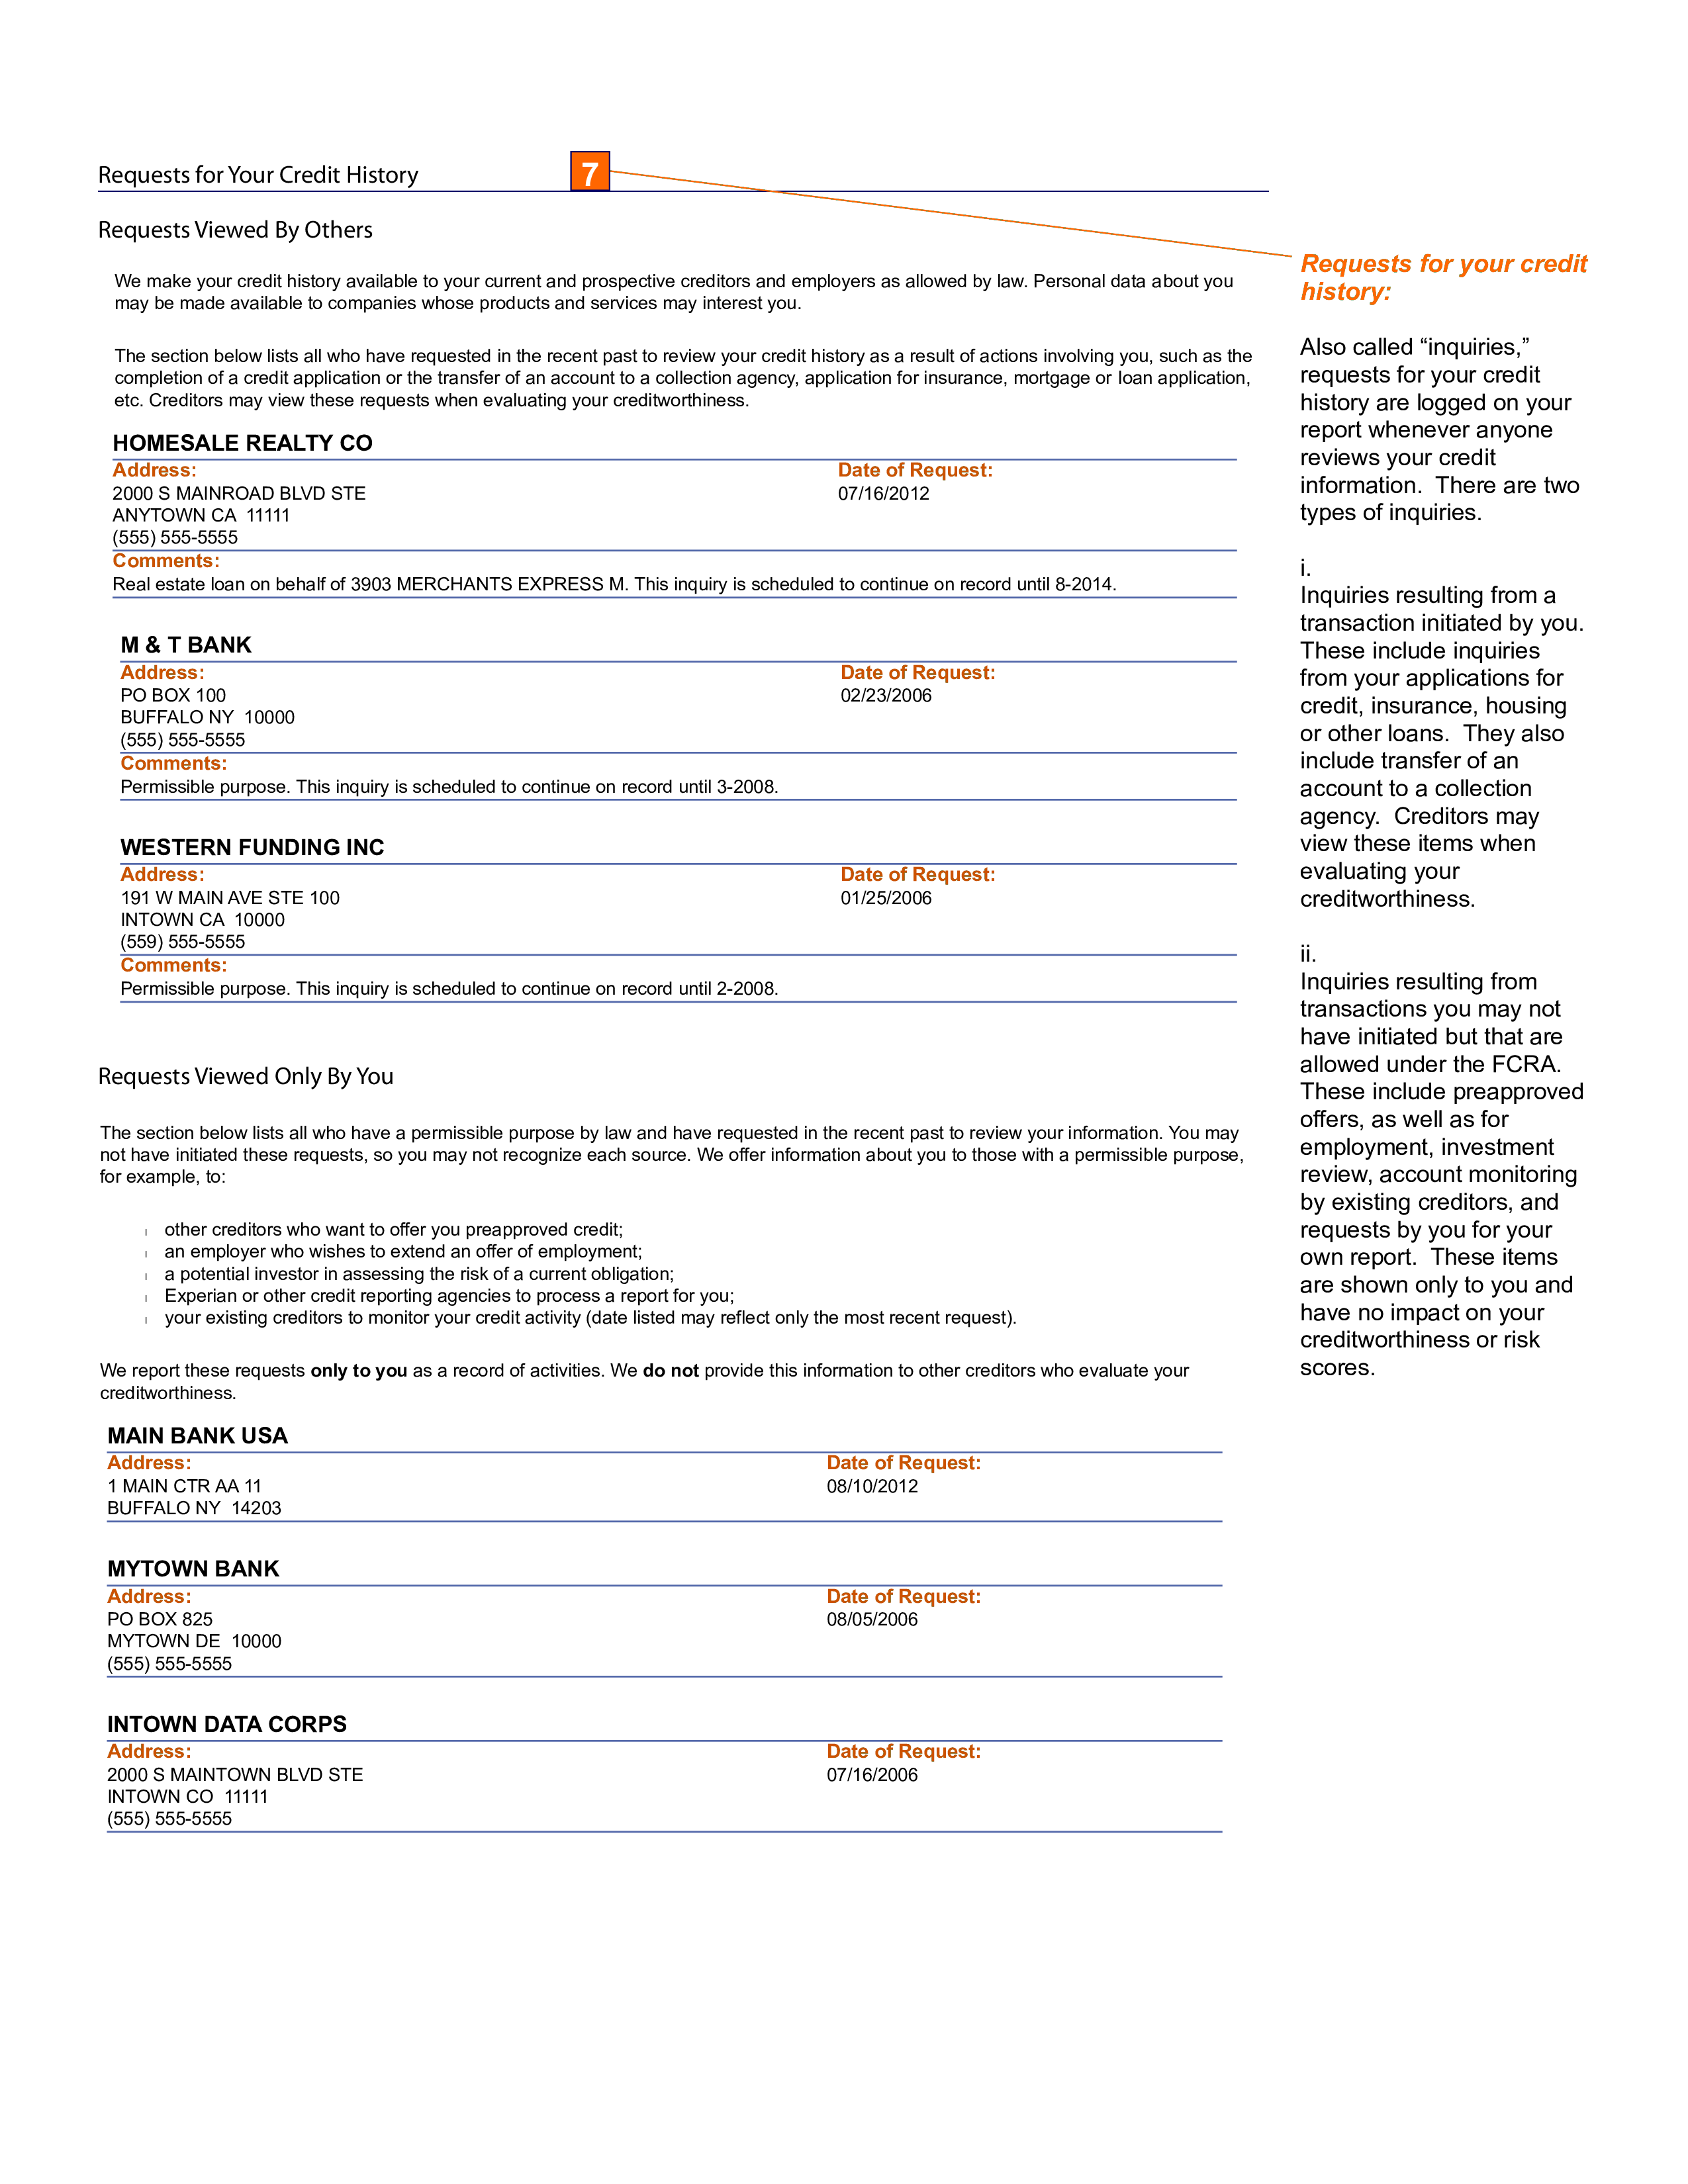
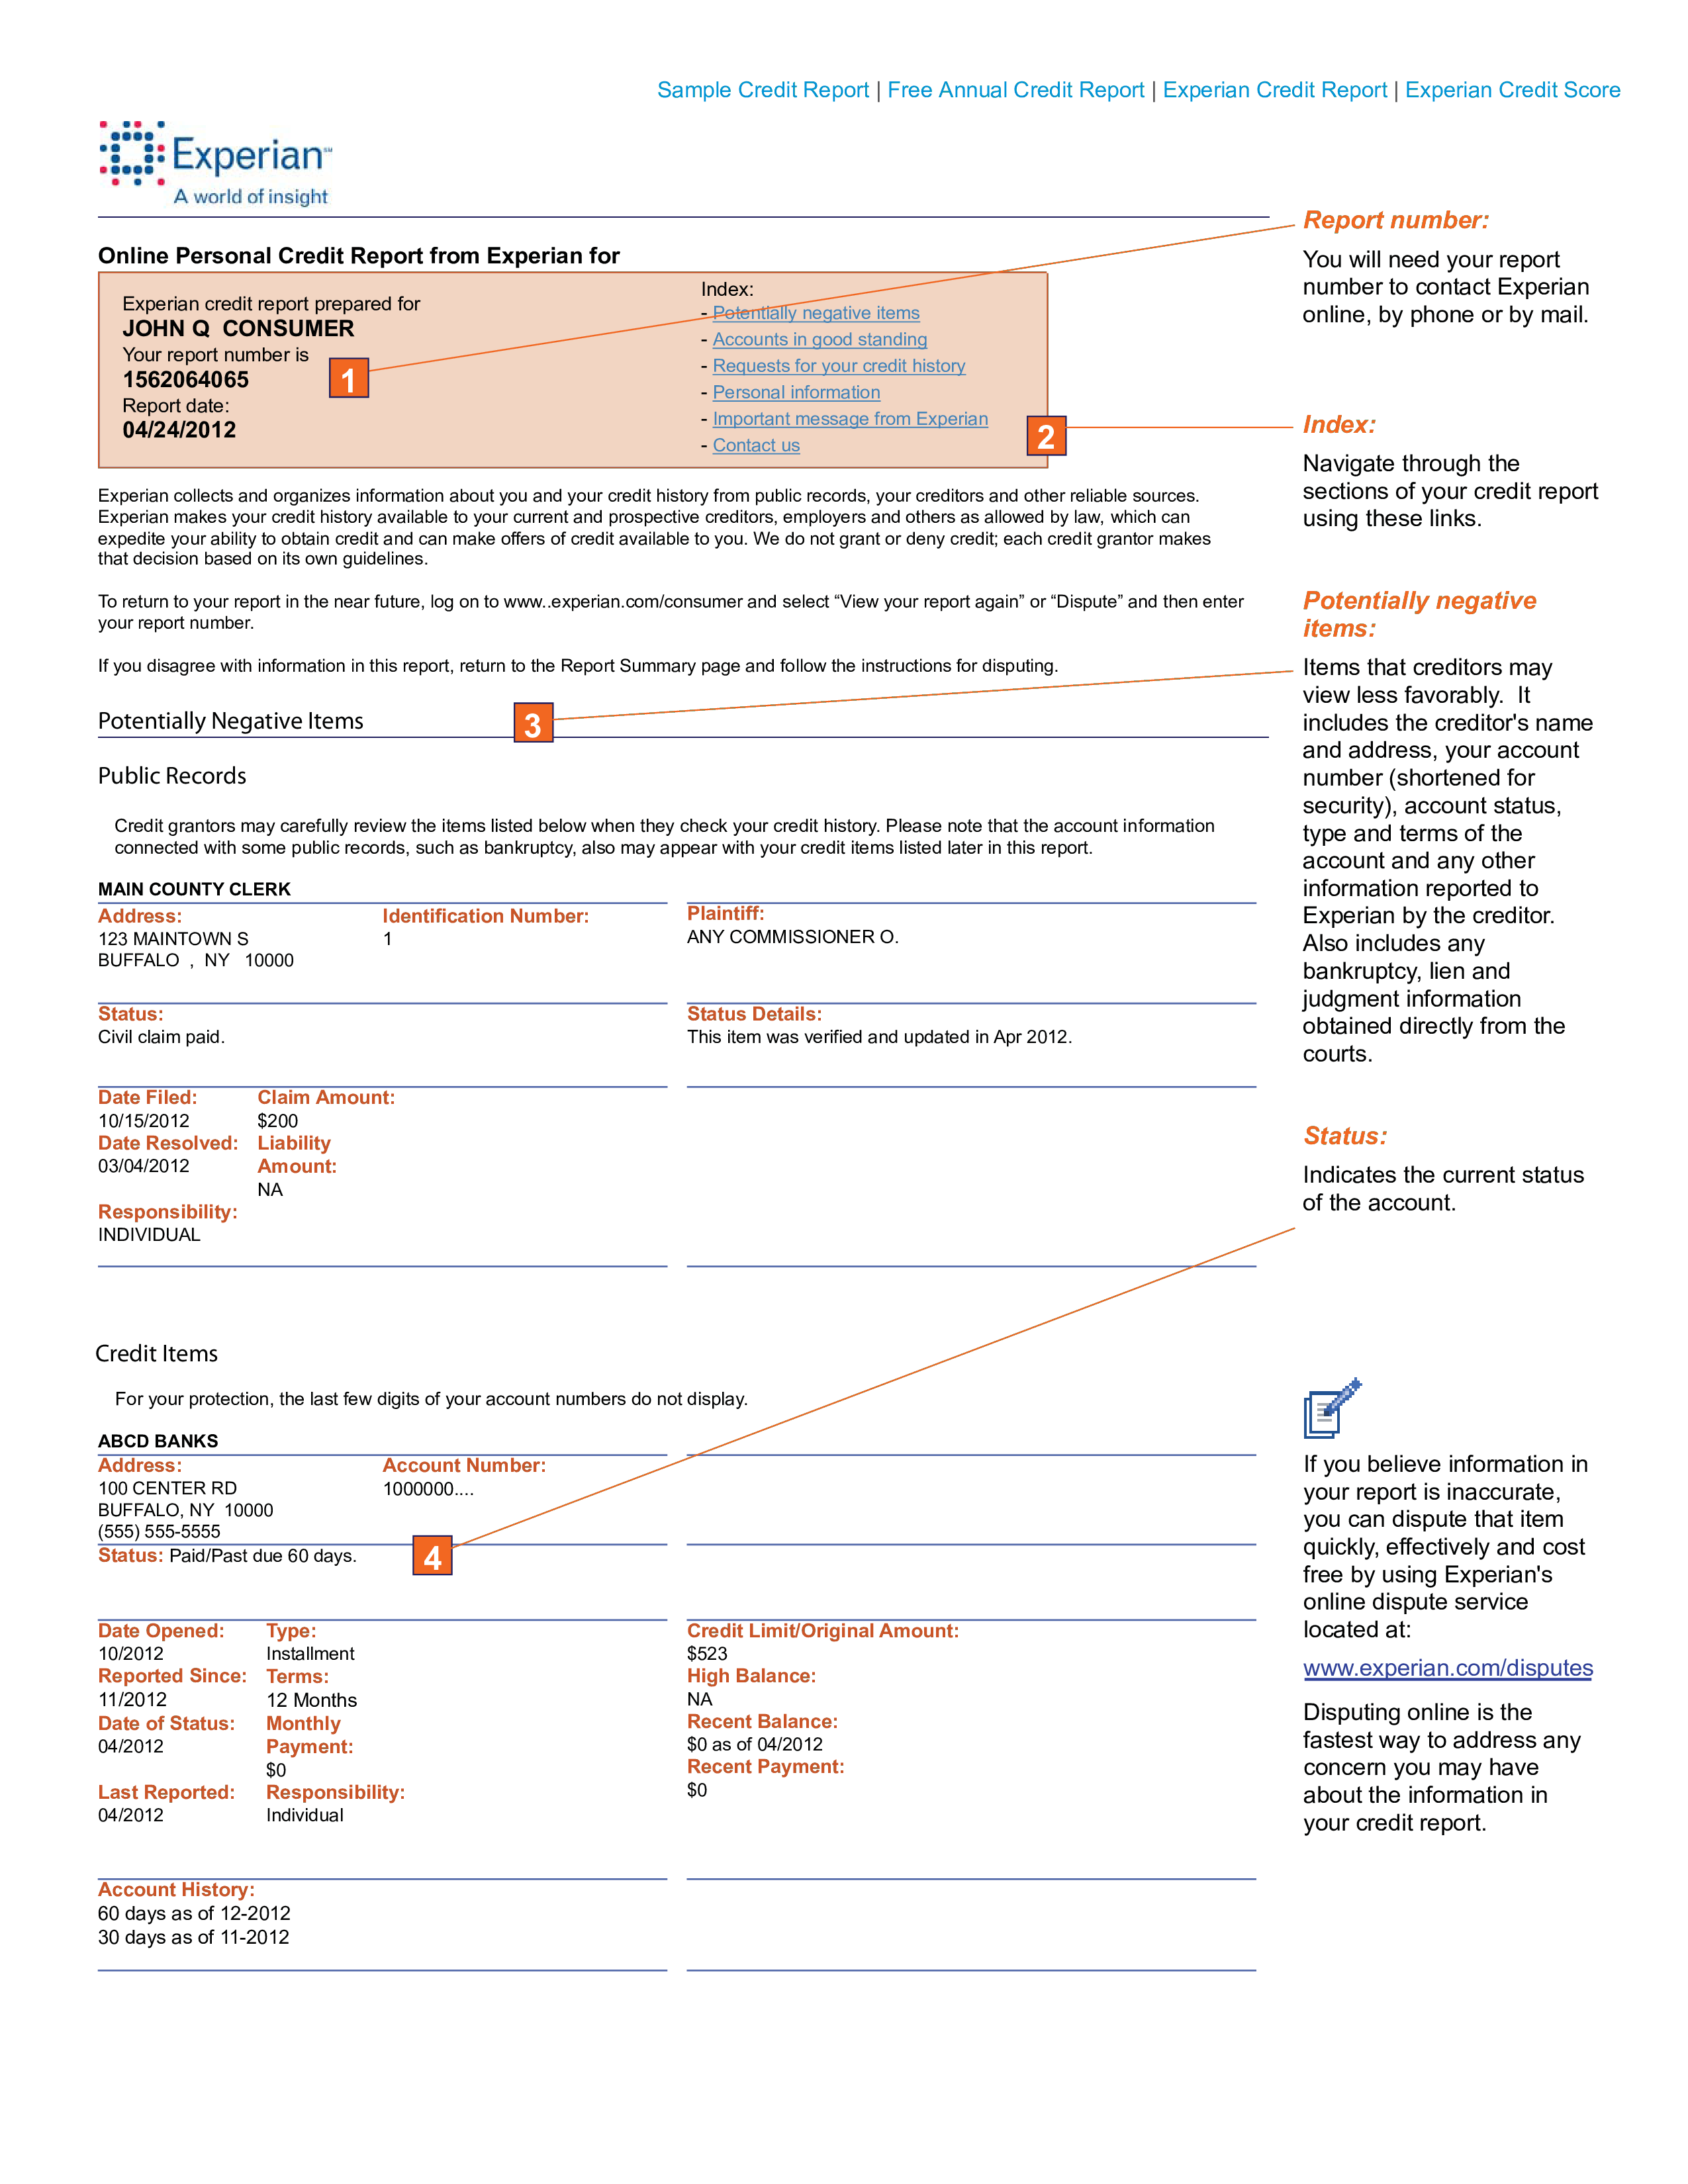
A Fake Credit Report Template is a pre-formatted document that mimics the structure of a legitimate credit report, typically pulled from one of the three major bureaus. It replicates the layout — personal information section, account lines, payment history grids, inquiries, public records — but populates the fields with fabricated or placeholder data. These templates surface in a few different forms: editable PDFs, Excel sheets, Google Docs, and sometimes HTML-based generators. The people looking for these are usually in one of two camps. The first wants a sample for testing or training — loan officers verifying that their document review process can catch anomalies, compliance teams building internal audit simulations, or freelance document verifiers who need practice assets. The second camp is far less legitimate, and it's the reason these templates carry serious legal risk. I've seen a lot of templates float through forums over the years. The ones that look convincing at a glance usually fail under closer inspection because they're missing small structural details that actual bureau-generated documents contain. Bureau letters, specific field alignments, certain barcodes, query reference numbers — those are the things that give a report away.
What's Inside a Typical Template
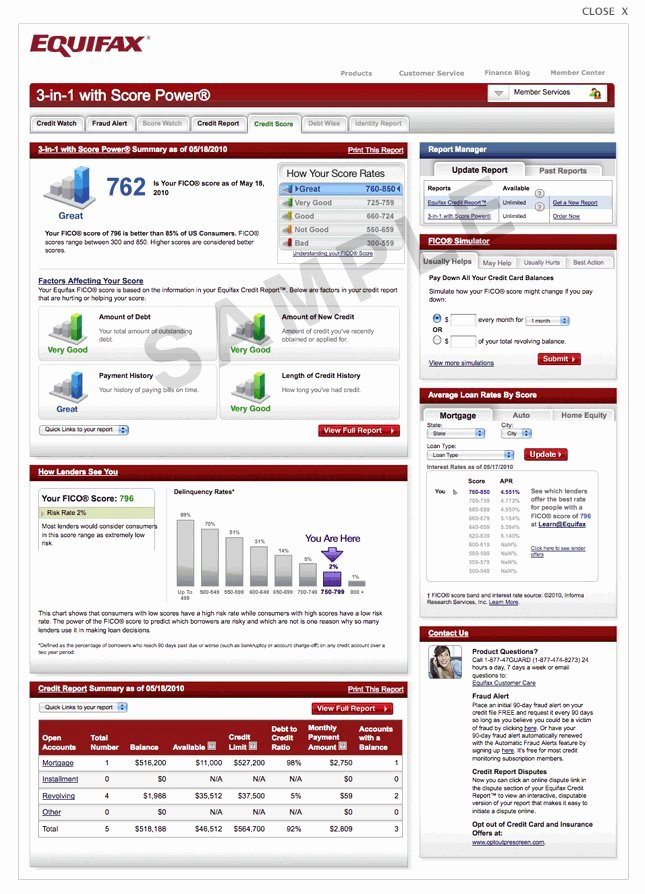
Most usable templates include the following sections: Header and bureau branding: Equifax, Experian, or TransUnion styling. Some templates use generic branding that still reads like a credit report. This is the part that's easiest to get wrong, because the visual layout varies by bureau and even by country or region. Personal information block: Full name, date of birth, Social Security number or equivalent, current and prior addresses, employer information. A proper template will have these fields structured exactly where they appear on a real report.
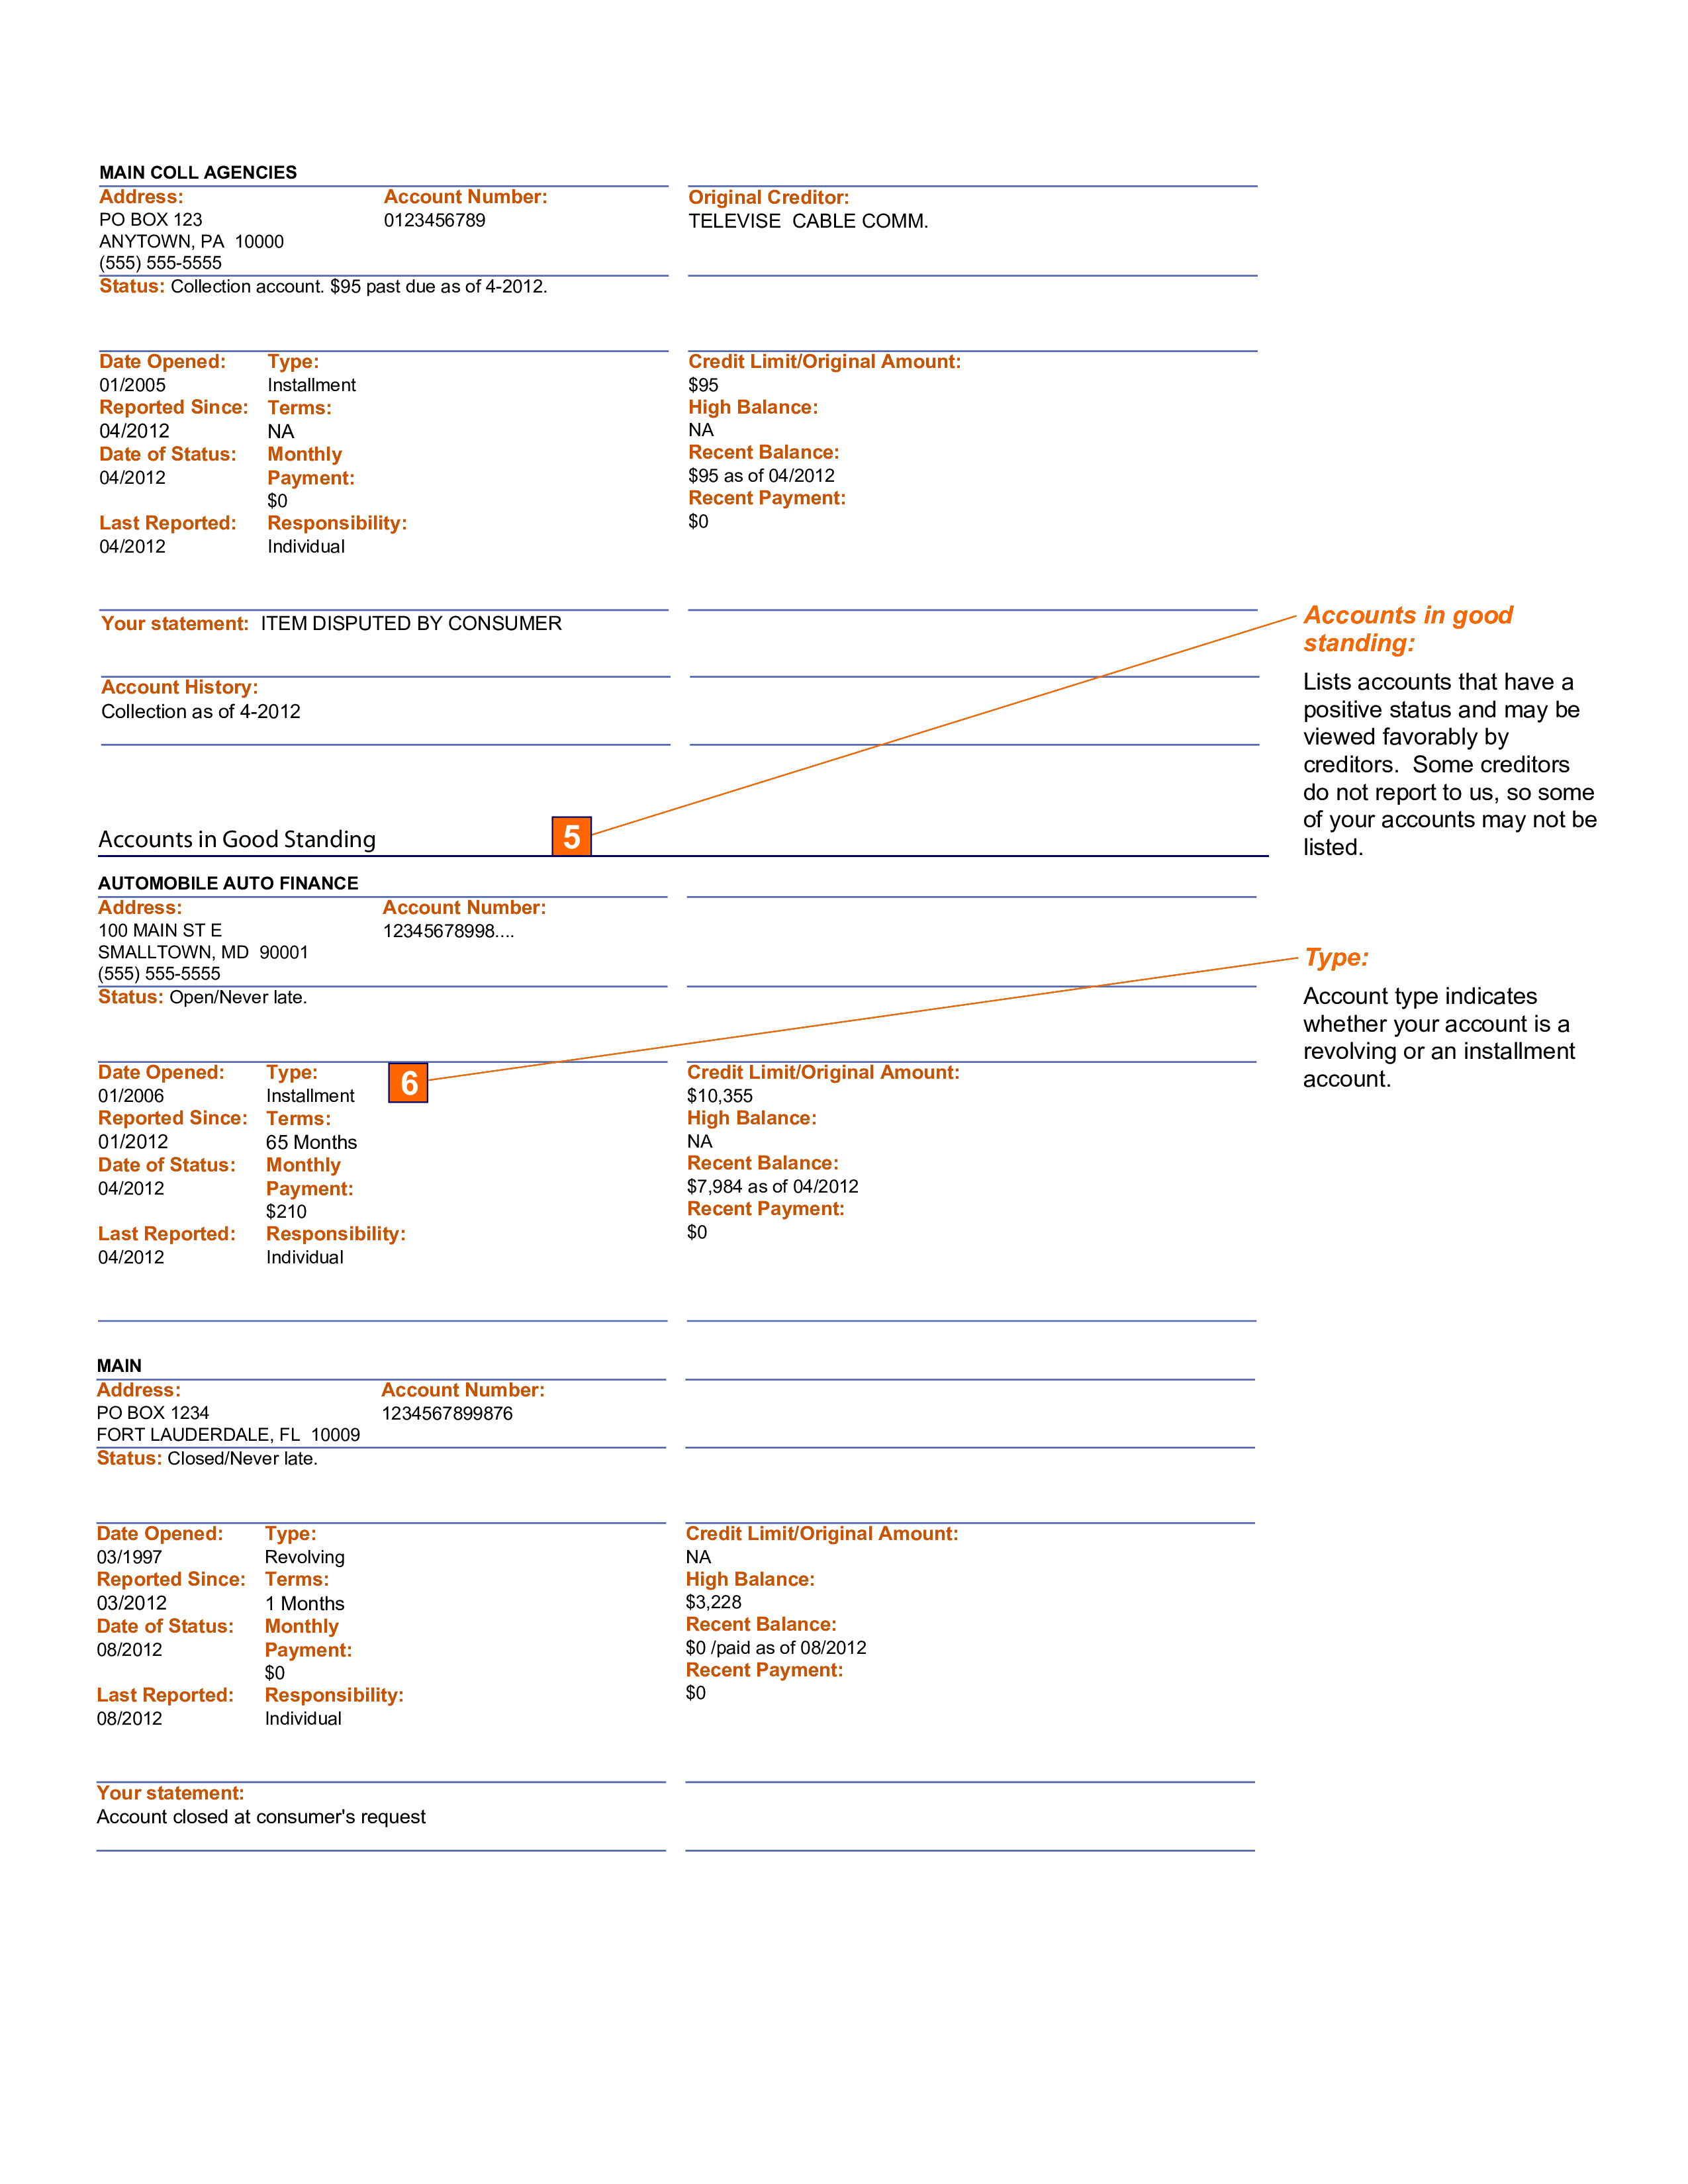
Account history table: Each tradeline contains the creditor name, account number (usually masked), account type, open date, credit limit or original amount, current balance, payment status, and months of payment history. The payment grid is what separates a decent template from a sloppy one. Inquiries section: Hard and soft inquiries with dates, creditor names, and sometimes source codes. Public records and collections: Bankruptcies, tax liens, judgments, and collection accounts with dates, amounts, and court information.
Get the Full Details
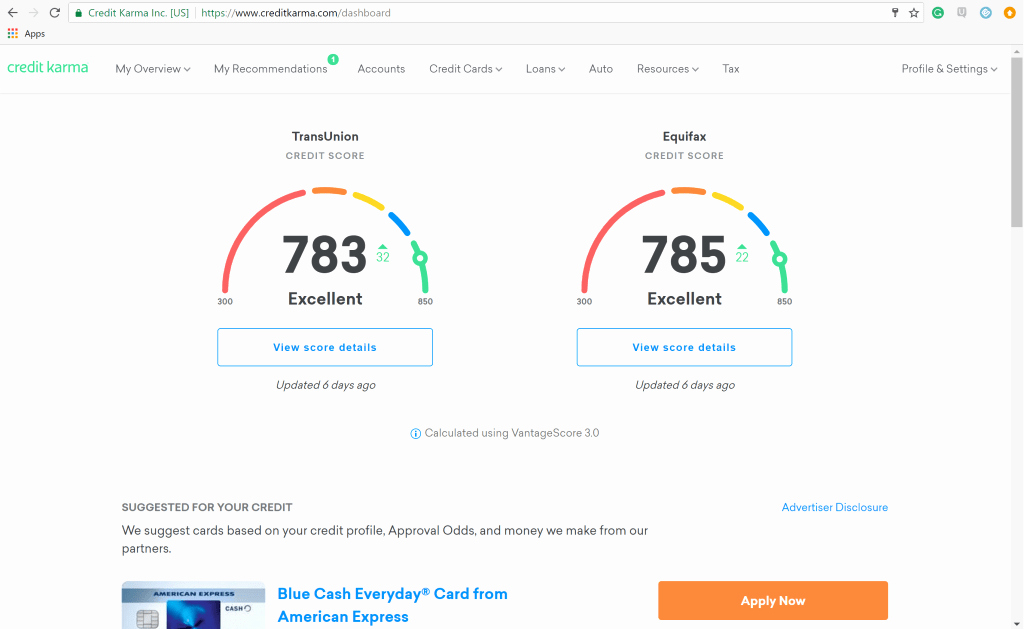
Score and summary section: FICO or VantageScore display, credit utilization percentage, total accounts, delinquent accounts, and the standard summary narrative that appears on every real report.
Where People Try to Find a Fake Credit Report Template
You'll find them on document template marketplaces, some freelance platforms, forum threads, and occasionally on sites that sell "report generation software." The quality varies wildly. I once spent about forty-five minutes trying to reverse-engineer a free Excel template someone linked from a Reddit thread, only to discover the payment history grid had misaligned column headers and the account types were using obsolete terminology. It would have been caught in about five seconds by anyone who processes these documents regularly. The best templates I've encountered are usually the ones built from actual redacted bureau reports. Someone takes a real document, strips the PII, and reconstructs the format. Those tend to be the most structurally accurate.
Practical Considerations Before You Use One
There are a few things that matter more than the visual layout. The first is scale. A template that looks fine on one page falls apart when you're generating multiple reports simultaneously with different data sets. The second is update frequency. Bureau formatting changes periodically, and templates that haven't been updated in a while will show outdated field structures. I ran into a specific edge case once where a client needed a practice report for a fraud detection training exercise. We used a template that was nearly perfect, but the inquiry section didn't include the proper inquiry source codes — the numeric identifiers that show where the inquiry originated. Every real inquiry from a major lender carries a specific code, and the template we had just listed "Mortgage Lender" without the corresponding code. A trained eye would spot that gap immediately. We fixed it by cross-referencing the codes from a legitimate redacted report and manually patching the template's inquiry module. It took roughly twenty minutes and made the difference between a document that passed scrutiny and one that didn't. Another practical detail: many templates don't account for state-specific requirements. Some states require additional disclosures or specific formatting for certain sections. If your use case involves a particular jurisdiction, you need to verify the template covers those requirements or add them manually.
What to Check When Evaluating a Template
Before you commit to any template, run through these checks: Field accuracy: Are the column headers correct? Do the payment history columns use the right notation (1, 2, 3 for late payments, or the newer alphanumeric system)? Some older templates still use the old numerical notation, which is a red flag on its own. Bureau consistency: Each bureau has subtle differences in layout. Make sure the template matches the bureau you're simulating, not a hybrid that pulls elements from all three. Hybrid layouts are an instant tell.
Score calculation display: Some templates include a score but don't show the scoring model or the date range. A legitimate report always includes this. If it's missing, the template is likely incomplete or outdated. Barcode and reference numbers: Real credit reports include specific reference and barcode elements. Templates often omit these or fabricate them in a way that doesn't match bureau formatting rules. This is one of the most common failure points. Date logic: Every date on the report needs to be internally consistent. Account open dates can't be after the current date. Payment history can't show future dates. Collections can't predate the original account by an impossible amount of time. I've seen templates where the math didn't check out simply because the fields were auto-generated without validation logic.
Limitations and Where Templates Fall Short
Let me be clear about what these templates can't do. They can't generate legally valid credit reports. They can't be used to apply for credit, loans, or housing — doing so is fraud and carries felony charges in most jurisdictions. They can't replace an actual credit report pulled through legitimate channels. And they can't fool anyone who has experience reviewing these documents, because the structural tells are well known. Some templates also struggle with certain edge cases. International applicants, co-op accounts, and certain secured or specialized credit products sometimes don't fit neatly into the standard template structure. If you need reports for these scenarios, you'll likely have to modify the template significantly or build a custom version. If your goal is legitimate — training, testing, or internal verification — I'd recommend using a service that provides simulated credit data specifically designed for those purposes. There are a few vendors that sell sanitized, legally compliant test datasets. They cost money, but they save time and eliminate risk. A typical commercial test dataset runs anywhere from fifty to a few hundred dollars depending on the volume and depth, and it covers far more edge cases than a free template ever will.
The bottom line is that a Fake Credit Report Template is a tool, and like any tool its usefulness depends entirely on what you intend to do with it. Used responsibly for training or verification, it's a reasonable resource. Used for anything that involves deception or misrepresentation, it's a fast track to serious legal consequences. The templates themselves aren't the problem — the problem is always the intent behind them.