What Falsifying Business Records Actually Means in Practice
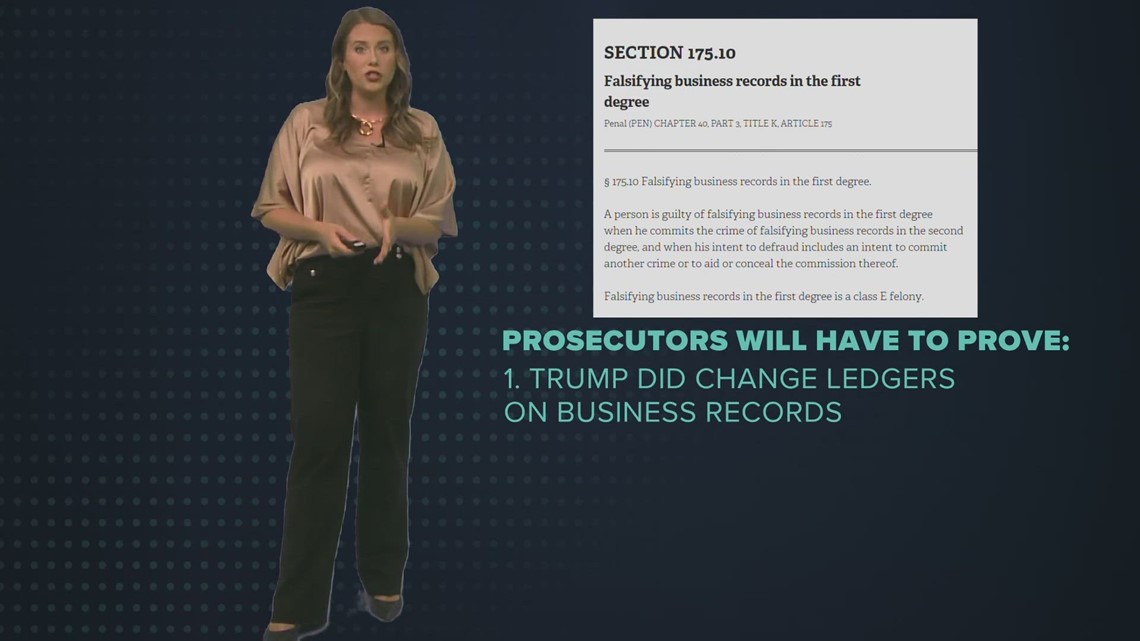
Falsifying business records isn't a dramatic courtroom moment. It's usually the result of someone trying to cover their tracks after a mistake, or someone trying to make numbers look different than they actually are. The legal definition varies by jurisdiction, but the core idea is straightforward: knowingly making or causing a false entry in business records with the intent to defraud or deceive. In New York, for example, it's defined under Penal Law Article 175. You commit the offense when you knowingly and with intent to defraud, deceive, or injure anyone, you make or cause a false entry in business records. The key word there is intent. A clerical error, even a sloppy one, doesn't automatically qualify as falsification. The prosecution has to show you meant to mislead. I've handled cases where the distinction between a genuine mistake and an intentional false entry was the entire defense. One client, a small shop owner, had been entering customer payments into the wrong columns on his spreadsheet for months. When an auditor flagged it, he panicked and tried to fix the records retroactively, which turned an accounting error into something that looked much more suspicious. He didn't know that backdating corrections is one of the fastest ways to go from "mistake" to "falsification" in the eyes of an investigator.
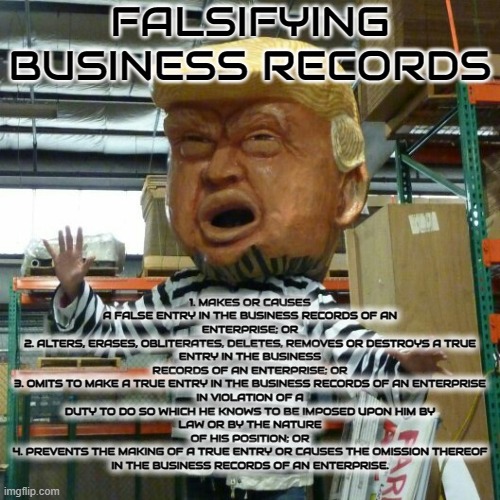
Here's what people often miss: the records don't have to be false in a way that matters to the grand scheme. Even a minor misstatement can qualify if it was done intentionally and with fraudulent intent. That means an off-by-one error isn't the problem — the problem is that you changed it deliberately after the fact to avoid detection. Another thing most people get wrong is thinking you have to fabricate something from whole cloth. You don't. Altering an existing record, deleting an entry, or writing over information already on file all count. The act of falsification covers any modification that introduces falsehood into the documented record. I ran into this exact situation with a contractor who was paying subcontractors in cash and recording the amounts as something else in his books. He wasn't trying to steal from anyone — he was trying to cut his tax liability. The intent was fraudulent, the records were false, and the charges stuck. His argument that "it was just about taxes, not about stealing from a person" didn't matter. The law doesn't require a specific victim of fraud, just the intent to defraud or deceive.
How It Works in the Real World
Most falsification cases don't come from evil masterminds. They come from small business owners who cut corners, managers who pad expense reports, or employees who alter timesheets. The severity of the charge depends on the purpose behind the falsification. In some jurisdictions, if the records were falsified to conceal another crime, the charges get stacked and the penalties increase significantly. A common pitfall is assuming that if no one was directly harmed, you won't get charged. Prosecutors don't need to prove actual financial loss. They need to prove the intent to defraud. That's a lower bar and it trips up a lot of people who honestly believe their actions were victimless. Another nuance: corporate entities can be held liable too. If a company as an organization falsifies records, the individuals who authorized or carried out the falsification can face personal criminal charges on top of any organizational penalties. This is where vicarious liability and individual culpability get tangled, and most people walk into it without realizing it.
Get the Full Details
What Counts as a Business Record
This is where things get broader than most people expect. Invoices, ledgers, payroll records, tax filings, inventory logs, email correspondence related to business operations, digital spreadsheets, bank statements — it's not limited to formal paper documents. Electronic records count. Handwritten notes on a business napkin could potentially count if they're being used as part of the business record-keeping system. The scope also extends to third-party records. If you cause someone else to enter false information into their records, you can still be on the hook. That includes getting a vendor to issue a false invoice, asking an accountant to adjust numbers retroactively, or pressuring an employee to alter their time cards.
Defenses and Practical Considerations
The most effective defense usually hinges on the intent element. Without proof of fraudulent intent, you're looking at either a misunderstanding, negligence, or an honest mistake — none of which constitute the crime. Documented good-faith efforts to correct errors can help, but they have to be contemporaneous. Fixing a record the day you find out it's wrong looks very different from fixing it six months later after an audit notice arrives. I once worked a case where the defense was able to show a clear paper trail of the original error, the discovery of that error, and the steps taken to report and correct it immediately. The client's bookkeeper had accidentally doubled a vendor payment in the system, and the client had corrected it in the next accounting cycle and flagged it in the internal audit report. When the state came calling, that documentation was the difference between a charge and a dismissal. On the flip side, if you're trying to figure out whether your own records put you at risk, the question isn't whether the numbers are wrong — it's whether you'd be able to explain the discrepancy in good faith if someone asked you about it three years from now. Most people can't. Their memory fades, their documentation is incomplete, and what starts as a reasonable explanation looks increasingly like a fabricated story under scrutiny.
Penalties and Consequences
Falsifying business records is typically a misdemeanor, but it can be elevated to a felony depending on the jurisdiction and the purpose behind the falsification. In New York, it's generally a class A misdemeanor, punishable by up to one year in jail. However, if the records were falsified to conceal a felony, the charge becomes a class E felony with potential prison time. Beyond the criminal penalties, there are civil consequences. Restitution orders, fines, disgorgement of ill-gotten gains, and reputational damage that can cost you your license to operate in certain industries. A conviction for falsifying business records shows up on background checks, affects bond applications, and can trigger regulatory sanctions even in areas unrelated to the original offense. The collateral damage is often underestimated. A single falsification charge can disqualify you from government contracts, professional certifications, and certain types of employment. People treat it as a minor offense because it sounds minor. It rarely is.
How to Avoid Problems
The simplest advice is also the most overlooked: keep your records accurate from the start. Don't try to clean things up after the fact. If you discover an error, correct it in the normal course of business with a notation that explains what happened and when. Don't erase or overwrite. Leave an audit trail. Use separate accounts for personal and business transactions. Mixing them is the fastest way to create confusion that can be construed as intentional falsification, especially if you're ever audited. Clean separation makes your record-keeping defensible even if mistakes happen. If you're running a business and you're not sure how to handle a particular situation, talk to someone before you make changes to your records. A quick consultation costs nothing and prevents a lot of problems. Waiting until you're under investigation is expensive and limits your options considerably.
The bottom line is that falsifying business records is less about elaborate schemes and more about the choices people make when they think no one is looking. The law doesn't require you to be brilliant at hiding things. It only requires proof that you knew what you were doing and did it on purpose.