Understanding FHA Loan Calculations Beyond the Basics
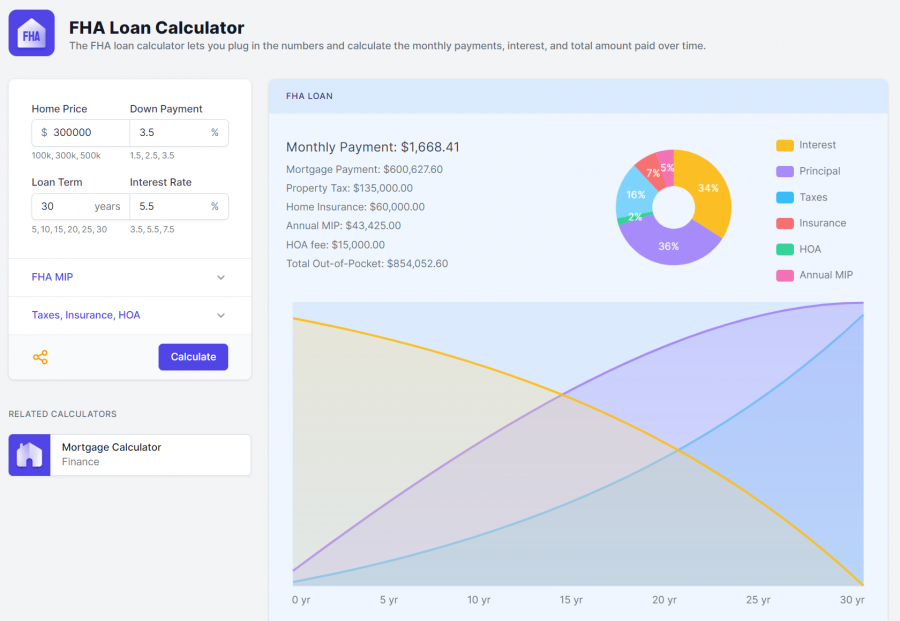
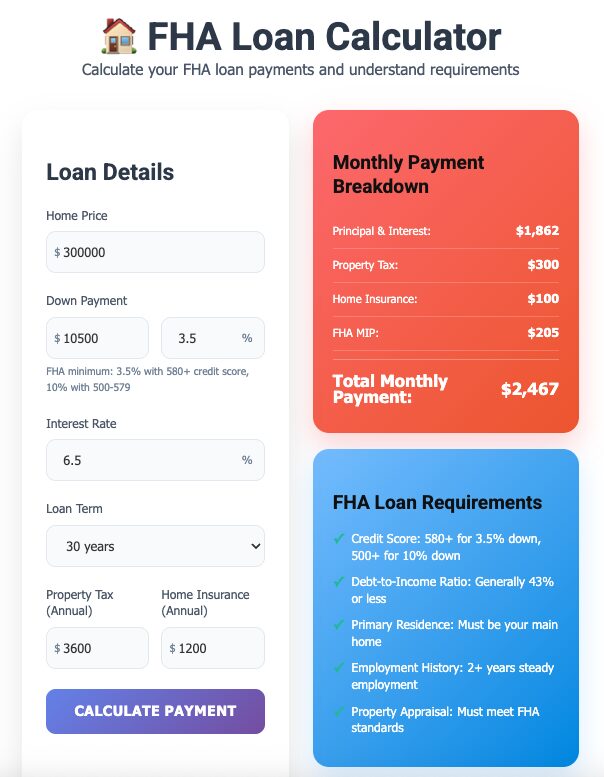
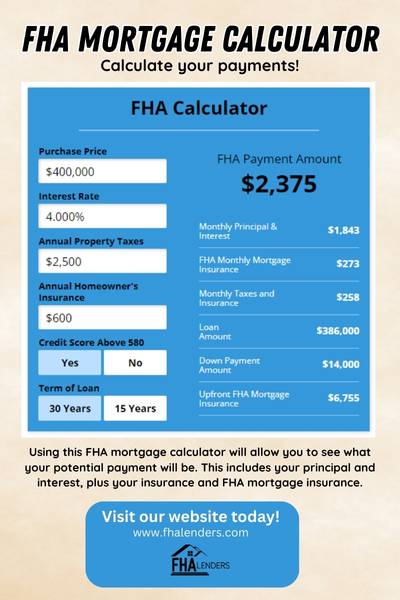
Most people grab a generic mortgage calculator and plug in numbers, then get confused when the result doesn't match what their lender quotes. The gap is almost always mortgage insurance, and with FHA loans specifically, that introduces a layer most online tools handle poorly or not at all. An FHA loan differs from conventional financing because the government backs it, which means you get a lower down payment requirement but also pay two separate mortgage insurance components. There's an upfront premium that typically gets financed into the loan balance, and there's an annual premium charged monthly for the life of the loan in most cases. A properly configured Fha Calculator accounts for both of these, along with property taxes, homeowners insurance, and HOA fees if applicable.
How to Use an Fha Calculator Correctly
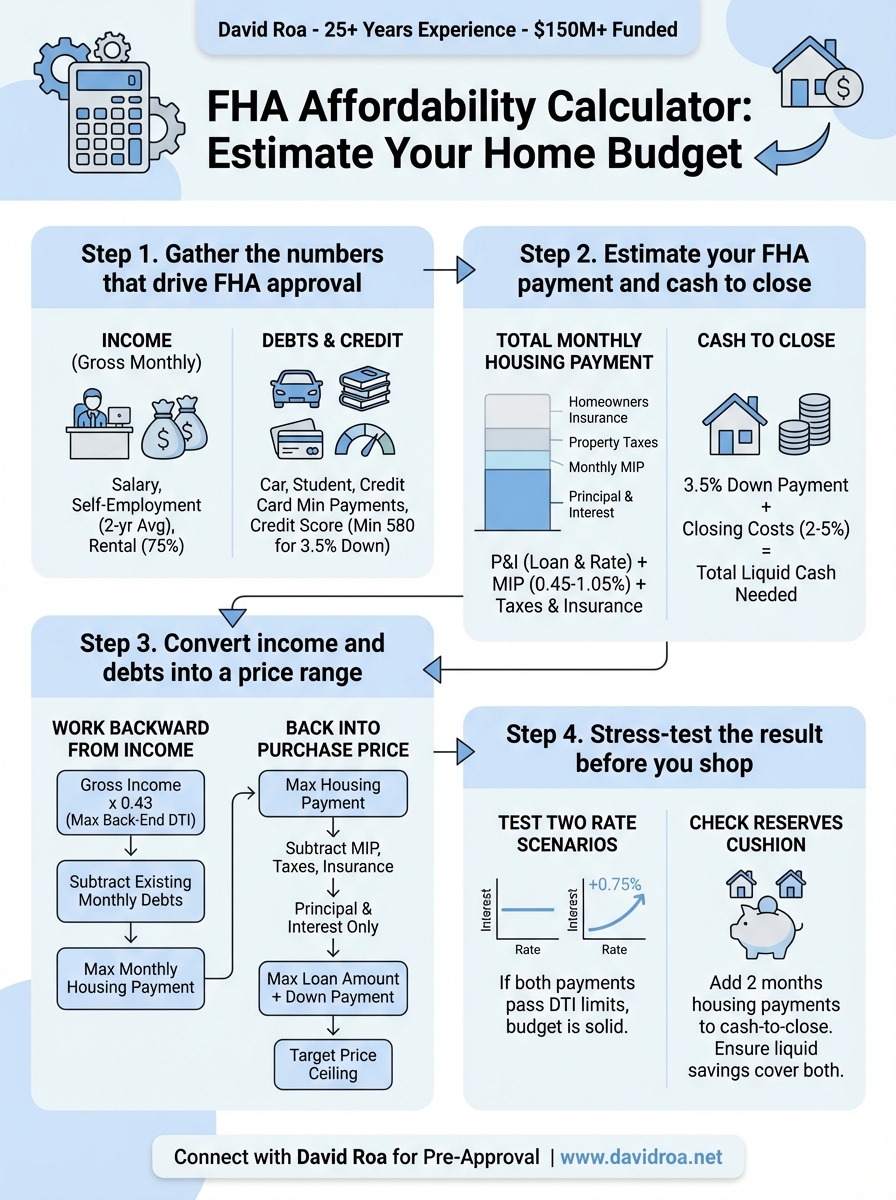
Start by gathering your actual numbers rather than guesses. Lenders pull debt-to-income ratios from your credit report, so knowing your total monthly debts beforehand saves several minutes. Your credit score matters more for FHA than many people realize — while 580 is the textbook minimum for 3.5 percent down, scoring below 620 can shift your mortgage insurance rates slightly higher depending on the lender, and some won't touch anything under 640 regardless of what the FHA guidelines say. Enter the purchase price first. Then your down payment, which for FHA is typically 3.5 percent if your credit score is 580 or above. After that, input the interest rate your lender has offered you. This is where most people go wrong — they use a rate they saw advertised online rather than the actual rate lock they're working with. Rate differences of even a quarter point change the monthly payment noticeably on FHA loans because of how the insurance premiums interact with the total loan amount. The critical field that most calculators bury or omit is the mortgage insurance input. For standard FHA loans, the upfront MIP is 1.75 percent of the base loan amount. The annual MIP ranges from 0.55 to 0.78 percent depending on your loan-to-value ratio and term. For a 30-year conforming FHA purchase with 3.5 percent down, you're looking at roughly 0.55 percent annual MIP. The calculator should divide that annual figure by twelve and add it to your PITI payment.
I worked a file last year where the borrower's calculator showed a $1,420 monthly payment but their closing documents came in at $1,587. The discrepancy was that the online tool calculated the upfront MIP as a separate one-time charge rather than financing it into the loan balance. Once that 1.75 percent gets added to the principal, it compounds — you're paying interest and monthly insurance on top of the insurance premium itself. The corrected calculation added about $35 per month to what the borrower expected. Small number, but it mattered for their debt-to-income qualification.
Get the Full Details

Pitfalls That Trips People Up
MIP isn't something you can easily eliminate on an FHA loan. For purchases with less than 10 percent down, the annual premium runs for the entire loan term. That's 30 years of an additional payment that a conventional loan wouldn't have if you put 20 percent down. Only if you refinance into a conventional loan later, once you've built enough equity, does that cost disappear. This is a feature of FHA loans that no calculator can fully communicate — it's a long-term financial commitment, not a short-term insurance fee. Another issue is that FHA loan limits vary by county. A calculator that uses national average figures will overstate your borrowing power in high-cost areas like Los Angeles or Miami, and understate it in places like rural Ohio. The 2024 FHA limits for a single-family home range from about $498,257 in most areas to $1,149,825 in high-cost counties. If your target home is in a high-cost zone, running the numbers using baseline limits gives you misleading results. Also worth noting: some calculators don't properly account for homeowner's association fees, which are mandatory inclusions in your payment if you're buying a condo or a home in a planned community. FHA requires these to be factored into your housing expense ratio, and missing them in your calculations means you'll likely fail underwriting when the real numbers surface.
What the Numbers Actually Tell You
A well-configured FHA calculator shows you three things that matter: your total monthly housing payment, your front-end debt-to-income ratio, and your back-end ratio when you include all other debts. Lenders typically want your back-end ratio below 43 percent, though some will go higher with strong compensating factors. The exact threshold depends on which manual underwriting framework the lender is applying. If the calculator shows a payment that pushes your DTI above 50 percent, don't just accept it. Look at whether you can increase your down payment, choose a shorter term, or explore state first-time homebuyer programs that offer down payment assistance. Those programs often stack with FHA financing and can bring your effective down payment requirement up to 5 or even 10 percent, which changes your MIP calculation and your overall qualification picture. FHA loans also allow gift funds for down payments, which many people don't know. A Fha Calculator that factors in gifted money properly will show you a different monthly payment than one that assumes you're drawing from savings. The difference matters because a larger loan balance means larger MIP charges. Gift funds need documented source and a letter from the donor, but they're widely available through employer programs, charitable organizations, and family members, so this isn't a theoretical workaround.