Understanding FHA Closing Costs When You Buy a Home
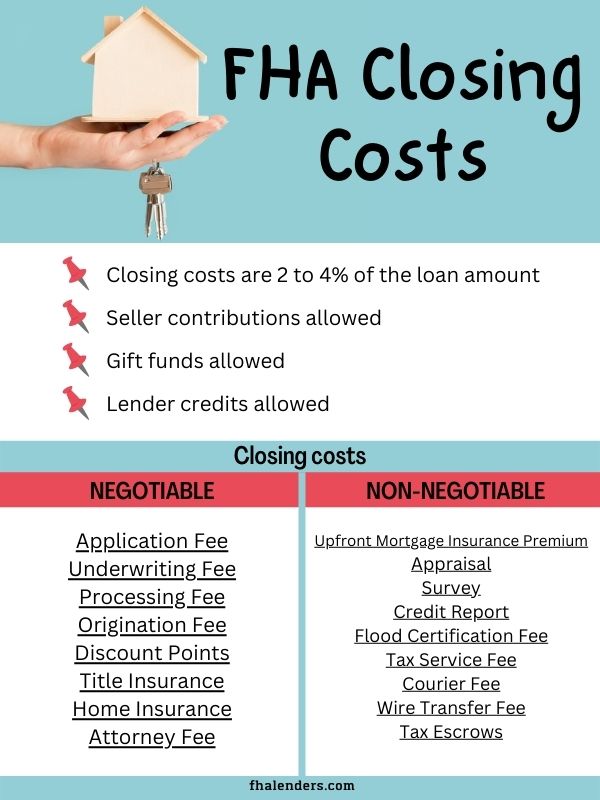
FHA loans have closing costs that are different from conventional loans in a few meaningful ways, and figuring them out upfront can save you from some headaches later. The total usually lands between 3 and 5 percent of the purchase price. On a $250,000 home that's roughly $7,500 to $12,500, give or take depending on where you live and what else is in the contract. They break down into a handful of categories, most of which look pretty standard whether you're going FHA or not. Appraisal runs about $500 to $800. Credit report comes in around $30 to $75. Title search and title insurance vary wildly by state but typically sit between $1,000 and $2,500 combined. Origination fees from the lender are usually 0.5 to 1 percent of the loan amount. Recording fees, transfer taxes, and HOA-related charges fill out the rest. The FHA-specific stuff is where things get a little different. There's an upfront mortgage insurance premium, commonly called the MIP, set at 1.75 percent of the base loan amount. That can be paid at closing or folded into the loan. Then there's the annual MIP, which runs 0.55 percent for most standard 30-year FHA loans and gets divided into monthly payments. So your actual monthly payment looks higher than the principal and interest alone would suggest.
I worked a file last year where the borrower's seller credit wasn't covering enough of the closing costs because the appraised value came in two percent below the contract price. That created a gap where the buyer had to bring extra cash to the table or renegotiate. The workaround was straightforward but annoying - we recalculated the allowable seller credit based on the actual appraised value instead of the contract price and went back to the seller with a revised ask. It took three extra days and a phone call the seller's agent was not happy about, but it resolved cleanly.
How to Estimate Your FHA Closing Costs Before You Apply
The most reliable way to get a number is to request a Loan Estimate from at least three different lenders. By law they have to use a standardized format, so comparing them side by side is actually useful. Look past the total and dig into pages two and three where the itemized costs live. Different lenders bundle things differently, but the major line items should be comparable. One thing most people miss is that the FHA appraisal isn't just checking value. It's also verifying the property meets HUD's minimum property standards. If the appraiser flags something like peeling paint in a home built before 1978 or a missing handrail, that repair has to be completed before the loan can close. I've seen this add $2,000 to $5,000 in unexpected costs for buyers who assumed closing costs were just fees and taxes. Budget for the possibility of minor repairs on older homes, especially if the property has been poorly maintained. Another counterintuitive detail: FHA allows seller contributions up to six percent of the sales price toward closing costs and prepaid items. That's higher than conventional loans in many cases. But here's the catch - if the seller is contributing six percent and your actual closing costs run only four percent, you can roll the excess two percent into the loan. I used that strategy on a transaction in Texas where the buyer was short on cash at closing and needed every dollar of seller credit available. It cleaned things up nicely without the buyer having to come out of pocket.
Get the Full Details
Ways to Reduce What You Pay at Closing
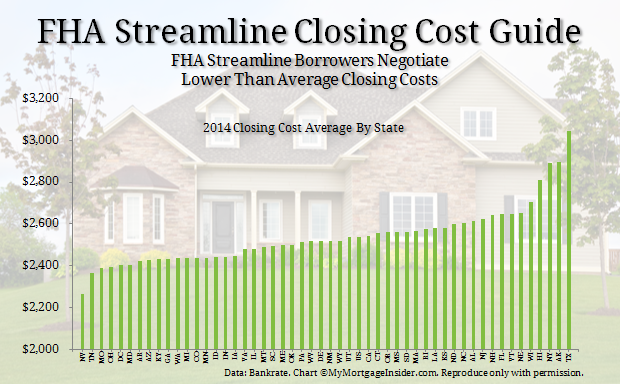
Negotiating seller concessions is the biggest lever you have. In a balanced or buyer's market, sellers are often willing to cover a meaningful portion of closing costs, especially if the offer price is attractive. Even in a hot market, some sellers will concede a few points to keep the deal from falling apart over inspection issues or appraisal gaps. Paying discount points is another option if you plan to stay in the home long enough to recoup the cost. Each point costs one percent of the loan amount and typically lowers your interest rate by about 0.25 percent. On a $200,000 FHA loan that's $2,000 for one point, but it could save you maybe $60 to $80 per month. Break-even is usually around three to five years depending on local rates, so it only makes sense if you aren't planning to move soon. There are also state and local programs, plus some employer-assisted housing initiatives, that offer grants or deferred loans for down payment and closing cost assistance. FHA loans are compatible with most of these, which is one of their practical advantages. Check with your state's housing finance authority or a local HUD-approved housing counselor to see what's available in your area. This is something a lot of first-time buyers don't know about and end up overpaying because they assume there's no help available.
Common Mistakes That Blow Up FHA Closing Cost Budgets
The biggest one is assuming the initial estimate you get during pre-approval is final. The Loan Estimate can change significantly between pre-approval and closing, especially if the appraisal comes in low or if there are changes to the interest rate. I've seen buyers budget for $8,000 in closing costs and then get hit with a $11,500 bill because they didn't account for an escalation in title insurance premiums after the purchase price increased during negotiation. Another mistake is ignoring the ongoing cost of mortgage insurance. With an FHA loan, the annual MIP runs for the life of the loan if you put less than ten percent down. If you put ten percent or more, it drops off after eleven years. A lot of buyers calculate their monthly payment based only on principal, interest, taxes, and insurance without factoring in the MIP, and then their debt-to-income ratio looks better on paper than it actually is. That can cause problems later if you're trying to refinance or qualify for other credit. The third common error is not shopping lenders. FHA loans are a government product, but the lenders charging to originate them are private companies with different fee structures. I've compared Loan Estimates for the same property and saw differences of over $3,000 in lender fees alone between two lenders in the same zip code offering the same rate. That's not a rounding error. It's worth spending an afternoon comparing estimates rather than just going with the lender your real estate agent recommended.
What Happens If Your Closing Costs Exceed Your Budget
If the numbers don't work out, you have a few realistic options. You can ask the seller to increase their concession up to the six percent FHA limit, though there's a point of diminishing returns here because sellers rarely go all the way to the maximum. You can lower your purchase price to reduce the loan amount and the costs tied to it. Or you can bring additional cash to closing, which isn't always possible for first-time buyers. There's also the option of a lender credit in exchange for a slightly higher interest rate. This effectively trades a higher monthly payment for lower upfront costs, and it can make sense if you need to preserve cash reserves. Just be honest with yourself about how long you'll actually stay in the home. If you're moving within two or three years, the higher rate will cost you more than the upfront credit saves you. The math is usually clear enough once you lay out the total cost over your expected ownership period. FHA closing costs aren't complicated, but they do have enough moving parts that skipping the detailed review is a mistake. Get multiple estimates, factor in the MIP, ask about assistance programs, and don't treat the first number you see as the final word. The process works well when you understand what you're actually paying for.


