How FHA Closing Costs Actually Work (And Why You Need a Real Calculator)
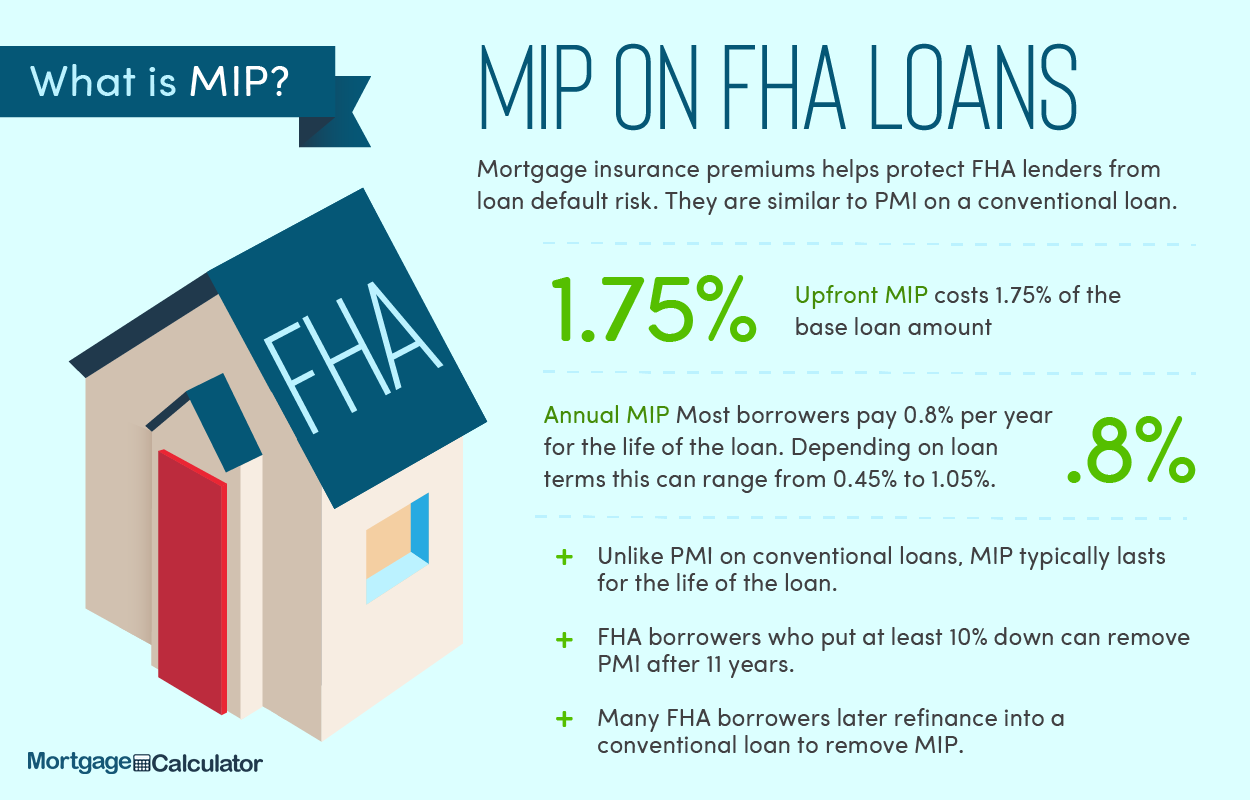
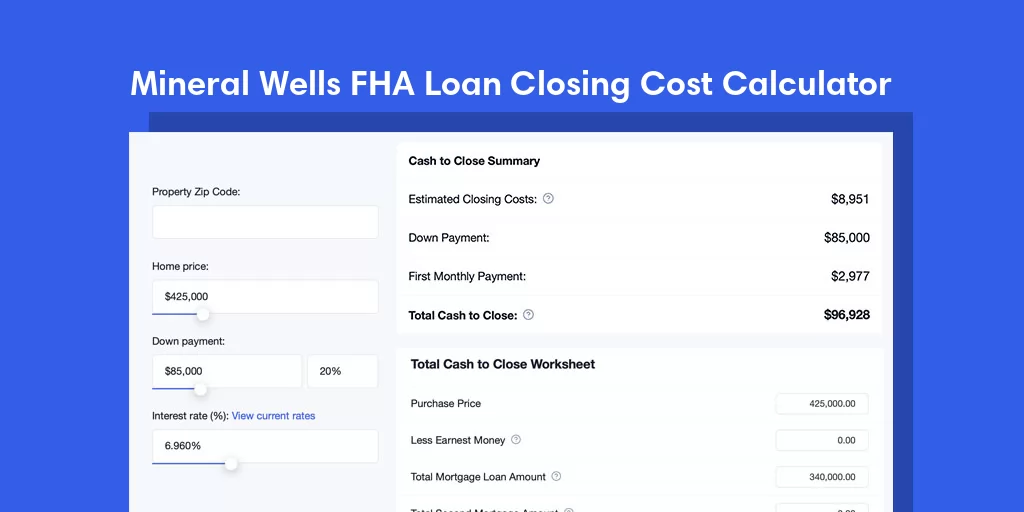
FHA closing costs run anywhere from 3% to 5% of the loan amount, but that range is basically useless without understanding what's inside it. Most people I talk to when they first ask about a Fha Home Loan Closing Cost Calculator have no idea that the upfront mortgage insurance premium (UFMIP) alone adds 1.75% to their loan balance, and they aren't prepared for how that reshapes their entire number. The calculators online give you clean outputs, but they won't tell you about the edges where things break. A proper calculator breaks your total down into the buckets an FHA loan requires. Origination fee — typically 0.5% to 1% of the loan amount, though some lenders charge flat fees that don't scale. Appraisal — FHA requires a specific appraisal, and it runs $500 to $800 depending on your market, sometimes higher if the property needs extra inspection work. Credit report — standard $30 to $75. Flood certification if you're anywhere near water — that's about $15 to $25 on its own. Title search and title insurance — this varies wildly by county. Settlement or processing fee — $100 to $400. Recording fees and government transfer taxes — also county-dependent. And then there's the UFMIP at 1.75% of the base loan amount, rolled into your mortgage balance rather than paid out of pocket. That last one is the big difference from conventional loans, and it's why FHA closing costs look different even on the same purchase price. I ran into a specific problem last year with a borrower in Ohio who had an FHA refinance where the calculator I was using didn't account for the lender's 1% origination cap adjustment under certain county-specific FHA guidelines. The closing disclosure came back $840 higher than the calculator had predicted. What happened was the county had a local transfer tax that FHA guidelines require to be itemized differently than conventional loans, and the software I was pulling from hadn't been updated for that county's latest assessment. The workaround was to pull the HUD-1 from a recent comparable FHA transaction in that same township and add the differential manually. Took about twelve minutes to cross-reference and adjust the estimate.
How to Use a Calculator Without Getting Lied to
Here's the part nobody mentions — most free calculators online assume your loan amount is the purchase price minus your down payment. That's wrong for FHA. Because the UFMIP gets rolled into the loan, your actual financed amount is higher than you think. If you're buying a $250,000 home with 3.5% down, your base loan is $241,250. But then you add the UFMIP of 1.75% on top of that, which brings your total loan to about $245,469. A sloppy calculator will show you closing costs based on the smaller number. Always verify it's calculating UFMIP on the correct base. Another thing — sellers can contribute up to 6% of the purchase price toward your closing costs on an FHA loan. Some calculators don't factor that in, and you'll see a total you can't actually achieve because the seller credit would cover half of it. When I'm building estimates for clients, I always run the number both ways — with and without seller assistance — so they understand the full range. It usually takes about five minutes to set up both scenarios, and it saves a lot of confusion later when the real numbers land.
When a Calculator Falls Apart Completely
FHA calculators are fine for rough estimates. They fail hard when you get into edge cases. Co-op purchases, manufactured homes, non-occupant co-borrowers, and second liens all trigger FHA-specific adjustments that generic tools don't handle. I had a situation last spring where a borrower wanted to use an FHA loan with a non-occupant parent as a co-borrower to qualify for the payment. The calculator I was using didn't have a field for that scenario and completely misestimated the required documentation fees. The actual extra costs — additional credit reports, employment verification, and a second appraisal in some cases — added roughly $600 to the closing table. The fix was to manually add the known add-ons for co-borrower scenarios, which I track in a spreadsheet that's been updated for about eight years now. If you're doing anything outside a straightforward purchase with a primary residence and a single occupant, don't trust the online tool alone. Get a Loan Estimate from at least two lenders and compare the line items directly. That's the only way to catch the discrepancies, and it usually reveals a $400 to $1,200 difference between lenders that the calculator never would have shown you.
Get the Full Details
A Note on What You Actually Save Using a Calculator
The honest answer is that a calculator saves you maybe ten minutes of manual math. The real value isn't in speed — it's in not being blindsided. I've seen borrowers show up to closing with cash short by nearly $2,000 because they trusted a generic estimate that didn't include their county's specific recording fees and transfer taxes. The calculator gave them a number that looked right until the HUD-1 arrived. Budget with a buffer of at least 0.5% above whatever the tool tells you. That covers the variables the software can't account for, and it's the margin that keeps you from having to scramble the night before closing.