What You Need to Know About FHA Rates When You've Got Good Credit
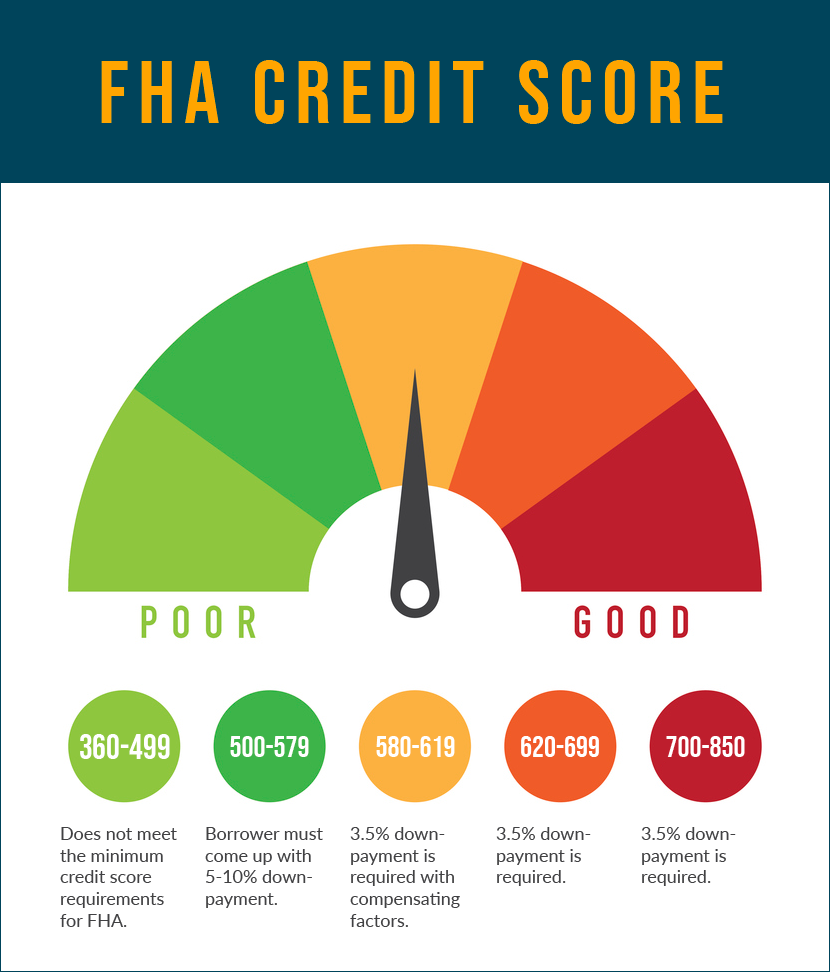
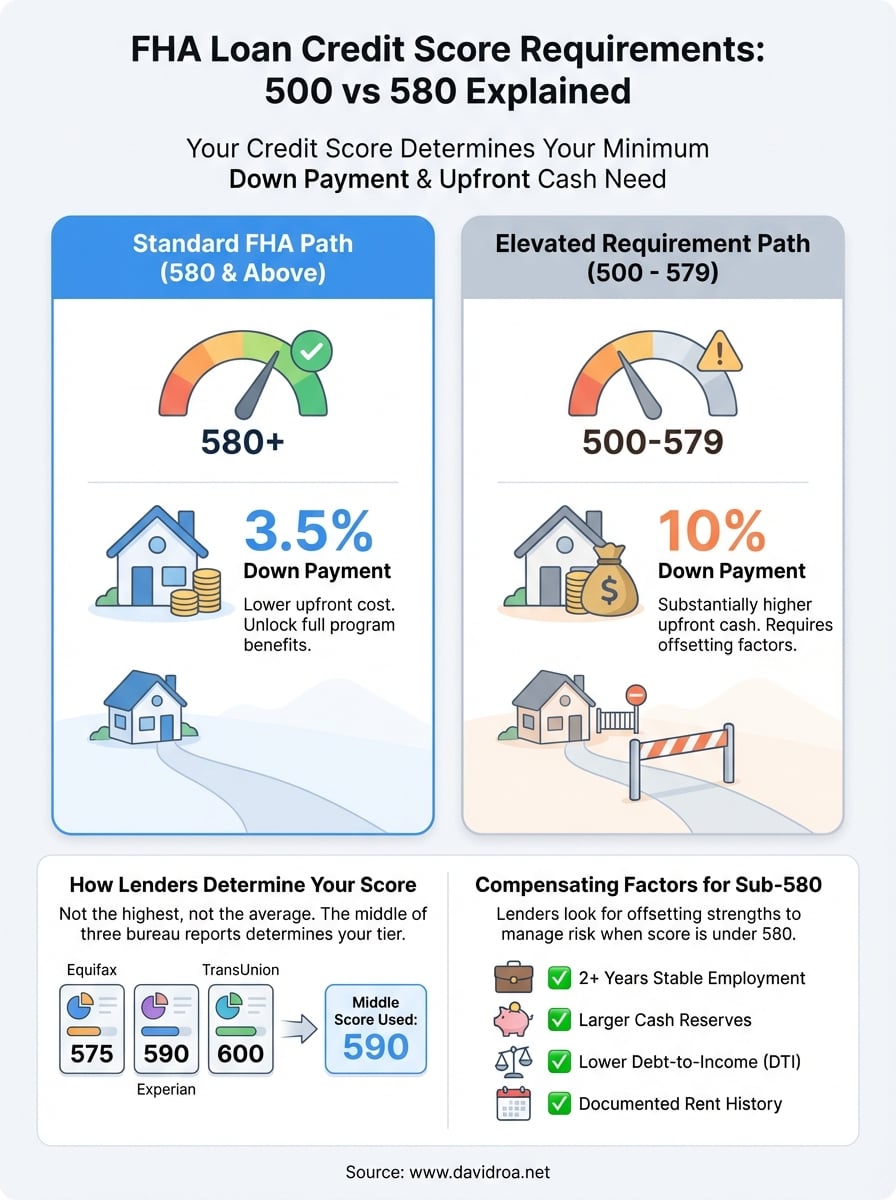
If you have an 800 credit score and you're looking at an FHA loan, here's the straightforward truth: your score won't get you the absolute lowest rates available, but it will put you in a solid position within the FHA program. FHA loans are backed by the Federal Housing Administration, and they are designed primarily for borrowers who might not qualify for conventional financing. That means the rate structure works differently than conventional loans. With an 800 credit score, you are well above the FHA minimum of 580 for the standard 3.5% down payment, and you also clear the threshold for the lower down payment tier. But FHA rates don't drop as dramatically as conventional rates do when credit scores go up. The spread between someone with a 740 score and someone with an 800 on an FHA loan is usually in the range of 0.125 to 0.25 percent, sometimes less. It varies by lender and by market conditions.
Fha Interest Rate With 800 Credit Score
The actual rate you will see depends on several factors beyond just your credit score. The loan amount matters. The geographic location matters. The loan term matters. And the lender's own pricing model matters a lot. Right now, FHA rates are based on the broader mortgage market, so I would check current listings before making any assumptions. An 800 score gets you the best rate a given lender will offer on their FHA products, but it does not guarantee the lowest rate in the entire market. For that, you would typically be looking at a conventional loan. One thing people miss is how FHA mortgage insurance affects the total cost. Even with a perfect credit score, you pay an upfront mortgage insurance premium, usually 1.75 percent of the base loan amount, and an annual premium that gets divided into monthly payments. This is true regardless of your credit tier. So the slightly higher rate compared to conventional can feel frustrating when you see the bigger picture. On a $350,000 home with a 3.5% down payment, your loan amount is about $337,750. The upfront MIP is roughly $5,910. The annual MIP runs around 0.55 percent for a 30-year fixed with a down payment above 5 percent, which adds about $155 per month to your payment. That monthly MIP stays for the life of the loan on most FHA purchases unless you refinance later. I dealt with this exact situation a while back. A client had an 802 score and was trying to compare an FHA offer against a conventional one from the same lender. The FHA rate was only 0.18 percent higher, which looked great on paper, but when we ran the numbers including the MIP, the conventional loan actually saved about $240 a month after accounting for the lower rate and no mortgage insurance. The client ended up going conventional with 5 percent down, which required a score of 620 minimum, and that score far exceeded it. The lesson here is not to look at the interest rate in isolation. You have to look at the total payment including mortgage insurance, closing costs, and your planned time horizon in the home.
Another detail that does not get enough attention is how lender overlays work. Some lenders set their own minimum credit score requirements above the FHA guideline of 580. I have seen lenders require 620 or even 640 for FHA loans, and some will not touch anything below 660. Your 800 score clears every single one of those, but if you are shopping around, you need to ask each lender about their overlays before you spend time on a full application. It saves you from getting declined at the underwriting stage for something the FHA itself would have approved. There is also the question of discount points. With an 800 score, you have strong negotiating leverage on points, whether you are going FHA or conventional. One point costs one percent of the loan amount and typically drops the rate by about 0.25 percent. Whether it makes sense to buy points on an FHA loan depends on how long you plan to stay in the home. If you are staying five years or more, buying down the rate usually makes mathematical sense. If you are moving in three years, it probably does not. I calculate this by comparing the total cost of points against the monthly savings, then dividing to get the breakeven in months. On a $337,750 loan, one point costs $3,377.50. If it drops your rate from 6.5 percent to 6.25 percent, your monthly principal and interest saving is roughly $66. That is a breakeven of about 51 months. After that, you are ahead. If you are curious about the current FHA Interest Rate With 800 Credit Score, the most reliable approach is to pull rates from at least three different lenders, preferably including one credit union and one online lender. Credit unions often price FHA loans more aggressively because they are member-focused and do not have the same shareholder pressure. Online lenders tend to have lower overhead and can pass that along. Branch lenders might match or beat them, but you have to ask them to.
Get the Full Details
One more edge case that catches people off guard: FHA streamline refinances. If you already have an FHA loan and your rate is higher than what is available now, a streamline refinance can lower it without a new appraisal or full underwriting. With an 800 score, you should absolutely consider this if your current rate is more than 0.75 percent above current market rates. The process usually takes two to four weeks and the costs are lower because there is no full credit redo or appraisal. I have done this for several borrowers who locked into FHA loans during a rate spike and wanted out without the hassle of a full refinance. It is one of the most underutilized tools in the FHA toolkit. The bottom line is that an 800 credit score is a strong asset in the FHA world, but it is not the decisive factor it is in the conventional world. The rate advantage is real but modest. The mortgage insurance is the real cost driver. Shop multiple lenders. Compare total payments, not just rates. And if your financial situation allows it, a conventional loan might serve you better overall despite the higher down payment requirement.