What You're Actually Paying At An FHA Close
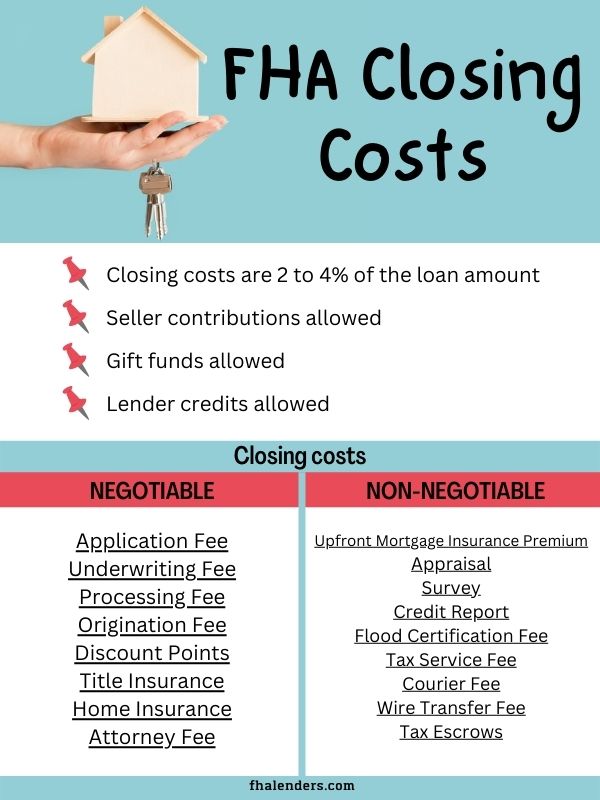
FHA closing costs are the fees you pay to get a house loan approved and funded under the Federal Housing Administration program. They sit alongside the principal and interest of your mortgage, and they typically run between two and five percent of the loan amount. On a $250,000 loan, that is roughly $5,000 to $12,500 out the door before you even think about moving in. The breakdown matters because some of these costs are negotiable and some are not. Lenders can shop around for certain services, but government-mandated fees and third-party appraisals are fixed in practice. Knowing which is which saves you money without any fancy strategy.
Fha Loan Closing Costs
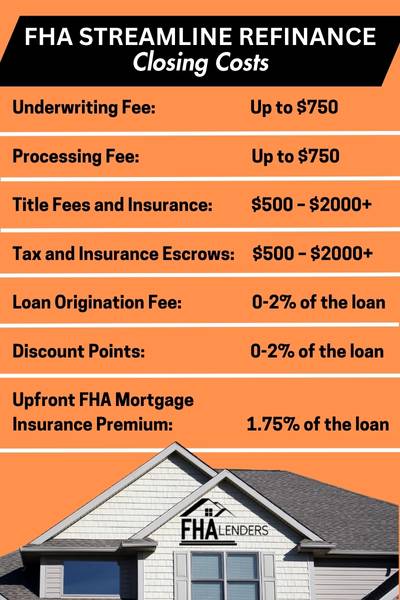
Here is how they actually break down on a typical FHA transaction. Origination charges from the lender usually run between zero and one point, so you might see a flat fee of $1,000 to $2,500 or a percentage match to your interest rate. Appraisal fees sit around $500 to $750 depending on the county and property type. Credit report pulls are usually $30 to $75 total across the three bureaus, though some lenders bundle this into an application fee that can hit $100 to $300. Government recording fees vary wildly by county. In some places you are looking at $150 total. In Miami-Dade County, you could be paying over $600 for the same documents. Title insurance is where people get confused. FHA requires a lender's title policy, and that runs about 0.5 to 1 percent of the loan amount in most states. An owner's title policy is optional under FHA but strongly recommended, and it usually costs an additional 0.5 to 1 percent as a one-time premium. Escrow setup is a big one that surprises first-time buyers. FHA mandates an initial escrow deposit equal to at least six months of estimated property taxes and hazard insurance, plus a cushion of up to two months. On a $250,000 home with $3,600 in annual taxes and $1,200 in insurance, you are looking at roughly $3,000 to $4,000 going into escrow at closing just to seed the account. Survey fees, if required by the lender, run $400 to $800. Flood certification is usually $15 to $30, and a full flood determination comes in around $80 to $150 if the property is in a designated zone.
Pest inspection or termite reports cost between $75 and $200 depending on the region. In the southern states, these are basically mandatory for FHA and will delay your closing if they come back with active infestation. Home inspection is not an FHA requirement but nobody should skip it, and a standard inspection runs $350 to $500.
Get the Full Details

How To Estimate Your Specific Numbers
The Loan Estimate form is your primary tool here. Lenders are required by law to deliver this within three business days of receiving your application, and it breaks every cost line by line with good-faith estimates. Compare at least three Loan Estimates before you commit. The numbers will look similar on the surface, but small differences in origination charges, title fees, and escrow calculations add up fast. One thing most people miss is that the Loan Estimate resets its accuracy clock every time you submit a new application. If you apply with one lender, then go to a second lender two weeks later, the first estimate has expired and you cannot compare them side by side. Get both at roughly the same time or ask the first lender to update their numbers with the same purchase contract terms. Another trick that works more often than it should: request a broker price opinion or a comparative market analysis from your agent before you even apply. If the purchase price is coming in above recent sales in the neighborhood, your appraisal gap could eat into your closing cost budget faster than you expect. FHA appraisals are stricter than conventional ones, and if the house does not meet minimum property standards, the repair requirements get added to your closing tab.
A Specific Problem I Dealt With
I ran into this last year with a client purchasing a townhome in Chesterfield County, Virginia. The title search revealed an old utility easement from 1978 that had never been recorded properly. The seller's attorney wanted $2,500 in title insurance premium increase just to clear the defect. Our original Loan Estimate had listed title insurance at $1,800 based on the preliminary commitment. That $700 jump was not reflected anywhere in our closing disclosure until the final document arrived three days before closing. The workaround was straightforward but annoying. I pulled the actual title commitment document, identified the exception number causing the issue, and sent it to our title company with a request for a rate lock on the original premium. They honored it because the defect was discovered after the initial underwriting, not before. If you notice any discrepancy between your Loan Estimate and Closing Disclosure, flag it immediately. The tolerance rules under TRID (TILA-RESPA Integrated Disclosure) are strict, and lenders can absorb certain increases but not all of them.
Counter-Intuitive Things Nobody Tells You
First, paying points to buy down your rate is often a worse deal on FHA loans than on conventional loans. FHA already has a maximum loan amount that limits your equity cushion, and combining points with a lower rate does not necessarily improve your debt-to-income ratio enough to qualify for better pricing tiers. In my experience, keeping the rate at the standard offering and using those points as a credit toward closing costs almost always nets the borrower more value. Second, the FHA upfront mortgage insurance premium, commonly called the upfront MIP, is calculated on the base loan amount, not the full financed amount including your closing costs. Some lenders try to roll your entire closing cost package into the loan and then charge upfront MIP on a higher number. That is legal but expensive. On a $250,000 loan, rolling $8,000 in costs versus keeping them separate changes your upfront MIP by roughly $350 to $400. It sounds small until you add the annual MIP on top. Third, you can negotiate with your lender about which fees are lender-controlled and which are third-party. Origination charges, application fees, and processing fees are almost always adjustable. Appraisal, credit report, and flood cert are pass-through costs. If a lender is quoting you $500 for an appraisal when local comps show $600, they are making margin on it. Ask for the actual invoice from the appraiser. Most willing lenders will reduce or remove the markup if you push.

The Limitations And When This Strategy Fails
Negotiating closing costs works best when you have a strong credit profile and a low loan-to-value ratio. If your credit score sits below 620 or you are putting less than five percent down, lenders have less room to bend on fees because the risk premium is already baked into your pricing. In those cases, you are mostly competing on rate and upfront MIP, and the negotiation leverage shifts heavily toward the lender. Another scenario where negotiating closing costs falls apart is a cash-out refinance. FHA streamline refinances have capped fees and strict guidelines, but a full cash-out refi allows lenders to charge almost everything they want. The TRID tolerance rules still apply, but the initial estimates are wider, and the final numbers can swing by several thousand dollars depending on the lender's internal fee schedule. Finally, seller concessions can only cover up to six percent of the purchase price on FHA loans. This is a hard cap, not a guideline. If your closing costs exceed six percent of the price, you are paying the difference out of pocket. I have seen borrowers get caught by this when they assumed the seller would cover everything. The math is simple: six percent of a $200,000 purchase is $12,000. If your real closing costs total $14,500, you cover $2,500 regardless of what the seller agrees to.
Practical Steps To Manage The Process
Start by ordering your Loan Estimate from at least three lenders simultaneously. Use the same purchase contract and the same assumed interest rate for each so the comparison is fair. Line up the items that differ: origination charges, title fees, and escrow requirements. Ask each lender to explain any fee that seems higher than the others. When you receive the Closing Disclosure, compare it line by line with your Loan Estimate. Under TRID, most fees can only increase by ten percent from the original estimate without giving you a new waiting period. Certain fees, like government recording fees and transfer taxes, have zero tolerance and cannot increase at all. If you see a variances larger than expected, request a corrected disclosure before you close. Keep copies of everything. Appraiser invoices, title commitment documents, Lender's settlement statements. If a dispute arises three months after closing, you will need paper trails, and digital screenshots of your original Loan Estimate are the most reliable evidence you can produce. Lenders sometimes adjust fees during underwriting without notifying the borrower, and the only way to catch it is by comparing final numbers against the original estimate.
The bottom line is that FHA closing costs are predictable once you know the categories and the tolerance rules. The real cost driver is rarely the government fees. It is the lender-originated charges and title insurance premiums, and those are the ones you can actually influence with a little research and a willingness to ask questions.