What the FHA Manual Underwriting Checklist Actually Is
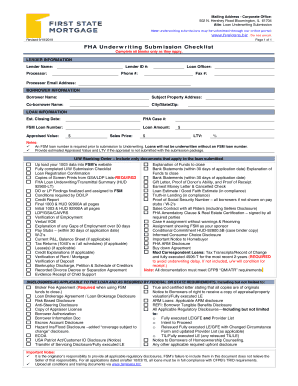
The FHA Manual Underwriting Checklist is essentially a decision tree HUD built into the Single Family Housing Policy Handbook (4000.1). It's the step-by-step logic that underwriters follow when determining whether a loan file meets FHA's credit, collateral, and eligibility requirements. Most people encounter it when their automated system either approves a refinance or pushes it to manual review. The checklist itself lives in Appendix B of the handbook, but practically speaking it's embedded in the DU Lender Insights tool and the FHA Connection underwriting module. I spent about six years working in FHA production and then another three doing quality control reviews. The reason I'm mentioning this is because the checklist has some quirks that nobody teaches in training. You'll read the document and think it's straightforward. Then you'll hit an edge case and realize the guidance is genuinely ambiguous on a few points.
Fha Manual Underwriting Checklist
The core of the checklist covers three main areas: creditworthiness, collateral, and mortgage eligibility. Under creditworthiness you're evaluating the borrower's ability to repay based on documented income, residual income, credit history, and debt-to-income ratios. For collateral you're looking at property value, condition, and insurability. Mortgage eligibility touches on loan amount, amortization terms, and documentation requirements. Here's the thing most people miss about the Fha Manual Underwriting Checklist. The residual income requirement is often treated like it's optional or secondary. It's not. If you're underwriting in a higher-cost area, the residual income thresholds from Table 2B of the handbook become binding, not suggestive. I had a file get tossed because an underwriter approved a refinance with a DTI of 43 percent and residual income below the HUD threshold. The loan got pulled in post-close QC. The borrower lost their appraisal fee and the closing cost credits we'd agreed to. That's a real consequence, not a theoretical one. Another common pitfall involves employment gaps. The handbook says a gap of less than six months needs explanation but doesn't always mandate documentation. I found a few underwriters interpreting that as "explain it verbally and move on." The correct approach is to document the explanation in writing, even if the gap is only two or three months. When I audited files, I'd see cases where the only record of an employment gap was a checkbox marked "explained" in the comments section. That doesn't hold up. The explanation needs to be substantive: layoff notice, separation agreement, a statement from the employer, or a documented search for new employment.
How to Work Through the Checklist in Practice
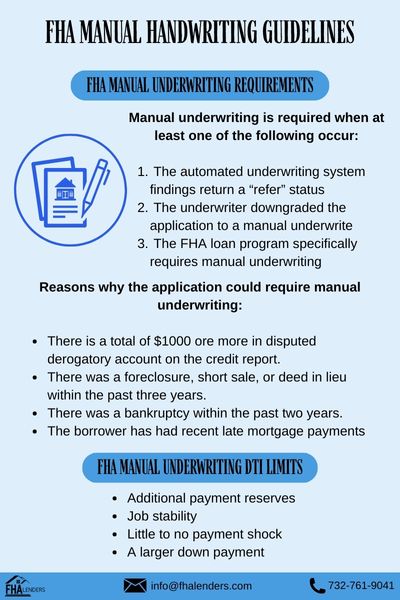
Start with the borrower's credit profile. Pull the three bureau scores and note the middle score. The manual underwriting path typically comes into play when the middle score falls between 580 and 620, or when there are derogatory items that the automated model flags. Below 580, you're generally not getting FHA approval unless there's a compelling compensating factor, which is rare. From there you move through the credit history review. You need to verify every derogatory item: collections, charge-offs, late payments, judgments, and bankruptcies. The handbook requires that each be addressed and resolved or explained. For collections over $2,000, HUD expects to see a payoff letter or a documented repayment arrangement. I've seen too many files where a collection was marked "paid" with a one-line note and no actual payoff documentation. That gets rejected in QC every time. The debt-to-income analysis is where most manual underwriting files stall. You're calculating both the front-end and back-end ratios. The standard FHA maximum is 31 percent front-end and 43 percent back-end for most cases, though higher ratios are permissible with strong compensating factors. The tricky part is what counts as a recurring monthly obligation. Minimum payments on revolving accounts must be included even if the borrower carries a zero balance. Student loans under forbearance or income-driven repayment need to be calculated at 0.5 percent of the unpaid balance or the payment shown on the credit report, whichever is higher. This rule gets missed constantly.
Get the Full Details
Income documentation follows the same path as conventional underwriting with one key difference: FHA accepts stated income for certain loan types, but if you're doing manual underwriting on a standard purchase or refinance, you still need full verification. Two years of tax returns, W-2s, and pay stubs. For self-employed borrowers, the Schedule C review is non-negotiable. I once saw a file where the underwriter accepted a year-one of business income without verifying the prior year. The borrower's business had operated for three years but only filed one tax return. That's not sufficient, period.
Common Problems and What to Do About Them
The biggest issue I encounter in manual underwriting files is inconsistent application of the compensating factors. The handbook lists several: significant residual income, substantial cash reserves, a demonstrated ability to manage similar housing expenses, minimal remaining debt after the mortgage, or a history of timely payments despite current high obligations. The problem is that "substantial" is never defined in dollar terms. Some underwriters treat reserves of two months' PITI as substantial. Others require twelve months. The safer interpretation is six months of reserves for borderline cases and twelve months when the credit profile has additional weaknesses. Another headache is the treatment of non-occupant co-borrowers. Their income can be used to qualify the borrower, but only if they have a bona fide ownership interest in the property and the mortgage. I've seen underwriters accept income from a co-signer who wasn't going to take title. That's a QC red flag. The fix is simple: verify that the non-occupant co-borrower is listed on both the purchase contract and the mortgage instrument. Property-related issues under the manual checklist often come down to health and safety defects. The FHA appraisal must identify any conditions that affect the livability or structural integrity of the property. Repairs required by the appraiser must be completed before closing or placed in escrow with a completion timeline. I remember one file where the appraiser flagged a cracked slab foundation in the garage. The underwriter marked it as "noted" and approved the loan without requiring a repair. The file was rejected in post-close review six months later. The borrower had to come back and fix the slab. The lender faced a claim payout. This is the kind of mistake that costs money, not just time.
Where the Process Breaks Down
Manual underwriting through the FHA checklist is slow. Even with the automated tools, a complete manual review typically takes three to five business days for a straightforward file. Complicated cases with self-employment income, multiple credit issues, or property defects can stretch to two weeks. The bottleneck is usually the documentation requests. Each RFE (request for additional information) adds three to four days to the timeline because you're waiting on the borrower or the appraisal management company. The other limitation is that the FHA manual underwriting process doesn't adapt well to non-standard income situations. Gig economy income, cryptocurrency earnings, and foreign income are growing faster than HUD's guidance has evolved. There's no clear pathway in the checklist for verifying crypto income. The workaround most underwriters use is to accept bank deposits that can be traced to exchanges, paired with a signed explanation from the borrower. It's not ideal, but it's the closest thing to a standard that exists right now. If your loan file involves a complex income situation or a property with unusual characteristics, you might be better off exploring conventional underwriting instead, depending on the borrower's overall profile. Conventional guidelines around non-traditional credit and alternative income documentation are more developed. The tradeoff is that conventional loans don't offer the lower down payment options that FHA provides, so it depends on what the borrower actually needs.
The takeaway is that the Fha Manual Underwriting Checklist is a functional framework but not a foolproof one. It requires judgment calls that aren't explicitly defined in the handbook, and those judgment calls are exactly where files get rejected in quality control. The most reliable approach is to be more conservative than the minimum requirements, document every assumption, and make sure every piece of the file tells the same story from start to finish.