What You Need to Know About FHA Loan Rates Right Now
FHA rates move differently than conventional mortgage rates, and if you're tracking them without understanding why they do what they do, you'll end up frustrated. The FHA program itself doesn't set rates. Lenders do. The government just backs the loan and sets minimum guidelines like credit score floors and mortgage insurance requirements. What you're actually seeing when you look up Fha Rates Today is a collection of offers from dozens of lenders, each pricing their own risk differently. The good sources are your lender's rate sheet, LoanPrice's FHA section, or the HUD website's approved lender directory. The bad sources are aggregator sites that pull from one wholesale price and slap five different lenders' names on it. I've seen borrowers argue with their loan officer for 20 minutes over a rate difference that turned out to be an error on the aggregator site. Don't bother until you've checked the actual source. Most lenders update their FHA rate sheets daily, sometimes twice a day during volatile market periods. A rate you see at 9 AM can be gone by lunch if the bond market moves. This is standard across all mortgage products, not just FHA, but it trips people up because FHA borrowers often have more time constraints - they usually need to close faster than conventional buyers due to seller expectations and appraisal contingencies.
How FHA Rates Are Actually Priced
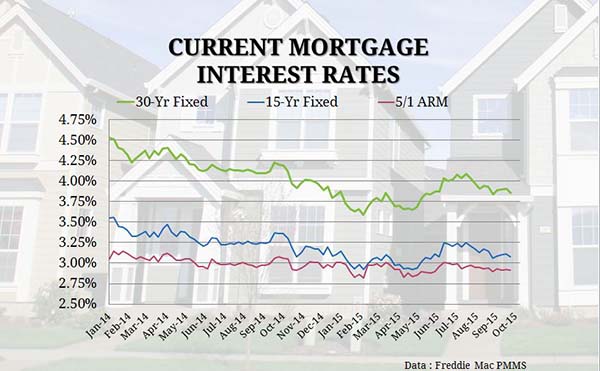
Understand the mortgage spread first. Lenders price FHA loans as a Treasury yield plus a spread. The 30-year average maturity Treasury is the benchmark. When that yield moves up a quarter point, your FHA rate moves up roughly a quarter point, give or take based on lender competition in your area. The spread itself is what varies between lenders and that's where the real negotiation happens. Here's something most rate calculators won't tell you: FHA rates are often slightly higher than conventional rates for the same borrower profile right now, which is backwards from what most people expect. The FHA mortgage insurance premiums make the overall cost higher even when the interest rate looks competitive. Lenders also price in the fact that FHA loans have stricter property requirements, which means more potential headaches during underwriting. That friction gets baked into the rate. The upfront mortgage insurance premium is 1.75% of the loan amount, added to your loan balance. The annual MIP ranges from 0.55% to 0.78% depending on loan term and down payment. That annual MIP stays for the life of the loan on anything with less than 10% down and a 30-year term. You can only remove it by refinancing into a conventional loan once you hit 20% equity. This is critical because it changes your actual borrowing cost significantly.
A Problem I Ran Into With FHA Rate Shopping
Last year I was helping a client who had perfect credit, 6.5% down, and needed to close in 28 days. We were comparing three FHA offers and one looked dramatically cheaper. The rate was 6.12% versus 6.89% and 7.05% on the others. Everything matched on the Loan Estimate except the lender's flood certification fee, which was $95 instead of the usual $25. We dug into it and the cheaper rate came with a mandatory origination discount that only applied if the loan funded by a certain date that had already passed. The lender had forgotten to adjust it. The real rate was closer to 6.45% after fees. It cost us two days to re-negotiate, but we caught it before she signed anything. The workaround is simple but most people skip it: ask for the fully priced rate after all lender credits and discounts are applied, not just the advertised interest rate. Get the annual percentage rate and the total closing cost estimate side by side. The gap between the APR and the note rate tells you how expensive the fees actually are.
Get the Full Details

What Actually Moves FHA Rates Week to Week
The Treasury yield curve is the main driver. Nonfarm payroll numbers, CPI releases, and Fed statements will shift rates in the morning trading session. If you're rate-locking, lock early in the week. Friday afternoon locks get painful because you're carrying the lock for eight days and the market could move against you over the weekend with no way to react. Secondary drivers specific to FHA: the FHA loss reserve fund health affects lender willingness to write these loans. When the fund gets thin, lenders raise spreads or pull out of certain zip codes entirely. I've seen entire counties go lender-stranded on FHA for a few months after the fund dropped below $1 billion. Check the FHA Mutual Mortgage Insurance Fund status quarterly if you're doing volume work. Right now the fund is in okay shape but it's worth monitoring if you're timing a purchase.
Fha Rates Today vs. Where They're Heading
No one can predict short-term rate movements with any reliability. The best you can do is lock when your financial picture is stable and your timeline allows. If you have 45 days to close and the market is trending up, lock at day 30 and let the rest ride open if it goes down. Most contracts allow a lock extension for a small fee, usually 0.125% to 0.25%. Cheaper to pay that than to lose your rate entirely. The counterintuitive part that most first-time FHA buyers miss: a lower rate isn't always better if it comes with aggressive points you don't need. Paying one point to drop 0.375% on a $350,000 FHA loan costs $3,500 and saves you roughly $130 a month. Break-even is 27 months. If you plan to move in three years, the math works. If you plan to stay ten years, it works even better. If you're uncertain about your timeline, stick with the no-point rate and keep your cash available.
When FHA Is Actually the Wrong Choice
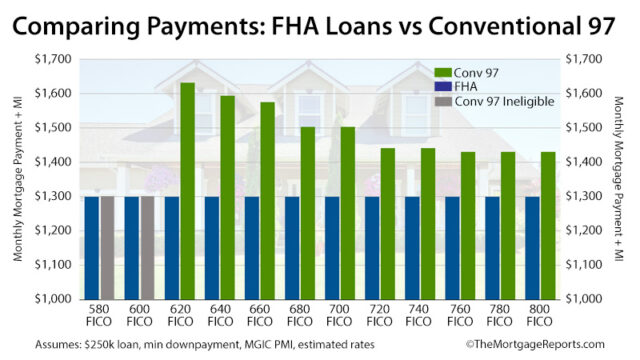
If you can put 20% down and qualify for conventional rates, FHA almost never makes sense anymore. The lifetime MIP on a below-20% down conventional loan doesn't exist. Conventional private mortgage insurance drops off at 78% LTV automatically. You'd need to stay in the home for roughly seven to nine years just to break even on the FHA upfront premium plus the annual MIP versus conventional PMI, not counting the rate difference. FHA shines when you have a credit score below 620, when you're doing a gift down payment from a family member, or when the property has minor condition issues that conventional appraisers would reject. The minimum credit score is technically 500 with 10% down, but most lenders won't touch anything below 580. Some will go to 580 with just 3.5% down. The tradeoff is you're accepting higher long-term costs for easier qualification. There's also the debt-to-income flexibility angle. FHA allows higher DTI ratios than conventional, usually up to 50% with strong compensating factors. Conventional lenders typically cap out around 45%. If you have student loans or car payments eating into your ratio, FHA might be the only path to homeownership at a reasonable rate.

Check your current numbers against at least three lenders before committing. Rates vary enough between institutions that shopping is worth the effort, even if you think your situation is straightforward. The difference between your best offer and your worst offer on an FHA loan can easily exceed half a percentage point, which is thousands of dollars over the life of the loan.