How the FHA Rental Income Calculation Worksheet Actually Works
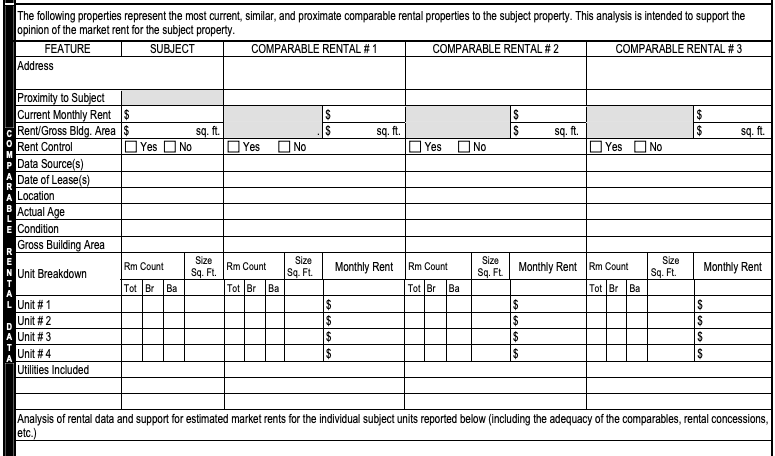
The FHA rental income calculation worksheet is a form lenders use to determine how much rental revenue you can count toward your qualifying income when you're buying a property that already has tenants, or when you own a rental property and want to factor its earnings into your debt-to-income ratio. The short version: lenders don't just take whatever the tenant pays. They apply a vacancy and management factor and only count a percentage of the gross rent. The exact percentage depends on what your current situation looks like. If you're dealing with an existing rental property, the most common calculation is straightforward. You take the actual lease amount, subtract between 25% and 30% to account for vacancy, credit loss, and management fees, and the remainder is your qualifying rental income. That 25% to 30% figure isn't arbitrary. It comes from the FHA guidelines that acknowledge most landlords don't collect 100% of their stated rent month over month. I've seen a lot of deals fall apart because the lender was being too aggressive on the deduction side and still came in under water. Or the opposite happened, where the appraiser used a market rent that was $200 higher than the actual lease and the borrower had no choice but to argue with the appraisal file to get it corrected. That's a whole separate headache but it's worth knowing about. For a property you're purchasing and plan to rent out immediately after closing, the calculation is different. In that case, you use the lesser of the lease amount or the appraised market rent, minus the same 25% vacancy and management deduction. Appraisals matter more here because if the appraiser comes in low on the rental comparison, your income gets reduced across the board. I had a borrower last year who locked in at a $2,400 monthly lease. The appraiser looked at comparable rentals in the area and concluded the market rent was $2,150. The lender used $2,150, subtracted 25%, and came out to $1,612 in qualifying income. If we had done nothing, the loan wouldn't have closed. Instead, the borrower provided three rental comparisons that were closer to the lease amount, and the appraiser revised the number upward. It added two days to the timeline, but it was faster than losing the deal entirely.
One thing that catches a lot of people off guard is how negative rental income can affect the application. If you already own a rental property and your expenses exceed the income, the shortfall gets added to your monthly debt obligations. That's right. A money-losing rental property doesn't just sit there neutrally. It actively makes it harder to qualify on another home. I've seen people who had been managing their rental fine for years get surprised when they tried to refinance or buy another property and suddenly the vacancy and management deductions turned a modest profit into a loss on paper. The fix is usually timing. Pay down the mortgage on the rental to reduce the debt service portion, or wait until the property has been owned long enough that the lender doesn't count it as a rental obligation anymore. There are edge cases that the worksheet doesn't really cover cleanly. Here's one that comes up more often than it should. If you have a tenant on a month-to-month lease rather than a signed year-long agreement, some lenders will still accept it, but others want to see a lease with at least 11 months remaining. I worked with a borrower who had a tenant who had been in the unit for five years, paid on time every month, and was on a month-to-month basis. The lender's underwriter initially said the income didn't count because there was no lease term. The workaround was simple but not obvious. We pulled a letter from the tenant confirming they intended to stay and pay the current rent, and we provided twelve months of bank statements showing consistent deposit activity. The underwriter accepted it, but it added a call and a couple of days. Knowing this upfront would have saved time.
The Core Components of the Worksheet
The worksheet itself asks for specific information and the answers you provide determine the final number. You need the gross monthly rent, the property address, whether you currently own the property or are purchasing it, and the length of the lease. The lender will also ask for the vacancy and management deduction percentage, which is typically 25% but can go up to 30% depending on the lender's internal guidelines. Then there's the question of whether you have property management fees, HOA fees, or other operating expenses that might factor in separately. Most of the time those don't enter the calculation at all. The worksheet is designed to be lean. Add too much detail and the underwriter will just ask you to simplify it anyway. I should note where the process breaks down. The FHA rental income worksheet works well for conventional single-family rentals with a standard lease and a stable tenant. It struggles when you're dealing with multi-unit properties where only some units are occupied, or when the rental history is short, or when the tenant is a relative. I've seen lenders reject rental income from a sibling paying below-market rent, and I've seen them accept it when the borrower could prove the rate was arm's length by providing comparable rentals in the neighborhood. The rule of thumb is that any rental income needs to be verifiable, and "verifiable" means paper trails. Lease agreements, bank deposits, tax returns, all of it.
Get the Full Details

Common Mistakes That Delay Approval
The most frequent problem I see is borrowers overstating their rental income by using gross rent instead of the amount that actually lands in their account. If your tenant pays $1,800 but they also reimburse you for $150 in utilities, the gross rent is $1,800 and the landlord's portion is $1,650. The lender will use the gross rent, apply the vacancy deduction, and then you end up with a number that feels wrong because you never actually collected that full amount. This doesn't usually cause a denial but it does cause confusion and sometimes a request for clarification that slows things down. Another mistake is not having the documentation ready when the lender asks for it. The worksheet isn't useful unless you can back it up. Tenants change. Leases get renewed. If you're relying on a verbal agreement or an expired lease, the lender will treat that income as nonexistent. I had a client who provided a rental income worksheet with a lease that had expired three months prior. The underwriter flagged it immediately. The borrower went back, got the tenant to re-sign, and resubmitted within 48 hours. It cost nothing in terms of the loan approval but it did add a couple of days to the timeline. Getting the documentation right the first time is always better than fixing it later.
Where the Worksheet Doesn't Help
The FHA rental income worksheet is a tool for a specific purpose. It calculates qualifying rental income for underwriting. It does not determine your actual cash flow. It does not tell you whether a property is a good investment. It does not replace a pro forma or a market analysis. If you're using it to decide whether to buy a rental property, you need to do your own research on expenses, appreciation, and tenant quality. The worksheet is just one input in the lending decision. It can be the difference between approval and denial, but it's not the whole picture. Lenders also look at credit score, employment history, reserve requirements, and the overall debt-to-income ratio. Rental income is a piece of that puzzle, not the entire thing. One final note on a specific scenario. If you're buying a multifamily property with two to four units and you plan to live in one of them, the FHA has specific guidelines that let you count rental income from the other units. The calculation is the same 25% deduction, but the property needs to be appraised as a multifamily home, and the lease terms need to be documented. I've seen this work smoothly, and I've seen it fall apart because the borrower tried to use a verbal agreement with a cousin who was going to rent the second unit. Verbal agreements don't cut it for FHA multifamily income calculations. Get everything in writing before you apply.