Why most beginner investing advice is useless (and what actually works)
I spent roughly four years trading individual stocks before I stopped doing it altogether. The reason wasn't that the market was too hard—it's that the advice being fed to people starting out was designed for engagement, not for getting results. Most guides tell you to pick winners. The ones that actually work for regular people tell you to stop picking winners entirely. That distinction matters more than anything else in this conversation. A Field Guide For Investing For Beginners is really just a structured way of saying: here is a set of rules that have survived multiple market cycles, written for someone who doesn't have time to monitor positions all day. The core concept is simple, but people keep complicating it because the simple version doesn't sound exciting. Diversified, low-cost index funds held over decades. That's it. That's the entire strategy. The boring truth is that this approach beats most actively managed funds and dramatically outperforms the vast majority of retail traders over a 10-year window.
The mechanics of what you're actually doing
When you invest in an index fund, you aren't betting on a company. You're betting on the economy as a whole. A total market fund like VTI or FDRM holds roughly 3,700 to 4,000 U.S. stocks. The S&P 500 holds 500 large-cap ones. The point is that whichever company fails gets replaced automatically by the next one that grows into the index. You never have to decide. The rebalancing happens on schedule. Your job is to contribute consistently and leave the money alone. The fee structure is where most beginners get tripped up. An expense ratio of 0.03% on a $10,000 position costs you three dollars a year. The same amount in an actively managed fund with a 1.25% expense ratio costs you $125. Over 20 years with annual contributions, that difference compounds to tens of thousands of dollars lost to fees. I learned this the hard way in 2016 when I finally crunched the numbers on a fund I'd been holding since college. Switching to a comparable zero-commission index fund cost me about 20 minutes and saved roughly $4,200 in fees over the next decade at my contribution level. It wasn't a dramatic revelation. It was just arithmetic. Dollar-cost averaging is the other mechanism that sounds fancier than it is. You invest the same dollar amount on a set schedule—say $500 every month—regardless of whether the market is up or down. This means you buy more shares when prices are low and fewer when they're high, without having to time anything. It removes emotion from the equation entirely. The data from Vanguard and Fidelity consistently shows that people who set up automatic contributions and forget about the account accumulate significantly more wealth than those who try to time entries and exits.
What nobody tells you about the early years
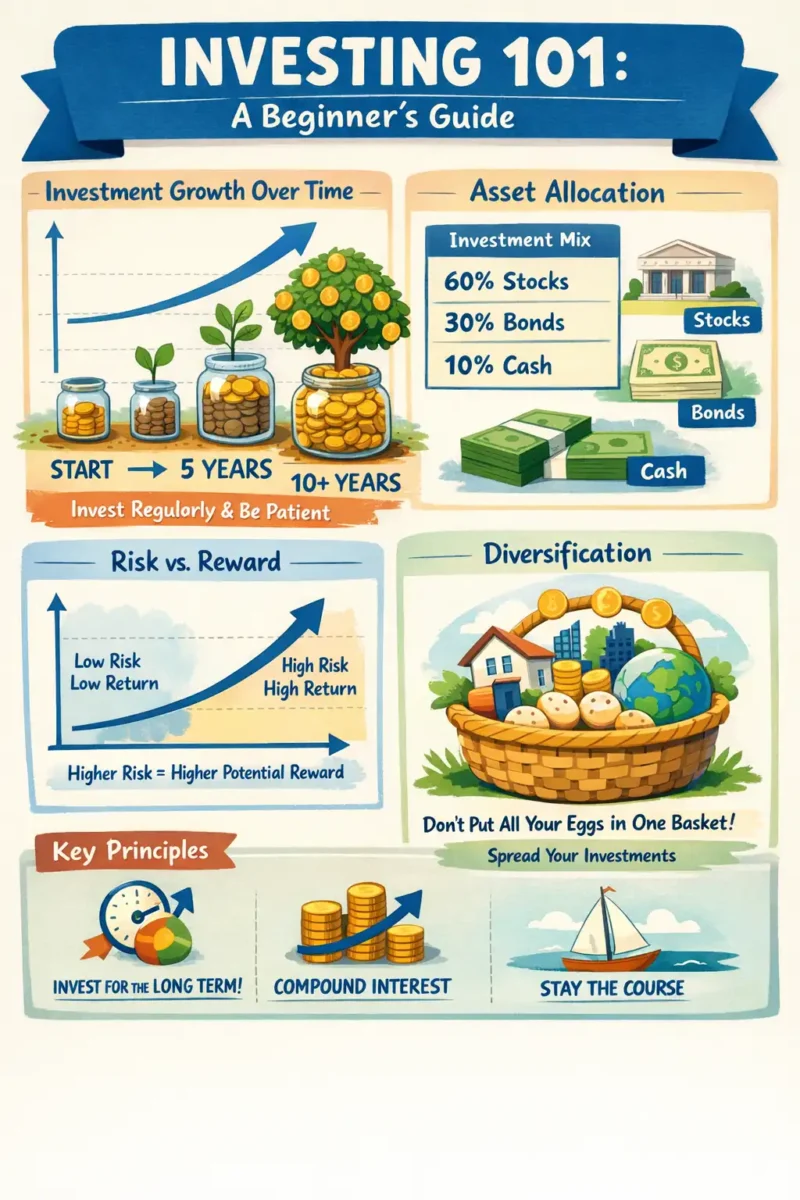
The first three to five years of investing are psychologically the hardest part, not because the strategy is difficult but because nothing appears to be happening. If you put away $500 a month at a 7% average annual return, after five years you'll have about $34,000. Of that, roughly $4,000 is growth. It looks like you're making progress on a spreadsheet, but your actual returns are barely visible against the contributions. This is the phase where most people bail. They check the account, see their money isn't doubling, and conclude the strategy doesn't work. It works fine. You just haven't given it enough time for compounding to dominate your contributions. Another thing that doesn't get discussed enough is tax inefficiency in non-qualified accounts. If you hold individual stocks and sell them in a taxable brokerage account, you trigger capital gains events. Index funds are far more tax-efficient because they generate minimal turnover, but they still produce distribution income. Holding them in an IRA or 401(k) eliminates the tax drag entirely. I discovered this around 2019 when I was reviewing my own portfolio for a friend and noticed he had about $8,000 in short-term gains he hadn't anticipated because he was trading individual tech stocks inside a regular brokerage account. Moving his core allocation into index funds inside a Roth IRA cut his expected tax liability to near zero and simplified his life considerably. Here's a more specific edge case. In 2022, when the market dropped roughly 19%, a lot of beginner investors panicked and sold. The practical problem was that many of them had allocated everything to a single-sector fund—usually technology or semiconductors—because that's what they'd heard about on social media. Their portfolio wasn't diversified at all, just concentrated in one direction. The workaround is straightforward: ensure your stock allocation includes both U.S. total market and international total market funds, and consider adding a bond fund if you're under 40 and want to reduce volatility. A simple 90/10 or 80/20 stock-to-bond split doesn't mean you're being conservative. It means you're sleeping better when markets fall, which is what actually lets you stay invested long enough for the strategy to work.
Get the Full Details
The practical steps for getting started
Open a brokerage account. Vanguard, Fidelity, and Charles Schwab all offer zero-commission index funds with expense ratios below 0.10%. Link your bank account and set up automatic monthly transfers. The amount doesn't need to be large. Even $100 per month works if that's what your budget allows. The consistency matters far more than the size. Pick your funds. A basic two-fund portfolio looks like this: one total U.S. stock market index fund and one total international stock market index fund. A common split is 80% domestic and 20% international, though 70/30 or 90/10 are both reasonable depending on your view of valuation and diversification. Add a bond fund if you want to reduce portfolio swings. That's the entire portfolio construction. No research required on individual companies. Set it and ignore it. Check your account once per quarter at most. Rebalance annually if your allocation drifts more than 5 percentage points from your target. That's it. The work is in the discipline of showing up every month, not in analyzing charts or reading earnings reports.
Where this approach actually breaks down
Index fund investing assumes you have a time horizon of at least seven to ten years. If you need the money within three years, this strategy is the wrong tool. Bonds or high-yield savings accounts are more appropriate for short-term goals. The market can and will drop significant amounts in any given year, and there is no protection against that if you need the funds on a fixed timeline. There's also a behavioral limitation. This strategy delivers average returns, which means during bull markets you will consistently underperform the hottest stock or sector. Watching someone make 300% on a single meme stock while your portfolio is up 8% in the same period feels terrible even though it's the rational choice. Most people can't handle that feeling and abandon the strategy right before it would have paid off. This is the single biggest reason people fail at investing, and it has nothing to do with the method itself. If your goal is to beat the market rather than match it, you need a different approach entirely. Active management, sector rotation, or individual stock picking are valid strategies but they require substantial time, skill, and emotional control. They also have a historically poor success rate for retail investors. The Field Guide For Investing For Beginners isn't designed for people who want to get rich quickly. It's designed for people who want to get wealthy slowly and without stress. Those are different objectives, and mixing them up is where most people go wrong.