How Motorbike Finance Actually Works In Practice
Most people approaching motorbike finance are already confused by the time they walk into a dealer or click on a website. The terminology alone — HP, PCP, secured loan, direct lending — reads like a glossary someone pulled together without testing it on a human being. I spent years sitting on the other side of these conversations, which means I know where things go wrong before they go wrong.Finance A Motorbike: What You Actually Get
The Main Routes Available
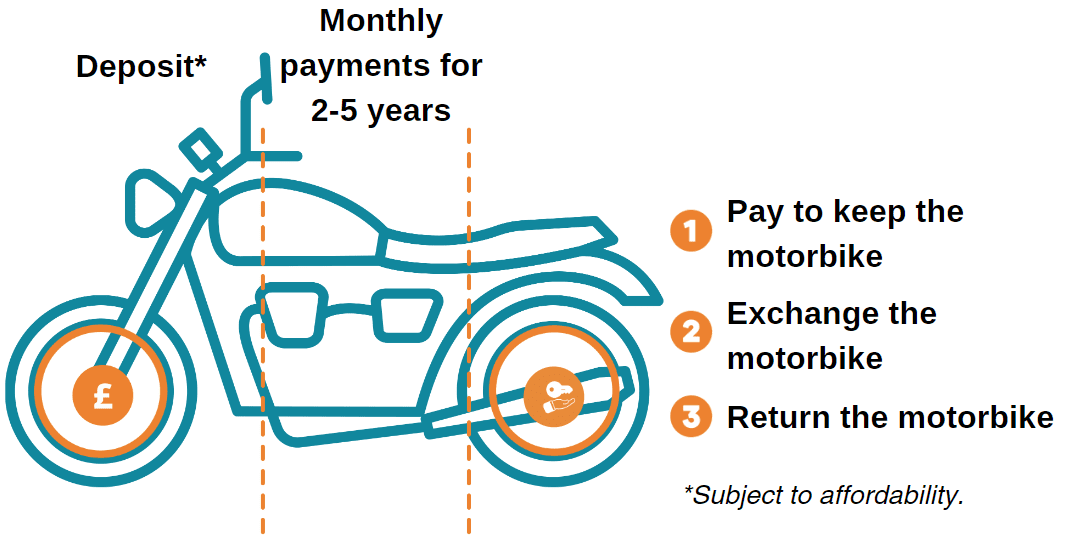
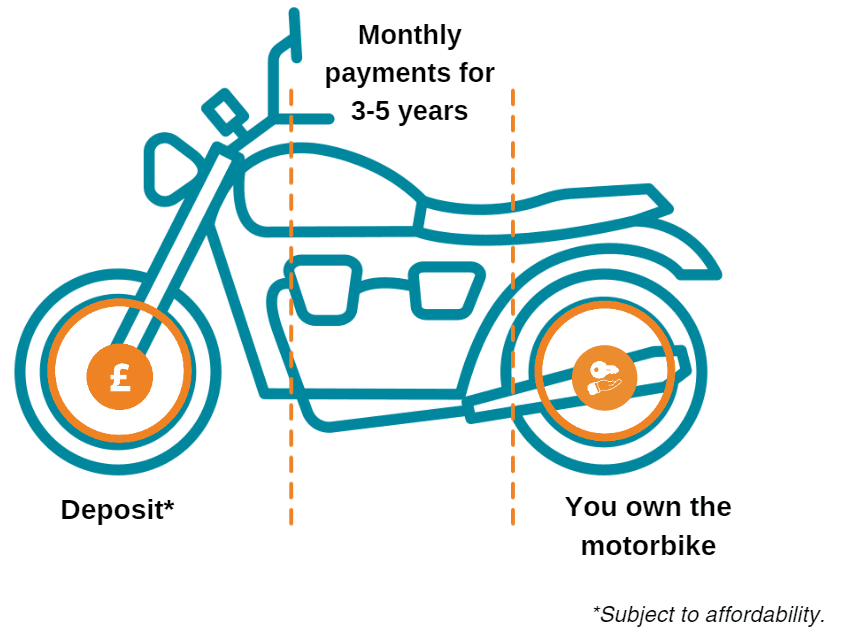
Personal Contract Purchase (PCP) is the most common option on high-street dealerships. You pay a deposit, fixed monthly payments for the term, and then you have a balloon payment at the end if you want to own the bike outright. If you don't pay the balloon, you return the bike. Simple in theory. In practice, the residual value set at the start determines everything about your monthly cost, and residual values are often set optimistically by finance companies — which means your monthly payment looks lower than it should. I've seen the same bike model priced with a £2,000 difference in residual just between two lenders on the same day. Personal Hire Purchase (HP) is the more straightforward route. You pay a deposit and fixed monthly payments until the bike is yours. No balloon payment. No guesswork about future value. The downside is the monthly outlay is higher than PCP, and the credit check is usually just as hard. But the math is transparent. Every payment brings you closer to ownership. No surprises. Secured loans and unsecured personal loans sit outside the manufacturer-backed options entirely. A secured loan uses the bike as collateral but can sometimes offer better rates if you have equity elsewhere. An unsecured personal loan is completely separate from the asset. The catch with both is that you own the bike immediately, which sounds great until you miss a payment and your credit file takes a hit the same way it would with any other credit product. The lender doesn't automatically repossess because you're financing a motorbike rather than a car.
Dealer arrange finance is what most people encounter first. The dealer acts as a broker, sending your application through their panel of lenders. This is convenient but introduces a margin. The dealer may accept a slightly higher rate and keep the difference. That is not universal, but it is common enough that you should always ask for the annual percentage rate before signing anything.
How To Actually Compare Options
The first thing I tell people is to get a decision in principle before you look at bikes. A decision in principle is a soft search that tells you roughly what you can borrow and at what rate. It does not leave a permanent mark on your credit file in most cases. Doing this takes ten minutes and saves you from falling in love with a bike you cannot afford to finance. A full credit application does leave a hard search, and those stack up. Three hard searches in six months will noticeably drop your credit score, regardless of whether any of them are approved. Once you know your budget, the next step is comparing the total cost, not the monthly payment. Monthly payments are designed to look manageable. The total amount repayable tells the real story. A £200 monthly payment over 36 months is £7,200. Add the deposit and any optional extras bundled in, and you now have the full picture. I once worked a deal where the monthly looked competitive until the finance company had rolled a £400 administration fee and a £200 gap insurance product into the principal. The bike was £5,500. The total repayable was £7,800. That is a realistic example, not an outlier.
Get the Full Details
Where I Went Wrong With My First Finance Deal
When I was financing my first used bike through a dealer, I accepted the first quote without asking about the optional products. The dealer added a protection plan that covered mechanical breakdown for the term of the finance. It looked reasonable on paper. The problem was that the finance company required me to take it as a condition of the deal, and the cost was £1,200 over three years. The coverage had a £250 excess per claim and excluded anything related to the chain, sprockets, or fairings. For a motorbike, that is almost every wear-and-tear item. I cancelled it within the cooling-off period — which is fourteen days under UK regulations — but only because I had read the terms carefully before signing. The workaround was straightforward: get a separate motorbike maintenance plan from a specialist provider at roughly half the cost, with terms that actually cover motorcycles instead of cars with two wheels slapped onto them. Imported bikes create a specific problem with finance. Many UK lenders will not touch a bike that has been imported and re-registered unless it was purchased through an authorised UK dealer. The reason is straightforward — they cannot reliably assess the residual value or verify the service history. If you are importing a bike, you will likely need a specialist lender or a cash purchase. The rate difference is significant, typically 2 to 4 percentage points higher than what a domestic bike would attract. Motorcycles are classified differently from cars for tax purposes, and this affects finance in a way most riders do not expect. Bike finance is treated as a secured agreement for VAT purposes, which means the interest portion is subject to VAT while the capital portion is not. Some lenders factor this into their APR calculations and some do not. Always check whether the quoted rate includes VAT on the interest component. A difference of 20 percent VAT on the interest can add hundreds to the total cost over a typical PCP term.
Early repayment is another area where people get caught out. Most motorbike finance agreements allow early settlement, and you are legally entitled to a rebate on the interest if you pay off the balance early. However, some agreements include an early settlement fee that can offset part of that rebate. I have seen fees of up to one month's payment charged on settlement. Always request a payoff quote in writing before you decide to clear the finance early. The oral figure the lender gives you over the phone is not binding, and it is rarely the final number.
When Finance Is a Bad Call
Motorbikes depreciate faster than cars, and the depreciation curve is steeper in the first two years. If you are buying a new bike and financing it on PCP, you are often paying interest on an asset that loses a third of its value before your first payment is even due. Cash purchases or short-term HP agreements make more financial sense for older used bikes where the value is already flattened out. A three-year-old naked bike in good condition will not drop significantly in value over the next three years, so financing it on HP is a reasonable compromise if you do not have the cash available. The alternative to dealer finance is going direct to a motorcycle-specialist lender. Companies like MotoNovo, Zwivel, and Bikesure focus exclusively on motorbike finance and tend to have more accurate residual models because they understand how bikes depreciate differently across categories. A sports bike depreciates on a different curve than a cruiser or an adventure bike, and generalist lenders often apply car residuals to both. Specialist lenders do not make this mistake as frequently, and the monthly difference can be meaningful.
Practical Steps Before You Sign
Check your credit report first. One discrepancy on your report can change your rate by a full percentage point or more. Use a free service like Experian, Equifax, or TransUnion to pull your file. Fix any errors before you apply. Missed payments show for six years, but incorrect defaults that have been marked as satisfied should be flagged and corrected. Read the fine print on mileage limits. PCP agreements typically include annual mileage caps of 2,000 to 5,000 miles. Exceeding this results in excess mileage charges at the end of the term, usually calculated at 8 to 12 pence per mile. For a rider who covers longer distances, this can add thousands to the final cost. HP agreements do not have this problem because there is no balloon payment and no mileage restriction at the end. Keep every document. Finance agreements generate paperwork that you will need if you ever want to challenge a charge, request a payout figure, or prove ownership. Digital copies are fine, but save them in more than one place. Finance companies merge, acquire, or lose records. I had to chase down a payoff statement for a bike I sold four years after the finance was cleared, and the original lender had been acquired twice in the intervening period. The digital trail was the only thing that made it solvable.