Setting Up Finance Cheat Sheet Quick
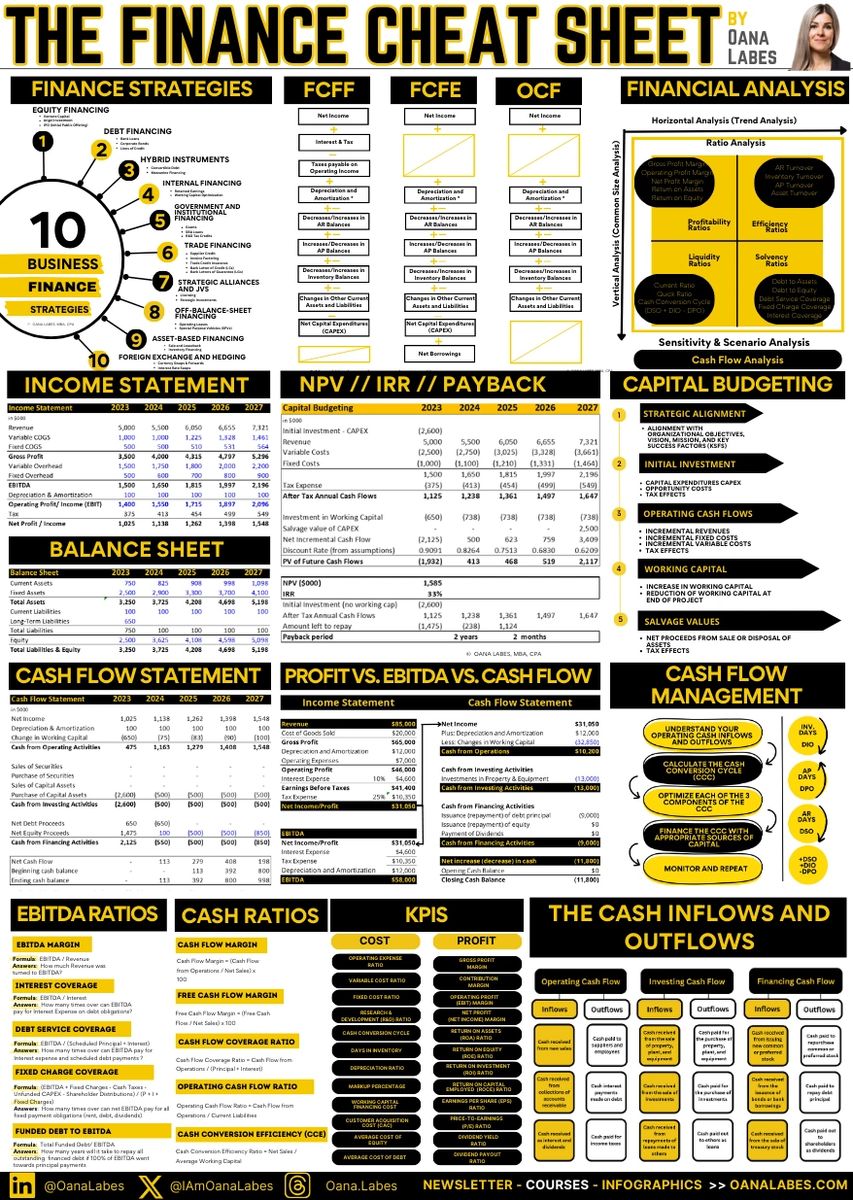
Most people who end up looking for a Finance Cheat Sheet Quick are either dealing with a spreadsheet that has lost all coherence, or they're starting a new project and want to avoid reinventing the calculation framework from scratch. The tool itself is essentially a collection of pre-built templates covering common financial calculations—NPV, IRR, amortization schedules, sensitivity analysis setups, and the like. You download it, plug in your own assumptions, and you have a working model in roughly 20 minutes instead of spending half a day building something that probably has a broken cell reference somewhere. The download is typically a single Excel workbook or a compressed folder containing multiple tabs organized by calculation type. Open it up. Do not immediately start editing cells. I learned that the hard way after a client noticed discrepancies in my month-three projection and I spent three hours tracing a circular reference that was actually just me overwriting a lookup table in the wrong sheet. The first thing to do is freeze the layout, then identify which input cells you're going to need to modify for your scenario. The input section is usually color-coded or at least clearly marked. These are the only cells you should be touching. Everything else is driven by formulas that reference those inputs. If you find yourself needing to change a formula, stop and think about whether the formula is wrong or whether your input assumption needs adjustment. In my experience, about 90 percent of the time the formula is fine and the input is what needs fixing.
What You Need to Know Before Using It
Finance Cheat Sheet Quick covers the standard calculations well enough, but there are a few things that trip people up regularly. The IRR function inside the template uses Excel's default IRR calculation, which assumes cash flows occur at regular intervals and uses a default guess of 10 percent. If your cash flow pattern is irregular or your returns fall far outside that guess range, the calculated IRR will be wrong. I ran into this on a project last year where the cash flows had two large outflows separated by a gap of nine months before any inflows appeared. The template spit out an IRR of 4.2 percent, which was obviously incorrect given the underlying returns. I switched to using XIRR with explicitly dated cash flows instead, and the result came to 18.7 percent. Still need to make sure your dates are accurate, but at least the formula accounts for the timing mismatch. Another thing to watch: the template's amortization schedules assume level payments unless you manually adjust the payment structure. If you're working with interest-only periods or balloon payments, the pre-built schedule will mislead you. I've seen this cause real problems in deal presentations where someone just ran the numbers through the sheet without verifying the payment structure matched their actual loan terms.
The Limitations
This tool is not going to handle complex derivatives pricing, stochastic modeling, or anything that requires Monte Carlo simulation. It is built for standard corporate finance and investment analysis workflows. If you need scenario analysis with more than three variables changing simultaneously, the template gets clumsy. You can do it, but you will be fighting the layout instead of working with it, and you will probably introduce errors in the process. For that kind of work, a purpose-built modeling environment or a Python-based approach is more reliable. The versioning is also worth noting. There is no built-in change tracking or audit trail. If multiple people are working on the same file, someone is going to overwrite someone else's assumptions. Keep a copy of the original template before you start modifying it, and name your working file with a date stamp.
Get the Full Details

When to Use It and When to Walk Away
If you need a quick NPV or payback period calculation for a straightforward project, this saves you maybe 90 minutes of setup time. The sensitivity tables alone would take an hour to build from scratch if you are not very fast with Excel. If you are doing a detailed investment memo with five different scenarios and a full downside case, you might save an afternoon. That is reasonable. If you are in an industry with non-standard cash flow patterns—real estate development with phased capital calls, infrastructure projects with construction periods longer than the standard 12-month assumption in the template—you need to adjust the structure yourself. The template is a starting point, not a finished product. I would recommend opening it up, reading through every formula, and confirming each one does what you think it does before you put it in front of anyone else. Two minutes of verification now prevents two hours of damage control later.