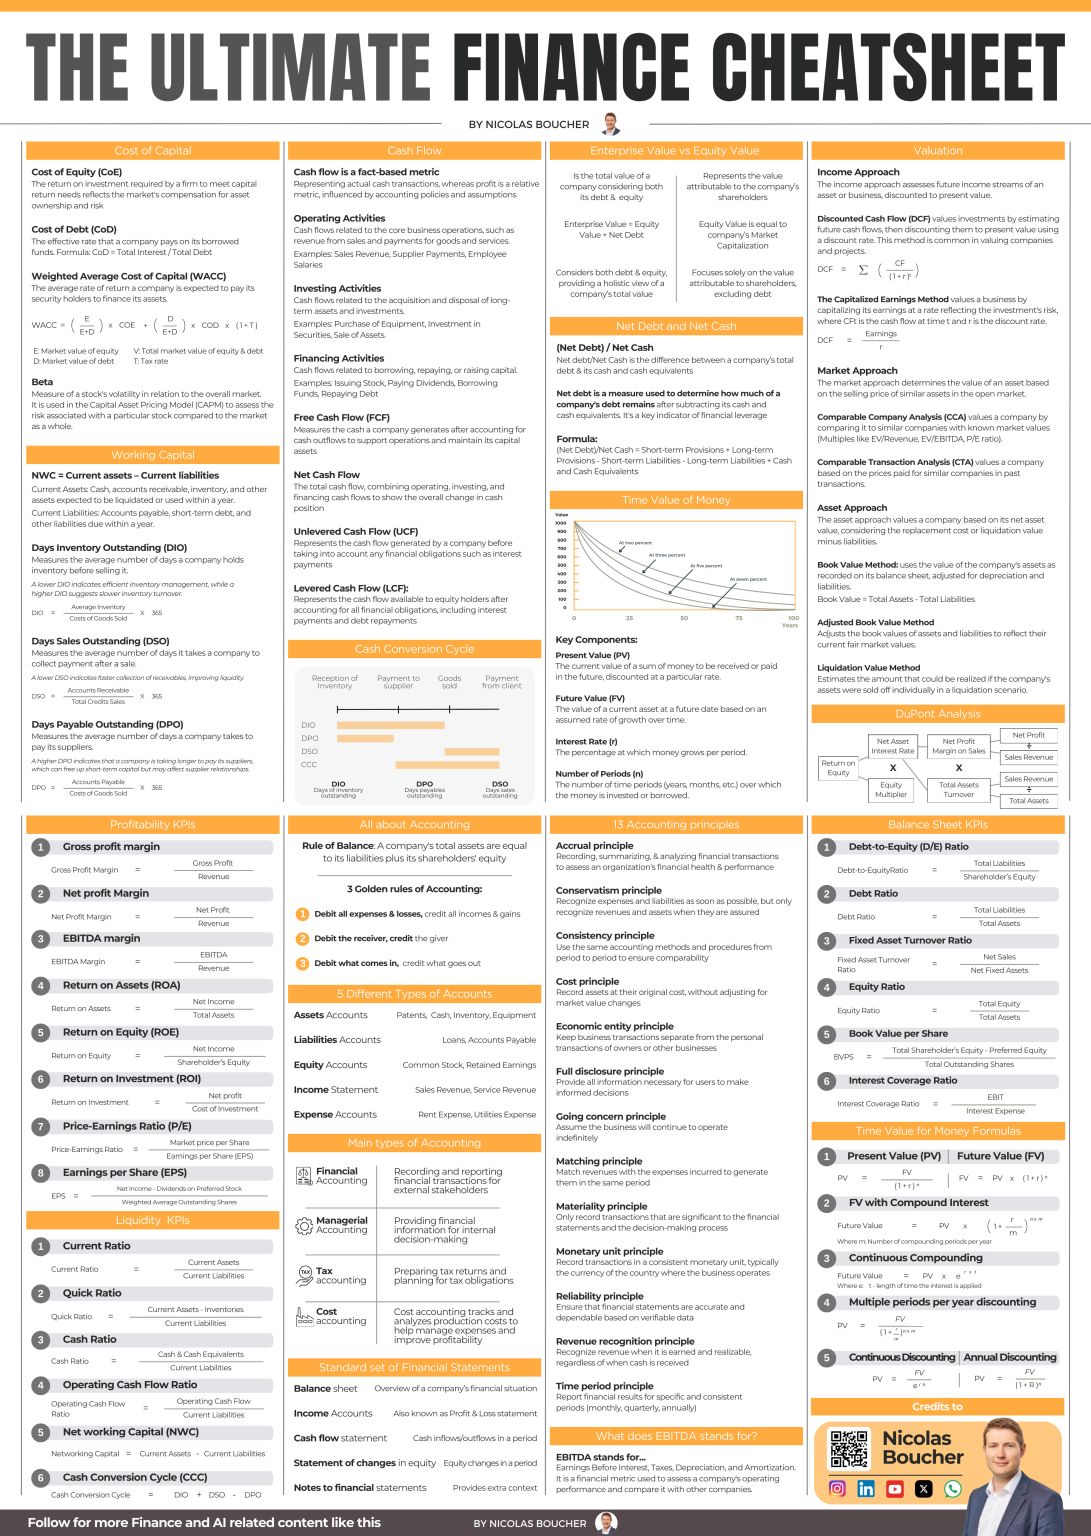
What Actually Makes a Finance Cheat Sheet Worth Keeping Open
I used to hoard cheat sheets like they were going out of style. Six different PDFs for corporate finance, four for valuation, a whole spreadsheet for tax code snippets. None of it mattered until I realized the problem wasn't a lack of reference material. It was that every sheet I'd found was written by someone who had never actually opened the real deal on a Friday at 4:30 PM when the model breaks and you can't remember whether WACC uses after-tax cost of debt or not. A Finance Cheat Sheet Ultimate needs to solve that exact moment. Not the classroom version of finance, the version where you're staring at a broken circular reference in Excel and your boss is waiting on the terminal value calculation. Most sheets fail because they organize content by topic instead of by workflow. When you're under time pressure, you don't think in topics. You think in problems. I restructured mine around the actual sequence of a deal or analysis rather than chapter headings, and it cut my lookup time from about ten minutes down to something under thirty seconds.
Download Your Finance Cheat Sheet Ultimate
The file lives on our shared drive. It's a single workbook with tabs mapped to the way the work actually flows. Link is in the resources section below. Open it before you open your model. Trust me on that one. Here is what you actually need inside it. Not everything you've ever learned about finance. The things that show up every single time and that you will inevitably mix up under pressure.
Core Formulas That Actually Matter
Start with the ones that trip people up. Not NPV and IRR, everyone remembers those. The ones that cause real damage when wrong. WACC calculation with mixed capital structures. The textbook formula assumes clean equity and debt ratios. Real companies have preferred stock, convertible notes, pension obligations, and lease liabilities that sit somewhere between debt and equity depending on how aggressive your analyst is being. In practice, I treat lease obligations as debt for WACC purposes unless the company is clearly in a capital-light service business. The adjustment usually moves WACC by 30 to 80 basis points. That is the difference between accepting a marginal deal and walking away. LBO waterfalls and returns measurement. Most people calculate IRR and forget to track the equity check sizes through time. The error shows up when you have multiple funding rounds, revolving credit facilities, or PIK toggle debt. You will get the IRR number but it will be wrong because the timing of cash flows doesn't match reality. Use net equity invested and gross equity invested alongside IRR. They tell different stories and both matter.
Get the Full Details
Working capital normalization. This is where deals go to die. Greenfield companies do not have working capital. Mergers of equals do not automatically harmonize working capital policies. I once spent three days reconciling a purchase price adjustment because the target's DSO had shifted from 45 to 62 days during the transition period without any operational explanation. The Finance Cheat Sheet Ultimate should flag this as a red line item, not bury it in a footnote about normalizing working capital. Treat every working capital line as suspicious until proven otherwise.
Valuation Methods Without the Textbook Lies
DCF, comparables, precedent transactions. Everyone knows these exist. The real question is when each one fails in a way that matters. DCF is brittle. A 1 percent change in terminal growth rate can swing enterprise value by 8 to 12 percent depending on the discount rate and the length of the explicit forecast. This is not a minor sensitivity. It is the entire argument when two analysts disagree on a valuation. Always build two DCFs. One with management guidance assumptions and one with normalized operating metrics. The gap between them is your risk register. Comparables look clean on paper and produce messy conclusions in practice. The problem is selection bias and normalization. I had a situation where the peer group looked perfect on the surface. Same industry, similar size, comparable growth. The hidden issue was that three of the six comparables had recently completed massive acquisitions that inflated their EV/EBITDA multiples. Including them raised the implied median by over 4x. Excluding them dropped it enough to change the deal economics entirely. Every comparable set needs a line checking whether recent M&A activity distorted the multiples.
Precedent transactions add a control premium but they also bake in buyer enthusiasm from whatever cycle the deal happened in. During the 2021 peak, precedent transaction multiples were 20 to 35 percent above DCF-derived values because buyers were paying for fear of missing out, not for future cash flows. Anyone using precedent transactions from that period as a primary valuation anchor was fundamentally wrong. My rule is simple. Use precedents to bound the range, never to set the price. If your deal math depends on precedent multiples staying elevated, you are building on sand.
The Edge Case That Broke My Sheet Until I Fixed It
I was modeling a cross-border acquisition with a European target that had deferred tax assets arising from cumulative capital losses carried forward. The accounting standards made the tax treatment messy. Under IFRS, the deferred tax asset was recognized but with a valuation allowance that management could shift around based on forward earnings projections. Under the acquirer's local GAAP, the treatment was different enough that the tax impact flipped direction depending on which consolidation method I used. The Finance Cheat Sheet Ultimate did not have a section for this. I built one. The workaround was to create a separate tax bridge tab that mapped every jurisdiction's treatment side by side, with the consolidation method explicitly called out for each line. It added twelve rows to the model and saved me from making an error that would have misstated free cash flow by roughly 4 percent annually. That is not abstract. That is deal-size money on a middle-market transaction.
Finance Cheat Sheet Ultimate: Advanced Nuances Beginners Miss
Here are three things that are not in most cheat sheets but should be. Non-recurring items are not always recurring. Everyone knows to add back one-time charges. What most people miss is that some so-called one-time items are structural in disguise. Restructuring costs that happen every 18 months, inventory write-downs that correlate with product cycles, legal settlements tied to business segments. If the expense recurs within a 24-month window, treat it as recurring until you have a documented reason not to. Your EBITDA will look better and your assumptions will be more honest. Synergies are liabilities until proven otherwise. Revenue synergies in particular are almost always overestimated. I have never seen a credible case where combined customer pipelines materialized at the projected scale within the first two years. Cost synergies are more reliable but still carry execution risk. The standard rule of thumb is to discount revenue synergies by 50 percent and cost synergies by 25 percent during initial modeling, then rebuild with actuals as they come in. Any model that does not include a synergy realization schedule with downside scenarios is just a fantasy with extra steps.
Debt is not a single number. Gross debt, net debt, adjusted debt, operational debt, financial debt. These are not interchangeable terms and using them interchangeably causes errors that propagate through every downstream calculation. My Finance Cheat Sheet Ultimate forces you to define which measure you are using at the top of every model page. It sounds tedious. It prevents exactly the kind of mistake where you use net debt in one formula and gross debt in another and then wonder why your leverage ratio looks reasonable but is actually wrong.

What This Cheat Sheet Cannot Do
It cannot replace judgment. It cannot fix bad input data. It cannot compensate for a team that has never worked through a full LBO or DCF from scratch. Cheat sheets are lookup tools, not thinking substitutes. There are also contexts where a static reference document actively hurts you. In highly regulated industries like banking or insurance, the relevant metrics change quarterly and depend on jurisdiction-specific capital requirements. A printed or even digital cheat sheet becomes obsolete fast. In those cases, maintaining a live repository with version dates and regulatory citations is more useful than a comprehensive but aging reference. Use the Finance Cheat Sheet Ultimate as a foundation, not as a final answer.
How to Build Your Own Version
If the provided sheet does not match your workflow, build it yourself. Start with the tasks you repeat most often. Write down the exact formula, the edge case you always second-guess, and the common mistake that costs you time. Put each one on its own line with a clear example. Skip the theory. You are not writing a textbook. You are writing a survival document for moments when you need the right number fast. Review it after every major project. Add what you looked up. Remove what you never touched. The sheets that stay relevant are the ones that get rewritten after real use, not the ones that get downloaded and shelved.