What a Finance Checklist Monthly Actually Is
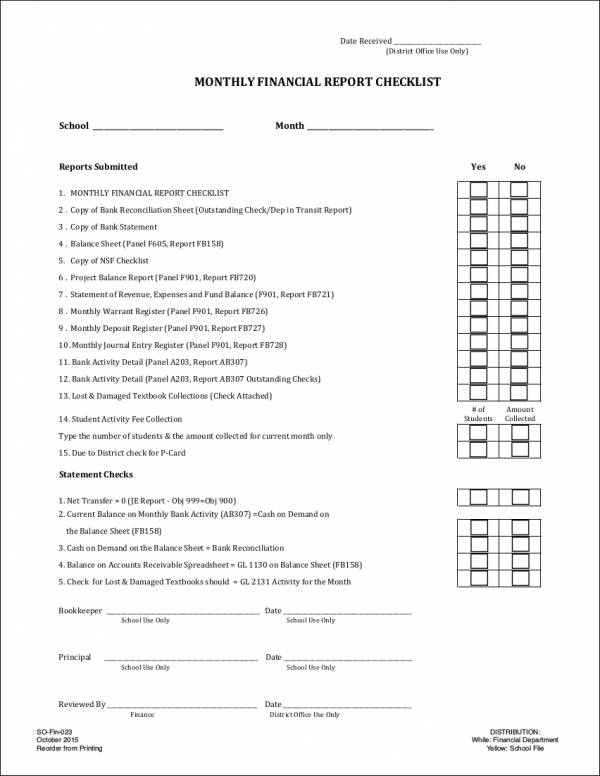
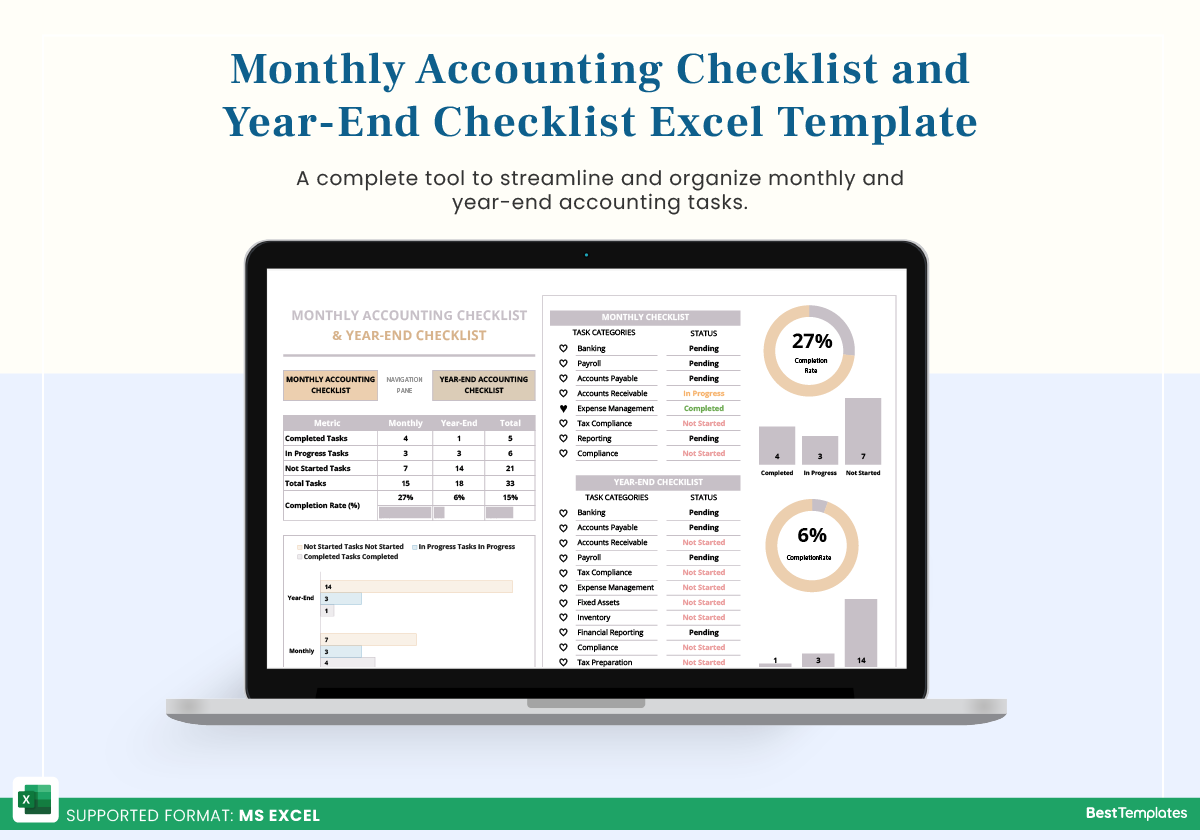
A Finance Checklist Monthly is just a repeated set of money tasks you run through at the same point each month so nothing falls through the cracks. It is not software. It is not complicated. It is a list, usually in a spreadsheet or a note app, that tells you what to check, what to pay, what to reconcile, and what to report. That is basically it. Most people try to build something too elaborate. They want twelve tabs, conditional formatting, and automated email reminders. It takes three hours to build and two months to maintain. A plain checklist with a deadline for each item is usually enough. If you need reminders, set them in your calendar once. You do not need a system that requires its own system.
How to Set One Up Without Overthinking It
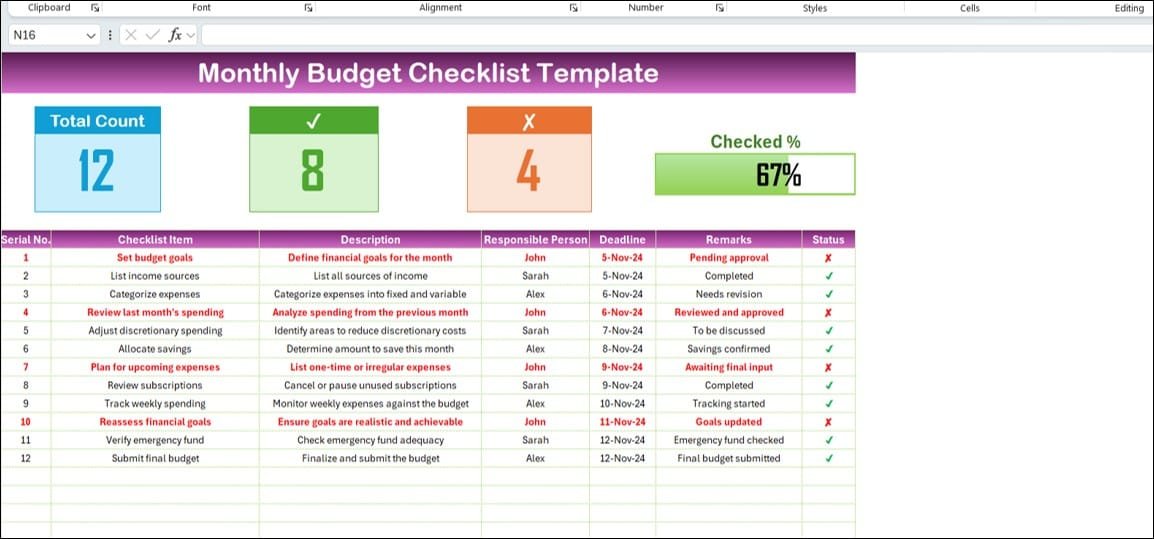
Start with the items that actually matter to you. Do not copy someone else's list. A freelancer's monthly finance routine is completely different from a salaried person's, and both are different from a small business owner handling payroll and inventory. Write down the tasks you know you keep missing. Here is the structure I use. I put it in a single Google Sheet with four columns: Task, Due Day, Status, and Notes. That is all. I go through it on the third business day of every month and mark things complete. When a task is marked done, I move it to the next month's tab so I never have to retype anything. I spend maybe twenty minutes each month maintaining the list.
How to Use a Finance Checklist Monthly Without Losing Your Mind
The hardest part is not creating the list. It is keeping it honest. I learned this the hard way when my automated bill-payment tracker failed me for fourteen straight months. I had connected all my accounts to a personal budgeting dashboard and thought everything was being monitored. It was not. The dashboard showed incoming transfers but never confirmed whether my landlord's payment actually posted to his account or just sat in limbo at the bank. The first I knew about it was a late-fee notice. I spent an hour on hold with three institutions before realizing the automation only tracked one direction of the transaction. My workaround was simple. I stopped relying on the dashboard for outgoing payments entirely. I created a separate verification step where I physically log into each creditor portal on the 5th of the month and confirm the payment posted. It adds fifteen minutes to my routine, but those fifteen minutes have saved me from late fees, awkward conversations with vendors, and several unnecessary phone calls. I added that verification step to my Finance Checklist Monthly as a non-negotiable item.
Get the Full Details
What to Put on the List
Core items most people miss: Account reconciliation - Match your bank statements against your records. Not your budget app. Your actual bank statement. Budget apps have a habit of misclassifying expenses and merging duplicate transactions. I have seen grocery purchases categorized as office supplies and utility payments split across three merchant codes. Reconciling directly against the bank statement catches these errors. Do it before anything else. If your numbers do not match, every report you build on top of them is wrong. Bill verification - Log in and confirm each recurring payment posted. Not "sent." Posted. There is a difference, as I discovered the hard way above.
Savings and investment contribution check - Verify your automatic contributions fired. Check your brokerage statements, not just your bank. Some people set up transfers that go into sub-accounts they do not actively monitor. Money disappears into forgotten 401k catch-up balances or Roth IRA backdoor conversion holds. Debt payoff progress - Note your remaining balance on each debt. Track whether your extra payments are being applied to principal or interest. This matters more than most people realize. Some servicers apply excess payments to future scheduled installments rather than reducing principal immediately. Call them and request principal-only application if you are paying ahead of schedule. Tax estimate tracking - If you are self-employed or have variable income, update your quarterly tax projections. Do not wait until April. I adjust mine every month and keep a running spreadsheet of estimated income, deductions, and tax liability. It prevents the panic that comes from realizing you owe eight thousand dollars in October because you assumed your W-2 withholding would cover everything.
Subscription audit - Review recurring charges. Cancel what you are not using. This sounds obvious but most people do not do it monthly. I keep a simple log of every subscription with its renewal date and cost. When I review it, I ask whether I used the service in the past thirty days. If the answer is no, it goes. I have cut my monthly recurring costs by about forty percent over two years using nothing more than this question.
Common Mistakes People Make
The biggest mistake is treating the checklist as a one-time setup. Lists rot. Items become irrelevant. New accounts open. Old subscriptions expire. Your Finance Checklist Monthly needs to be edited, not just executed. Every third month I go through and delete or add items. If a task has not come up in six months, I move it to a separate "quarterly" section so it does not clutter the monthly view. Another common error is confusing automation with completion. Setting up autopay is not the same as verifying payment. This is the mistake that cost me that late fee. Automation handles convenience. Verification handles accuracy. You need both. A third mistake is building the checklist around tools instead of outcomes. People start with their favorite app and then design their routine to fit the app's features. The app should serve your checklist, not the other way around. If your tool cannot handle a specific task, handle it manually. Do not skip the task because your spreadsheet does not have a column for it.
When This Approach Breaks Down
A monthly checklist does not work well for businesses with high transaction volume. If you process hundreds of invoices or payments per month, a manual checklist becomes a bottleneck. In those cases, you need accounting software with reconciliation workflows and automated matching rules. QuickBooks, Xero, or similar tools will save you time. A spreadsheet will not. It also breaks down if your income is highly irregular. Freelancers with project-based payments often find that a fixed monthly routine does not align with cash flow. In those situations, a rolling 30-day review cycle works better than a calendar-month checklist. You review everything within the most recent thirty days regardless of when the month changes. It sounds minor but it matters when your largest deposits come on unpredictable dates. If you have complex tax situations involving multiple entities, international accounts, or significant investment income, a simple checklist will not capture everything. You will need a CPA or tax professional involved in the process. The checklist can still help you stay organized, but it cannot replace professional guidance.
How Long This Should Take
For a typical individual or couple managing personal finances, a Finance Checklist Monthly should take between thirty and forty-five minutes. Thirty minutes if your accounts are simple and mostly automated. Forty-five minutes if you are reconciling multiple accounts and reviewing investments. If it takes longer than an hour, you probably have too many items on the list or your data is disorganized enough that you are spending more time searching than executing. Trim the list. Organize your documents. If you cannot find a bank statement, it is because you do not have a system for storing them, not because the task itself is difficult. I have seen people turn a two-hour monthly finance review into a twenty-minute task simply by standardizing where they keep their documents and removing tasks that no longer applied to their situation. The list was the problem, not the work.

What to Do If You Miss a Month
You will miss a month. Something happens. Do not abandon the system. Do not restart from scratch. Go back to the last complete cycle and work forward. Do two months of work at once if you have to. A checklist is a tool for consistency, not a test of perfection. Missing one review cycle is normal. Missing three in a row is when problems accumulate. Catch it early.