Working With Simple Financial Examples
Most people trying to learn basic finance concepts get overwhelmed by textbooks full of jargon before they understand anything useful. I spent years watching this happen, and I figured out that stripping everything down to its simplest form actually works better for real-world understanding. Here is how I approach it. The core idea behind Finance Examples Simple is taking complex financial mechanics and demonstrating them using plain numbers anyone can follow. No need for financial calculators or spreadsheets initially. Just pen, paper, and numbers that make sense in context.
Understanding the Basics Through Finance Examples Simple
Take compound interest as an example. The formula is A = P(1 + r)^t, but nobody needs that upfront. Start with this instead. Say you invest $1,000 at a 5% annual return. Year one gives you $50, so you have $1,050. Year two, you earn 5% on $1,050, which is $52.50. You now have $1,102.50. See the difference already? Each year you are earning interest on interest. That is the mechanism, not a memorized equation. I once worked with a client who wanted to compare two loan offers. One had a lower nominal rate but higher fees, the other was reversed. Instead of getting tangled in APR calculations immediately, I laid out the actual dollar amounts they would pay month by month for the full term. The lower-rate loan ended up costing $2,400 more over five years because of origination fees and prepayment penalties. Numbers on a page like that made the decision obvious without requiring any advanced knowledge.
This approach works because it forces you to confront actual cash flows rather than abstract rates. That is where most people make mistakes. They fall in love with a low percentage number without tracking what it actually costs over time.
Get the Full Details
Common Pitfalls to Watch For
Simple examples can mislead if you do not understand their limits. A compound interest example showing $10,000 growing at 7% looks attractive until you factor in inflation eating away 3% annually, leaving a real return closer to 4%. The nominal example is still correct, but it paints an incomplete picture. Another issue is the assumption of constant returns. Real investments fluctuate. A simplified example might show steady growth, but the actual experience involves years of gains followed by periods of decline. If you only study the smooth version, you will not be prepared for volatility when it actually hits your portfolio. I encountered a situation where a friend asked me to evaluate a retirement projection based on Finance Examples Simple methodology. The model showed sufficient growth assuming a flat 6% annual return. I recalculated using historical data instead, running a Monte Carlo simulation with actual market drawdowns. The result showed a 30% chance of running out of money by age 85, which completely changed our strategy. We shifted the allocation more conservatively and added a bond ladder component.
The simple example was not wrong. It was just insufficient for the decision being made. Knowing when simplicity crosses into oversimplification is the skill that separates useful from dangerous.
Building Your Own Simple Models
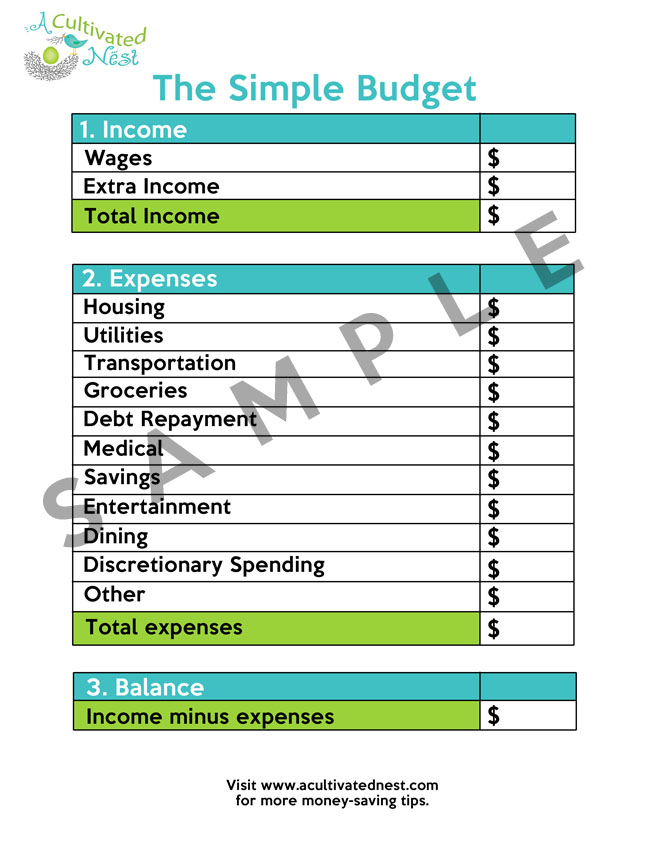
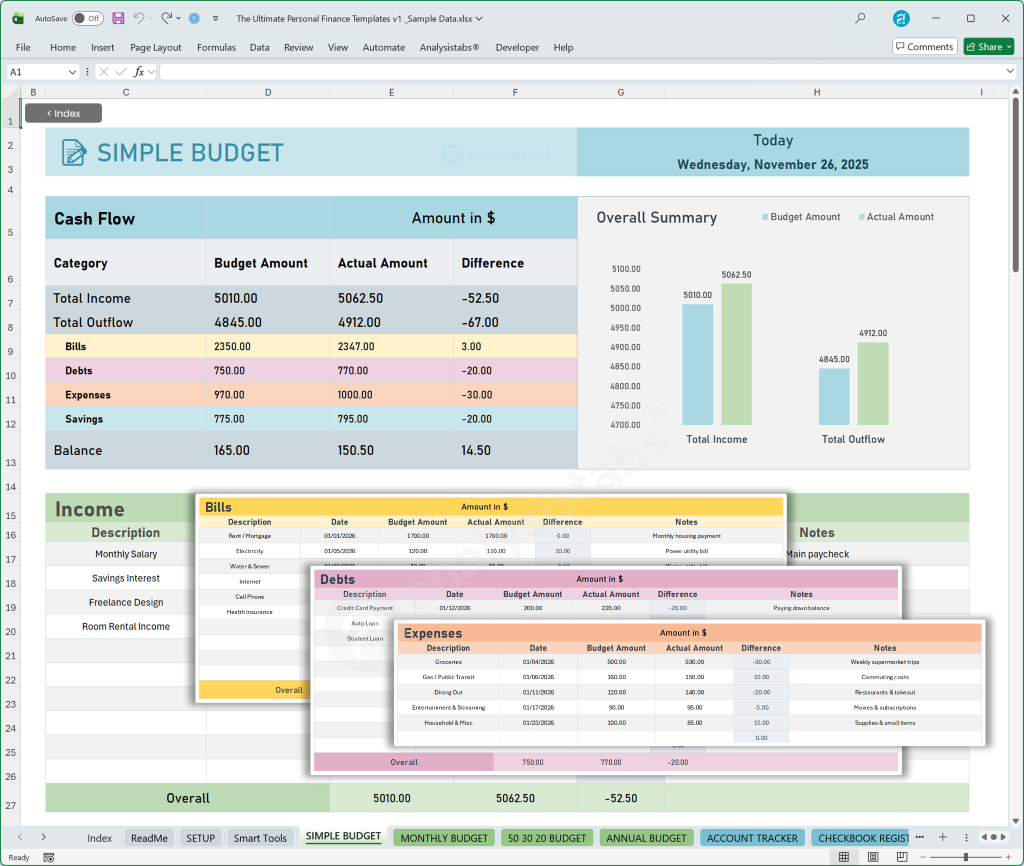
You do not need expensive software to work through basic financial scenarios yourself. A simple spreadsheet or even a notebook works fine for the foundational cases. Start with one variable at a time. Change only the interest rate, or only the time period, or only the initial amount. Observing how each change moves the outcome builds intuition faster than trying to adjust everything simultaneously. For budgeting, try the 50-30-20 rule as a starting framework. Fifty percent of take-home pay goes to necessities. Thirty percent to discretionary spending. Twenty percent to savings and debt repayment. It is rough, intentionally imprecise, and that is the point. Getting the broad strokes right matters more than perfect accuracy in the beginning.

I built a simple debt payoff model for myself a few years back that tracked multiple loans side by side. I used the avalanche method, targeting the highest interest rate first while making minimum payments on the rest. The example showed I would be debt-free in three years. Reality took four because of unexpected medical expenses that interrupted the payment schedule. The model still served its purpose of showing me the path forward, but I learned to build in a buffer from the start.
When Simple Examples Break Down Completely
There are scenarios where simplified models fail outright. Tax-advantaged accounts like 401(k)s and IRAs involve rules that change frequently and interact in ways that simple examples cannot capture. The same is true for estate planning, where state laws and individual circumstances create complications that no generic example covers adequately. Insurance products, particularly annuities, are another area where oversimplification can cost significant money. Commission structures and surrender charges vary widely between providers. A simple comparison of payout rates ignores the fees that erode returns over time. If you are dealing with any of these situations, consult a licensed professional rather than relying on simplified models. The cost of advice is almost always less than the cost of a mistake made from incomplete information.
The usefulness of Finance Examples Simple as a learning tool does not depend on complexity. It depends on using the right level of detail for whatever decision you are trying to make. Start simple. Recognize the boundaries. Move to more sophisticated analysis only when the situation demands it.