The Problem With Making Finance Look Pretty
A lot of people stumble into financial journaling because they saw something on Pinterest or Instagram that looked satisfying. Thin fountain pen lines, gold ink, little washi tape borders, everything color-coded. Then they try it once, realize they spent forty-five minutes making a monthly budget page look like a piece of art, and never do it again. That's the first lesson: aesthetics are the easy part. The hard part is actually doing the work consistently over years. I've helped maybe a dozen people set up proper finance journals over the last several years, mostly through informal advice online. The ones who keep it going for more than six months share one trait: they made the system boring enough to sustain. The gold-ink pages always fall apart by March. The ones using a simple black pen and a cheap composition notebook from Walmart are still writing in June of year two.
What Finance Journal Aesthetic For Adults Actually Means
The term itself has gotten bloated. People use it to describe anything from bullet journal spreads to Notion dashboards to printed worksheets. At its core, a finance journal for adults is just a system for recording money movement in a way that reduces decision fatigue. The aesthetic component is secondary but not irrelevant — if the notebook looks pleasant to open, you're marginally more likely to actually open it. The adult version differs from the student or beginner version in a few practical ways. Adult finance journals need to handle irregular income, multiple accounts, recurring bills that change amounts, and the occasional large one-time expense that throws off a monthly budget. A template designed for a salaried employee with predictable deposits will frustrate a freelancer within three months.
Setting Up a System That Actually Sticks
Start with something physical unless you have a strong reason not to. A dedicated notebook costs about twelve dollars. Downloaded templates require software decisions, app subscriptions, and will inevitably get replaced by whatever new tool you decide to try next month. Paper doesn't update its interface without your permission. Here's the layout I recommend for most people. On the left page, draw a simple table: date, description, amount, category. That's it. No color-coding by category. No decorative headers. On the right page, a running monthly balance column. You write your spending on the left, update the balance on the right. At the end of the month, total your expenses and compare to your income. If you're below, you saved. If you're above, you know immediately. I almost always suggest skipping the category sub-sections that bullet journal guides love to push. Breaking every expense into "food" or "transportation" sounds useful until you realize you've spent twenty minutes on a Tuesday night deciding whether a grocery run counts as "groceries" or "eating out" because you had a small coffee with it. The tracking becomes about maintaining the system rather than tracking the money. One page for entries, one page for balance. That's the entire spread.
Get the Full Details
There's a specific edge case that trips people up, and I want to address it directly. I had someone once who used a checkbook-style system with account numbers pre-printed on the first page of their notebook. They wrote down their full routing and account numbers for three different bank accounts in pen. When I pointed out that this is essentially a target for identity theft if the notebook were lost or stolen, they were genuinely surprised. They'd been doing it for two years without thinking about it. The fix was simple: use the last four digits only on the reference page, and keep the actual statement documents in a separate file. Write the full numbers on a piece of paper you store somewhere secure, then reference the shortened version in the journal. I've seen people do this unknowingly quite often.
Where This Approach Fails
Handwritten finance journals don't integrate with bank APIs. If you want automatic transaction import, this isn't the system for you. You'll be entering data manually, which means you're more likely to skip days when life gets busy. I've watched people maintain a paper journal faithfully for eight weeks, then miss three days during a renovation project, then feel guilty and abandon it entirely. The gap between December 14th and December 17th became a permanent blank space, and the whole thing felt ruined. The workaround I suggest is to keep a backup digital record that's intentionally low-effort. A shared Google Sheet where you paste bank statements once a week and copy any missing transactions is enough. It's not elegant. It's not aesthetic. But it catches the gaps before they compound into a month of lost data. Another failure mode is over-engineering the aesthetic. I watched one person spend approximately three hundred dollars on notebooks, pens, stamps, stencils, and specialty tape. Their journal looked like a museum exhibit. They wrote exactly one month of entries. The aesthetic investment created a pressure threshold — the notebook was too nice to use carelessly, so they barely used it at all. A fourteen-dollar spiral notebook from Office Depot has no such psychological barrier.
Finance Journal Aesthetic For Adults: The Visual Part
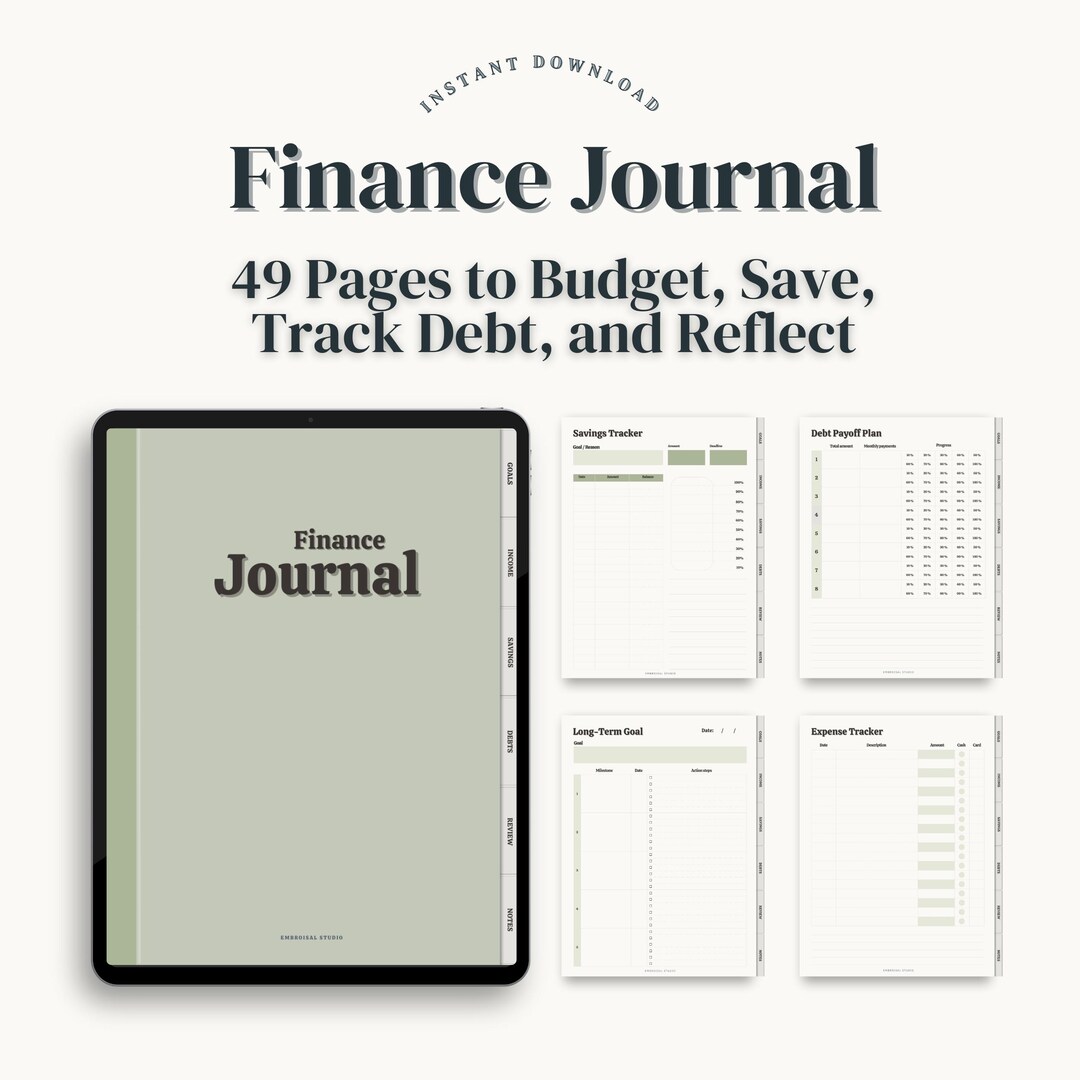
If you want the aesthetic element without the maintenance burden, there's a middle ground. Use a quality pen — a Uni-ball Signo or a Pentel Energel writes smoothly and doesn't bleed through standard paper. Pick a notebook with thick enough pages that gel ink doesn't feather. A simple grid or dot grid layout gives you structure without the rigidity of ruled lines. Everything else is optional. You can add color with a single colored pen for income entries. Blue for spending, green for income. That's one decision per transaction instead of seven. Most elaborate color systems require remembering which shade corresponds to which category, which introduces more friction than it removes. There's also a printable route if you prefer not to hand-draw tables every month. Sites like Etsy and individual creators sell finance journal PDFs in the twenty to thirty dollar range. They handle the formatting for you. The downside is that you're committing to a specific layout that may not fit your actual financial situation, and you'll print pages you might not use. I usually recommend downloading one template and filling it out for a month before buying a full pack. See if the layout actually works for your data pattern first.
The Numbers That Matter
Most people don't need more than three data points in their finance journal: date, amount, and whether it was income or expense. Everything else — categories, subcategories, notes, goals, savings targets — is layering on top of that core system. Adding layers increases accuracy effort without necessarily increasing financial awareness. I've tracked my own finances in a plain notebook for about six years now. The entries look like a spreadsheet written by hand. The system catches every dollar I spend and takes about twelve minutes per week to maintain. That's the realistic time commitment. Twelve minutes a week. If it's taking you more than twenty minutes, you've added complexity that's eating your time without adding proportional value. Strip something out. Remove a category. Stop measuring your net worth weekly and switch to quarterly. The journal should serve the tracking, not the other way around. The aesthetic matters in the sense that a pleasant-looking notebook makes the weekly maintenance feel less like a chore. But "pleasant" doesn't require decoration. It requires legibility, consistency, and a format you actually want to look at. A clean handwritten table with clear dates and aligned columns is more aesthetically functional than any stamped floral border you could apply. The design is in the data clarity, not the surface treatment.
If you want to start, buy a notebook, get a pen that writes smoothly, and write down your January first balance. From there, just add entries. The rest organizes itself after about six weeks of practice.