Why Most People Abandon Their Finance Journals By March
I started tracking every dollar in 2009, not because I read some productivity guru, but because I was bleeding money without knowing where it went. I'd glance at my account balance three weeks after payday and have no idea how we got from $4,200 to $612. That panic is a pretty universal experience, honestly. The bookkeeping systems you find online range from elaborate spreadsheets to notebook setups that look like something a forensic accountant would use on a embezzlement case. Neither extreme works for daily use. The real friction isn't the math. It's the gap between the moment you spend money and the moment you actually record it. Most methods fail because they require you to sit down and consciously engage with your finances at a time of day when you are already mentally drained. I tried morning logging and evening logging. Morning means you're rushing. Evening means you've already forgotten the $7 coffee or the Uber fare from last Tuesday.
Building a Finance Journal Daily Log For Adults That Actually Sticks
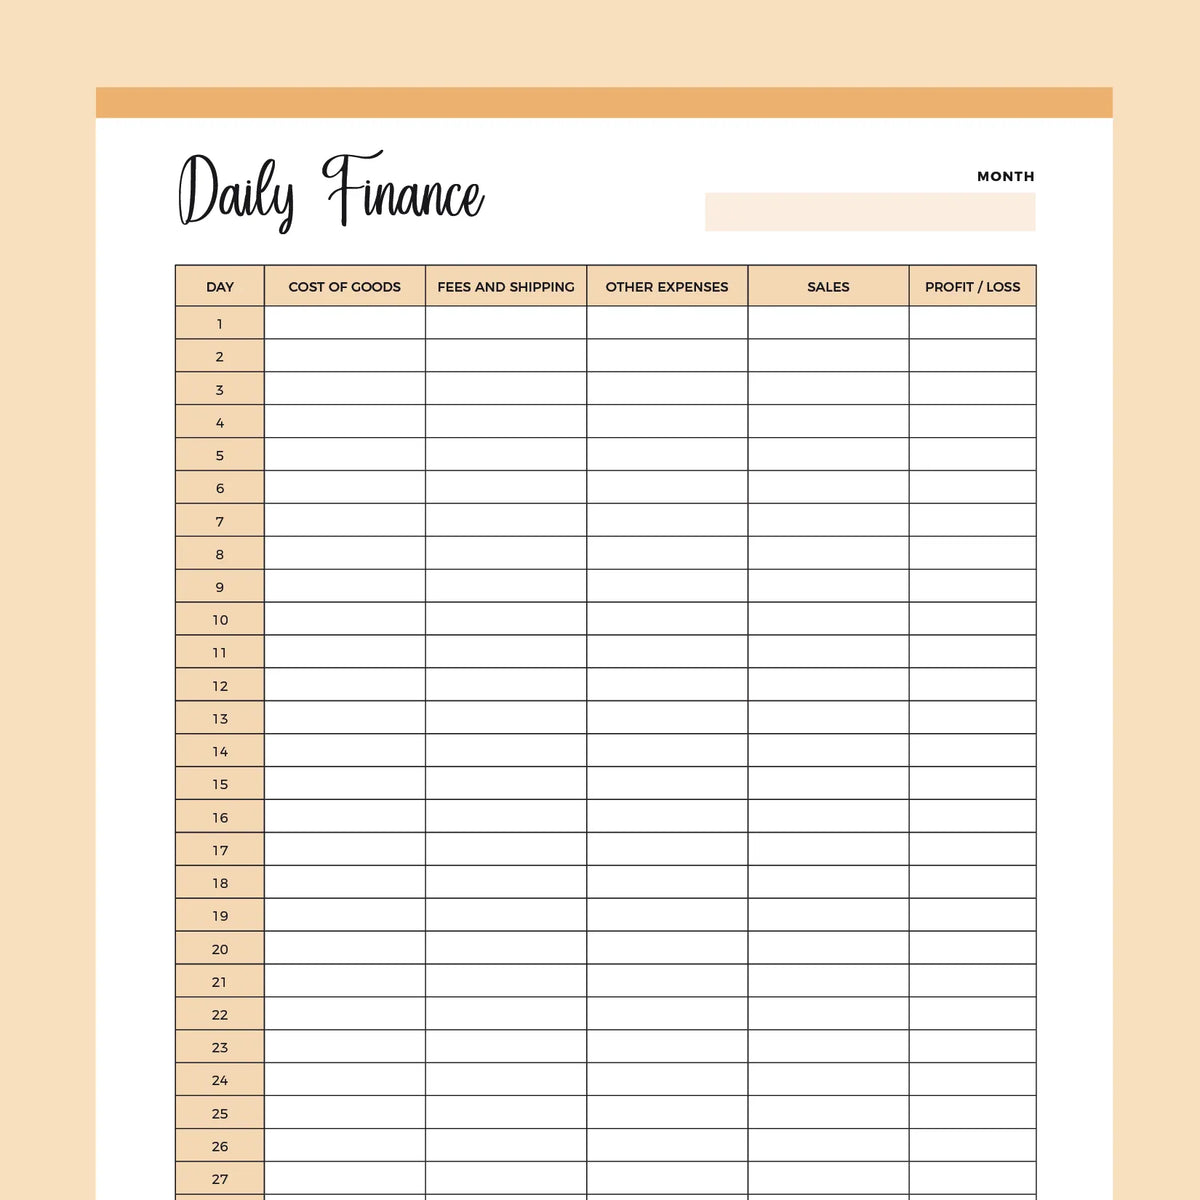
Here's what I settled on after about two years of throwing away perfectly good notebooks and failing spreadsheets. You need a daily log format that captures transactions within thirty seconds of happening and still gives you enough structure to actually learn something from them. A single-column running list doesn't work. You lose context fast. A full double-entry system on a daily basis is overkill and you'll quit before the habit forms. The middle ground is a modified cash-basis daily log with three required fields per transaction: timestamp, amount, and category. Everything else is optional. Keep it to that. The categories matter more than most people realize. If you use something generic like "Food," you're going to conflate groceries and takeout, which are two very different problems financially. Separate them. Use at least: groceries, dining out, transportation, subscriptions, entertainment, healthcare, shopping, and transfers. Yes, transfers go in there. Missing a transfer between checking and savings creates phantom money in your head that disappears when you actually do reconciliation. There's one edge case I ran into that threw me for a loop. I was using a notes app on my phone with bullet points, and for about six months I didn't notice that my subscription category was eating into what I thought was my discretionary spending. The problem was that several of my subscriptions auto-charged on different days throughout the month. My bullet-point log showed individual charges of $14.99, $9.99, $12.99, and I was treating them as miscellaneous expenses because I hadn't labeled them at the time of entry. I caught it only because I finally sat down and cross-referenced my bank statement line by line instead of trusting my memory of the categories I was supposed to have used. From then on I added a fourth field: reference. Just a five-word note telling me what the charge actually was. Took maybe eight extra seconds per transaction.
What to Log and How to Structure the Day
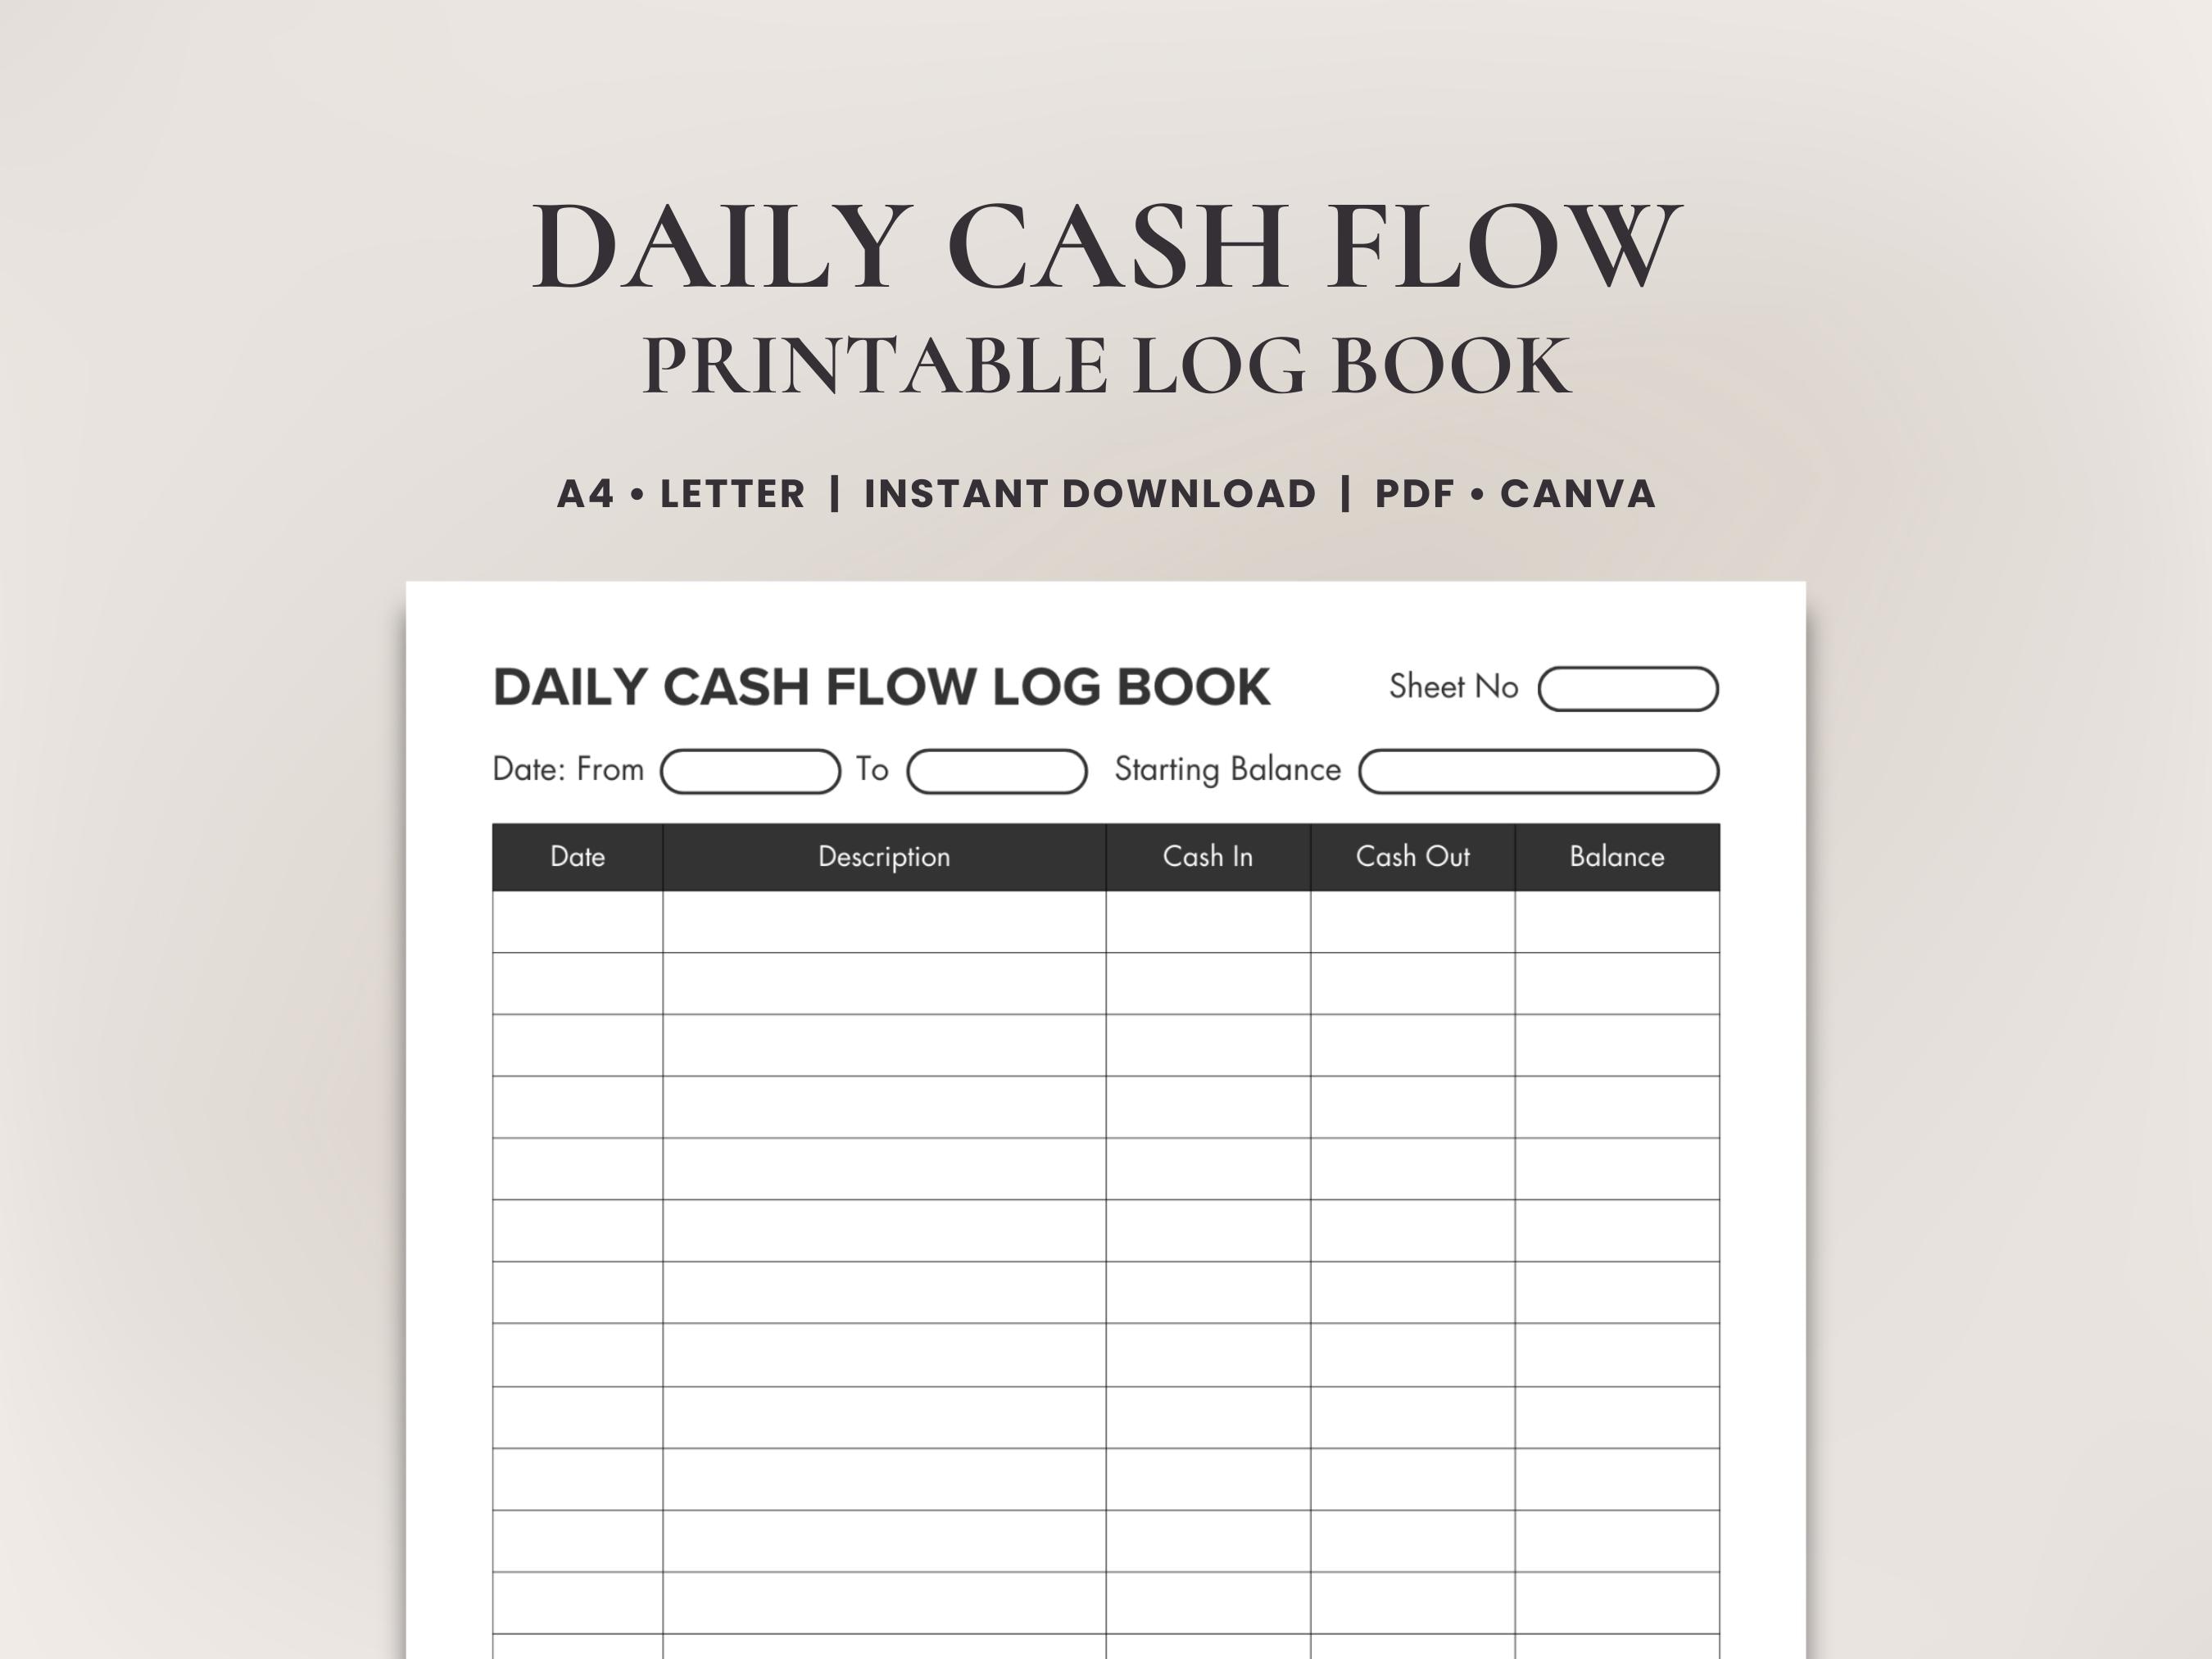
Each entry should start with the date as a header. List transactions in chronological order. Put income at the top, separated with a thin line or a different color if you're using a physical notebook. The running total column is where most people get confused. There are two approaches. The first is to update your cash balance after every single transaction. This gives you a real-time picture but requires constant arithmetic and it is easy to make small errors that compound. The second approach, and the one I recommend, is to record a morning balance once per day and only log transactions without a running total. At the end of the week, you do a quick reconciliation against your bank balance and adjust the morning balance if needed. This is faster daily and actually more accurate long-term because you're not doing mental math in your head while driving. Weekly reconciliation is non-negotiable. Without it, your journal drifts. I learned this the hard way when I spent an entire Friday convinced I had $1,800 available and my card got declined for $47 because my actual balance was $12. I had been logging transactions inconsistently for eleven days. A fifteen-minute weekly review prevents this. Match each journal entry against your bank statement. If there's a mismatch, investigate it the same day. Don't push it to next week. The longer you wait, the harder it becomes to remember what a particular charge was for. One thing beginners consistently overlook is the treatment of pending transactions. Banks show them as available, but they are not yet confirmed. If you log a pending transaction on the day it appears, you're recording money you may or may not actually spend. I used to do this and my numbers were always slightly off. The fix is simple. Do not log pending transactions. Wait for them to post. If you want to track anticipated obligations, keep a separate section at the bottom of your daily log called "Scheduled but not posted." This keeps your actual cash balance accurate while still giving you visibility into upcoming commitments.
Get the Full Details

The Mechanics of Category Budgets Inside a Daily Log
A daily log on its own is just a diary of spending. It becomes useful when you tie it to category-based budgets. The method is straightforward. At the start of the month, assign a dollar limit to each category based on your actual income and fixed obligations. Then each time you log a transaction, you note the category and the system tells you how much remains. The trick is doing this without turning your finance journal into a second job. Most people try to calculate remaining budgets in their head. This introduces error and resentment. Instead, use a simple table on the first page of your notebook or the top of your spreadsheet that shows each category with three columns: monthly limit, spent so far, and remaining. Update the spent column daily. The remaining column is just limit minus spent. That's it. Here is a counter-intuitive point that surprised me. When I first started doing this, I thought stricter category budgets meant better control. They did not. What actually worked was setting my food category significantly higher than I needed and taking the surplus seriously. The psychology of having a cushion changed how I approached spending. Instead of panicking every time I hit a category limit, I learned to plan around it. I stopped making impulsive purchases out of anxiety and started making intentional ones. Your daily log becomes a tool for decision-making rather than a ledger of failure.
Common Failure Points and What to Do About Them
The biggest reason people abandon their journals is inconsistency, not complexity. They miss three days, feel guilty, and then stop entirely. I have watched this happen to myself multiple times. The workaround is simple and not obvious to most people. Allow yourself to log nothing on weekends. Seriously. Most discretionary spending happens Friday night through Sunday, and if your system demands logging every coffee and bar tab for seven days straight, you will burn out. Treat Saturday and Sunday as buffer days. On Monday morning, pull your bank statement or credit card app and reconcile the weekend in bulk. You can enter twelve to fifteen transactions in under three minutes this way because you are no longer trying to remember each one individually. You are looking at raw data and assigning categories as you go. Another failure mode is treating your finance journal as a prediction tool instead of a record tool. I saw people online insist that daily logging would help them predict future spending patterns. This is backwards. A finance journal daily log for adults is about establishing an accurate baseline first. You cannot predict anything meaningfully until you have at least two months of consistent data showing what you actually spend, not what you think you spend. The first month of logging will feel inaccurate because you will catch transactions you always missed. This is normal. The second month is when the numbers start stabilizing. Give it that long before you try to forecast or budget aggressively. There is also a technical edge case worth mentioning. If you use a spreadsheet-based daily log and import bank CSV files, you will eventually run into duplicate entries from your bank reconciling transactions that you already logged manually. I built a simple check into my spreadsheet that flagged any entry with the same date and amount as an existing entry, and asked me to confirm before adding it. This saved me roughly ten minutes per week in cleanup work. If you are doing everything by hand in a notebook, the equivalent is a simple star or checkmark next to transactions you have already reconciled against your statement.
When a Finance Journal Daily Log Is Not the Right Tool
I should be honest about where this approach breaks down. If you have multiple income streams with variable pay, dozens of shared accounts, or you are managing debt across several cards with different due dates and interest rates, a simple daily log becomes insufficient. You will spend more time organizing the log than you save in awareness. In those cases, a dedicated budgeting application or a quarterly spreadsheet analysis will give you better returns on your time investment. The daily log works best for single-income households or couples sharing one primary checking account with a manageable number of expense categories. It also assumes you have the cognitive bandwidth to engage with your finances daily. If you are going through a major life event like a divorce, job loss, or hospitalization, do not force this habit. Come back to it when things stabilize. The core principle is that your finance journal daily log for adults is a tool, not a moral judgment. It exists to give you information you did not have before. Anything beyond that is noise. Track consistently for two months. Reconcile weekly. Adjust categories as needed. Then step back and let the data speak for itself.