Why Most Finance Journals Die Within Three Weeks
I started tracking my finances daily back in 2018 because I kept losing money on things I couldn't account for. Small purchases, recurring subscriptions I forgot about, impulse buys that added up to nearly eight hundred dollars a month. The standard advice is to download a spreadsheet template or use an app and just log everything. That worked for about eleven days. Then I stopped because the friction of opening an app, finding the right category, and typing in each transaction became too much during a busy workday. What actually stuck wasn't the tool. It was the reflection habit built around it. A daily log in this context isn't a transaction ledger. It's a structured written record where you capture not only what you spent but why you made each financial decision that day. The reflection component is what separates it from a bare-bones expense tracker. You're looking at behavioral patterns, not just numbers. When I say Finance Journal Daily Log For Deep Reflection, I mean a daily written practice that combines transaction recording with honest analysis of your spending triggers, emotional state, and whether each expense aligned with your actual priorities. The core structure breaks down into four sections. First, record every transaction from the day with amount, category, and merchant. Second, rate your emotional state that day on a one to ten scale. Third, flag any purchase that felt impulsive or misaligned with your goals. Fourth, write a short summary answering one question: did my money go where I said it would? This takes roughly twelve minutes per day if you're efficient. Most people who abandon this system fail because they try to do it in twenty-minute sessions with elaborate commentary. That's unsustainable.
The Practical Setup
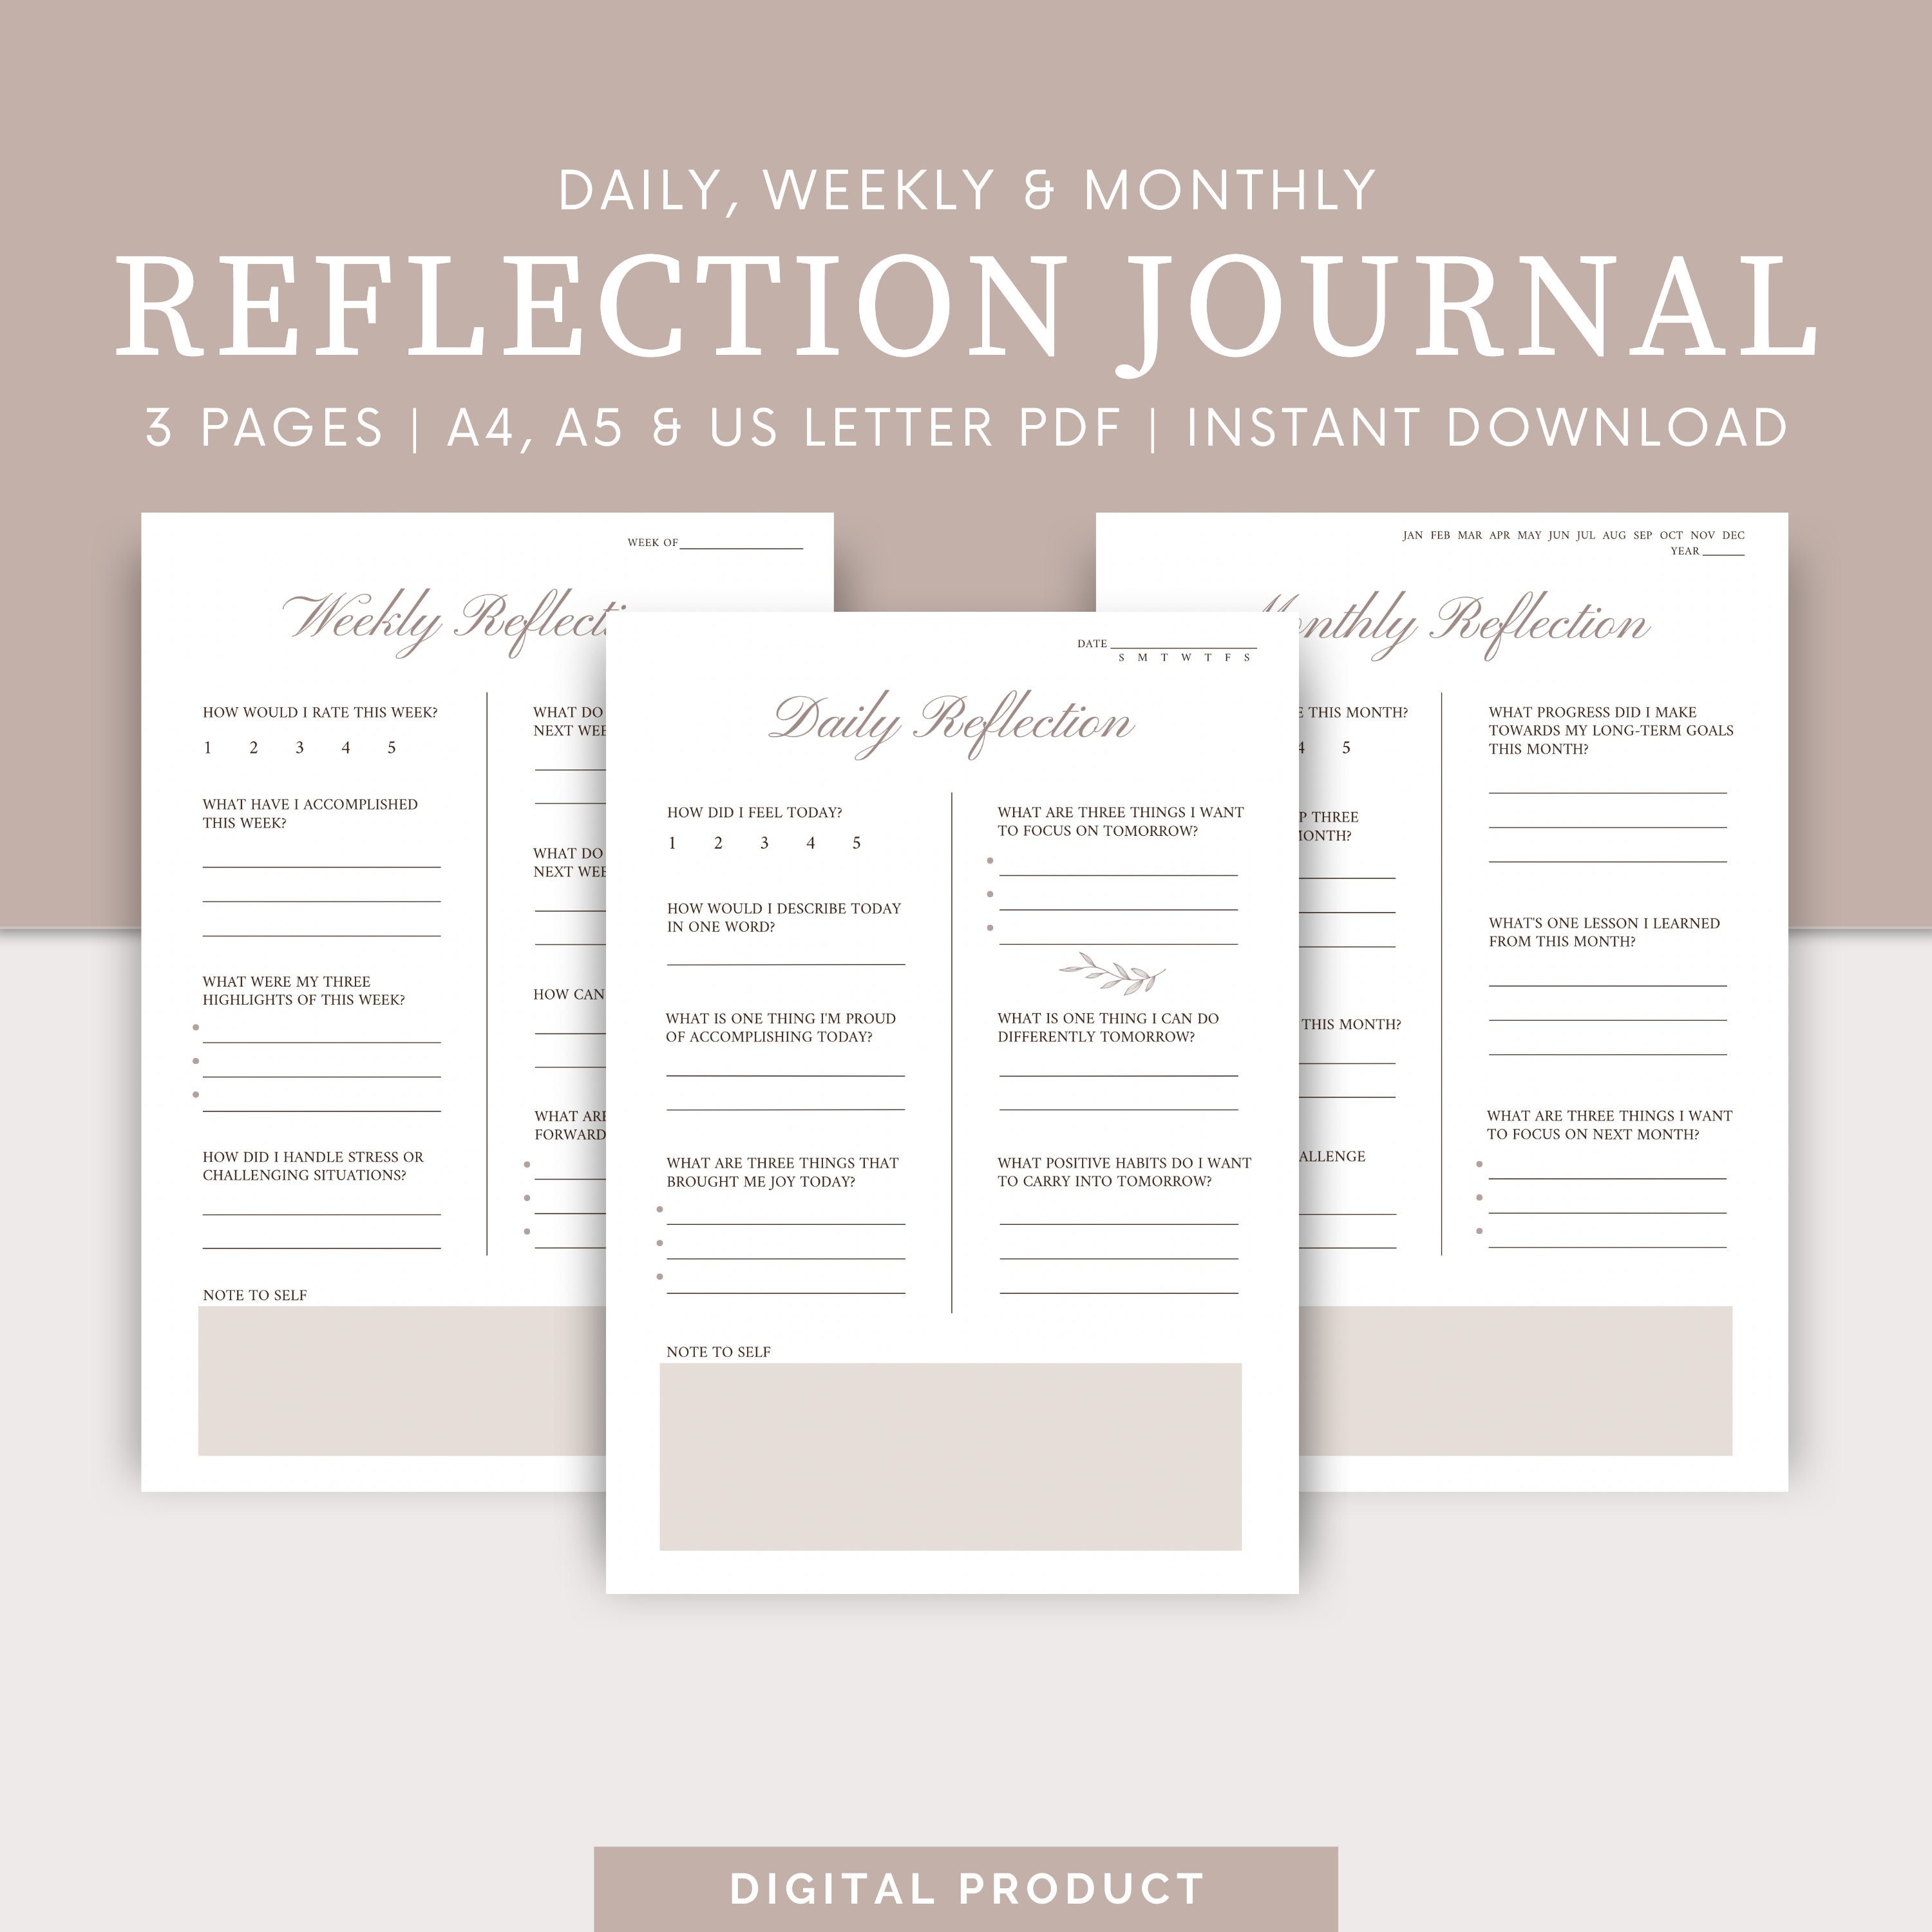
I use a simple notebook for the reflection part and a separate budgeting app for transaction import. The app handles the raw data. The notebook handles the thinking. Some people try to do it all in one place and it becomes a mess. The split workflow matters more than the medium. A digital tool with a clean interface works just as well as paper if it reduces friction. I've tested Notion templates, Google Sheets, dedicated journaling apps, and a plain Moleskine. The notebook won for me because there was zero setup time, no password to remember, and no sync anxiety. If you want to build this from scratch, start with a daily date header. Under that, list your transactions in a single column format: date, amount, category, note. Below the transaction list, add a reflection block with three prompts. How many impulse purchases did I make today? What emotion was driving those decisions? What's one thing I'll adjust tomorrow? Keep it to three prompts. Adding more makes people skip days.
Common Pitfalls That Make This System Fail
The biggest mistake I see people make is treating the journal as a punishment tool. They write entries with guilt and self-criticism after every unnecessary purchase. That creates a negative association with the practice and they stop doing it. The second mistake is perfectionism. If you miss two days, you feel like you've ruined the streak and you abandon it entirely. The third mistake is over-categorizing. Spending twenty minutes deciding whether a coffee was a "morning routine expense" or a "social anxiety purchase" defeats the purpose. Categorize broadly and move on. There's also a technical issue worth mentioning. Most expense tracking apps pull data from linked bank accounts but they often misclassify merchants or lump transfers into spending. I spent a full afternoon reclassifying transactions in YNAB only to realize my grocery spend was double counting because of a pending transaction that cleared two days later. The workaround is to run your journal entries against your bank statement at the end of each week, not each day. Daily matching is overkill. Weekly reconciliation catches the errors without eating your evening. Another edge case I encountered personally involved subscription tracking. My finance journal showed I was spending about forty dollars monthly on subscriptions but my bank statement told a different story. The gap was due to a free trial that converted to paid without any email notification. I set up a separate spreadsheet with subscription names, renewal dates, and monthly costs, and cross-referenced it against the bank statement every Sunday. This caught three dormant subscriptions and one duplicate service within the first month. The daily log alone couldn't solve this because subscriptions don't show behavioral patterns. They need a separate tracking mechanism.
Get the Full Details
What the Data Actually Reveals After Eight Weeks
Most people quit before they see the signal in the noise. The first three weeks are just data collection. You're building the habit and the entries look shallow. By week five, patterns start emerging. You'll notice that your spending spikes on certain days of the week, or after specific events like social gatherings or stressful workdays. In my own journal, I discovered that Thursday and Friday evenings accounted for nearly thirty percent of my monthly discretionary spend. The purchases were mostly food delivery and streaming rentals. Knowing that allowed me to pre-plan those evenings instead of reacting to fatigue and hunger. The deeper insight comes from combining the emotional rating with the transaction data. When I logged my mood alongside spending, a clear correlation appeared. On days I rated myself below four out of ten, my average transaction value jumped by sixty percent compared to high-mood days. This isn't surprising if you think about it, but seeing the number confirmed was different from knowing it intellectually. The journal made it impossible to ignore. The workaround I used was setting a twenty-four hour cooling-off rule for any non-essential purchase over thirty dollars on low-mood days. That single rule cut my impulsive spending by roughly forty percent within the next month.
When This Approach Stops Working
Be honest about when a daily journal isn't the right tool. If you have a complex income situation with multiple revenue streams, freelance payments, and investment returns, the daily log becomes tedious because you're tracking inflows and outflows across accounts simultaneously. A weekly review format works better there. If you live paycheck to paycheck and every dollar needs allocation, the journal's reflection component adds friction you can't afford. A zero-based budgeting system with a strict envelope method will serve you better. And if you've already automated your savings, bill payments, and investment contributions, the marginal value of daily transaction logging drops significantly. You might be better off doing biweekly reviews instead. There's also the data quality problem. Bank feeds aren't always accurate. Merchant categories can be wrong. Recurring payments sometimes get logged twice or missed entirely. I've seen people spend more time correcting their journal than they would have spent just using a traditional budgeting app. The solution is to accept that your journal will never be perfectly accurate. Aim for eighty-five percent data completeness and spend the remaining time on reflection instead of corrections. Perfection in tracking is the enemy of consistency in behavior change.
A Realistic Daily Workflow
Here's what my actual process looks like on a normal weekday. I open the journal app at 9:47 PM, right after dinner. I import my transactions from the bank feed, which takes about ninety seconds. I scan the list and flag anything unusual. Then I answer the three reflection prompts. The entire session takes between eight and fourteen minutes. On weekends or days with more transactions, it can stretch to twenty minutes but that's the maximum. I don't do it on days I'm traveling because the data is messy and fragmented. I catch up on Sunday evening with a weekly summary instead. The weekly summary is where the real value sits. Each Sunday, I review the seven days of logs and look for trends. I calculate my total spending by category, compare it to my planned budget, and note any emotional patterns. This thirty-minute session replaces what would otherwise be an hour of spreadsheet analysis. Over a year, that's roughly fifteen hours saved compared to doing everything manually. I should mention one more thing that most guides don't cover. The reflection entries themselves become a resource. Six months into keeping my journal, I had written about two hundred and forty daily entries. When I was preparing for a major purchase, I reread the entries from the previous three months to understand my spending trajectory. That context was impossible to get from any app dashboard. Apps show you totals. They don't show you the story behind the numbers. The story is what changes behavior.


