Why Most Kid Finance Journals Fail Before They Start
I spent three years trying to build a functional money journal for my nephew before I got it right. Most DIY finance journals for kids fall apart because adults overcomplicate the tracking mechanism. The kid gets lost in too many columns, or the system requires so much setup that they abandon it after a week. The simplest approach is usually the only one that survives past the second month. You need to understand what actually happens when a child tries to track money. They receive cash or digital allowances, they make a choice to spend or save, and then they record it. That is the complete loop. Everything else is decoration. A proper system captures those three actions without requiring a ledger that looks like an accounting degree from accounting software.
Essential Components Of Finance Journal Diy For Kids
The core structure needs four sections. Income, expenses, savings goals, and reflection. Income tracks every dollar received. Expenses tracks every dollar leaving their possession. Savings goals are where the actual behavioral change happens. The reflection section is what most people skip, but it is the part that turns a spreadsheet into something educational. I used three-ring binders with printed pages for a long time. Then I switched to printable templates because kids lose physical books, and printer paper costs less than binder replacements. The printable approach also lets you adjust the difficulty level without buying new materials. I print simpler layouts for younger kids and add more detailed columns as they get older. This single switch extended the usable lifespan of the system from about four months to nearly two years. Warning: Do not include compound interest calculations in the early versions. It confuses the tracking and creates false expectations about how money works at the family level. Compound interest belongs in a separate section once they understand basic accumulation.
Building The Actual Template
Start with a monthly income log. Create columns for date, source (allowance, gifts, chores, babysitting), amount, and running total. Keep the running total simple subtraction so they practice math rather than depend on calculators. I learned this the hard way when my nephew filled out three months of entries using a calculator and could not explain why his numbers were wrong when the math did not add up. The expense section works the same way but in reverse. Date, category, amount, and remaining balance. Categories matter here. I started with generic labels like "Fun" and "Food." That was useless. Specific categories like "Toys," "Snacks," "Games," and "Transportation" force the kid to think about where money actually goes. Vague categories produce vague awareness. For savings goals, use a progress tracker. A target amount, current saved amount, and a visual bar or checkmarks. I initially used percentage-based tracking because it felt more mathematical. Kids under twelve do not intuitively understand what 37 percent means in practical terms. Switched to dollar amounts and checkmarks. Completed in two weeks instead of two months before they lost interest.
Get the Full Details

The Reflection Section Nobody Talks About
Every Friday or at the end of each month, the kid writes or draws one sentence about what surprised them about their spending. This seems soft and unnecessary until you see data showing that kids who skip this section stop tracking after six weeks. Those who keep it tend to continue for months. The reflection creates ownership of the system. It is not just recording numbers anymore. It is recording their own decisions and reactions. I had a problem where my nephew wrote the exact same sentence every week for a month. Something about how pizza was expensive. I changed the format from open reflection to multiple choice questions: "Was there something you wanted but did not buy?" "Did you skip something to save money?" "What surprised you about your spending?" The structured prompts forced new observations and the journal became useful again within a week.
Where People Go Wrong
The biggest mistake is making the journal too adult-facing. You will see templates online that look like actual accounting records with debit and credit columns. Do not use those. A child does not need to understand double-entry bookkeeping to learn financial responsibility. They need to see money come in, money go out, and money remaining. Another common failure point: Parents audit the journal too frequently. Weekly checks feel like homework to a kid and kill motivation fast. Monthly reviews are fine. Quarterly conversations work better. The journal belongs to the child. Parent involvement should be minimal and scheduled, not constant scrutiny. The digital version has its own trap. Apps that gamify tracking sound great until the kid learns to game the app itself rather than learn the habit. Screens add distractions that a paper journal never introduces. If you go digital, pick something with zero social features and zero reward systems. Just tracking. Nothing else.
A Practical Template Structure
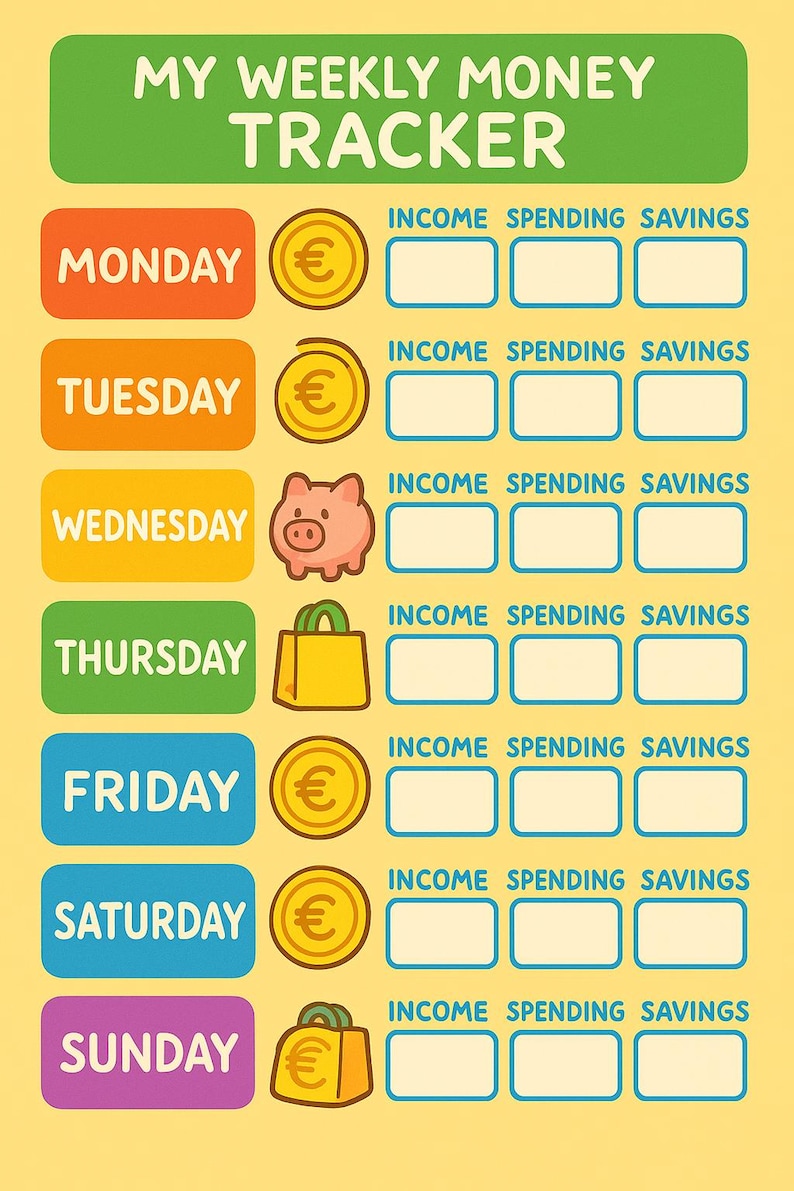
Here is a working layout I have used successfully with ages eight through fourteen: Page one: Monthly income summary. Spaces for up to five income sources per week. Total column. No category breakdown needed yet. Page two through four: Weekly expense logs with date, specific category, amount, and balance remaining. Keep it to one page per week to prevent overwhelm.

Page five: Savings goal tracker with visual progress representation. Dollar amounts only. No percentages until age twelve. Page six: Monthly reflection with guided questions. Not blank pages. Guided prompts produce better results consistently. This structure fits on standard letter paper and takes about twenty minutes to set up the first month. Subsequent months require only the printout and a pen. The recurring time investment is approximately five minutes per week for the kid to fill in entries, plus ten minutes for the monthly reflection.
What Happens When It Actually Works
Kids who stick with this system for six months or longer start making different purchasing decisions without being told to. They begin asking about prices before buying. They voluntary check their remaining balance. These behaviors emerge naturally from the tracking process itself, not from parental instruction. The journal does the teaching once the routine becomes automatic, which usually takes between eight and twelve weeks depending on the child's age and prior exposure to money concepts. The system breaks down if you involve too many people in managing it. Grandparents giving cash without recording it, parents adding extra allowances without updating the income log, sporadic tracking schedules. Consistency matters more than complexity. A simple system followed every week beats an elaborate one followed irregularly. That is the lesson I wish I had learned before going through three failed versions over eighteen months.