The Structure That Actually Works
A finance journal for goal setting is basically a living ledger where you record your actual money movements against the targets you wrote down. Not everything fits neatly into a spreadsheet category. Some months you'll pay off a credit card and realize your "emergency fund" calculation was wrong because you forgot about the $34 annual subscription fees that quietly bled out. This is why the format matters more than the tool you pick. Most people set a goal like "save $10,000 in twelve months" and then track it with zero accountability until the month is over. That's the opposite of a journal. A real finance journal captures what happened, not what you hoped would happen, and it does it on a timeline you can reference when the numbers get uncomfortable.
Why Monthly Review Beats Weekly Review
Weekly tracking sounds disciplined until you realize your income fluctuates enough that a single bad week skews everything. Monthly reviews smooth out irregular paychecks, one-off expenses, and the occasional gift money from your sister that you honestly weren't expecting to count as income. Here's a stripped-down example of what a monthly entry looks like: January Example: Income: $5,200 | Expenses: $3,800 | Savings contribution: $1,200 | Remaining to goal: $8,800 | Notes: car repair hit unexpected ($420) but I pulled it from the fun money category instead of touching savings
That one entry tells you more than a hundred rows in a bank app ever will. It also forces a conversation with yourself that you don't want to have. Which is the whole point.
Get the Full Details

The Mechanics Behind Finance Journal Examples For Goal Setting
The method has three moving parts: baseline, projection, and correction. You start by establishing where you actually stand today, not where you'd like to stand. Then you build a projection based on what's realistic given your current cash flow. And finally, you correct when the projection diverges from reality, which happens in about 80 percent of cases within the first ninety days. Most people skip the correction step. They keep following the original plan even though the plan assumed a $120 monthly grocery bill when they're actually spending $210. That's how goals quietly fail without anyone noticing until three months have passed. I ran into a specific edge case last year where I was tracking a debt payoff goal with a monthly surplus of exactly $680 after minimum payments. The math said I'd be free in fourteen months. But I hadn't accounted for the fact that my health insurance premium increased mid-year by $94 a month. That smaller line item wasn't dramatic enough to catch my attention, so the projected payoff date drifted to twenty-two months. What fixed it wasn't a new budget — it was cutting the autopay subscription service I had set up two years earlier for a streaming platform I barely used anymore, saving $15 per month, and redirecting the rest of the gap by adjusting the discretionary spending ceiling rather than touching the emergency fund.
The workaround I ended up using was a simple column addition: every time a new expense materialized, I added it to a "goal interference" column in my journal. After three months, I could see the pattern — it was always the same three categories eating into the surplus. That pattern let me renegotiate the budget instead of just watching the goal recede month by month.
A Counter-Intuitive Truth About Tracking Frequency
Tracking daily doesn't give you better visibility than tracking monthly. It gives you anxiety. Daily entries create noise that drowns out signal. The human brain over-indexes on recent data, which means a $78 lunch one day gets filed as a crisis when it's just a Tuesday. Monthly data averages out that noise. I've seen people spend twenty minutes a day logging transactions and still miss the structural problem, while others spend forty-five minutes a month reviewing their entries and catching the real issue. The other thing nobody tells you: the goal you pick shapes the journal, not the other way around. A debt payoff goal produces a very different document than a home down payment goal. With debt, you want to see payoff curves and interest savings. With savings, you want to see compounding growth and contribution consistency. Mixing the two in the same journal creates confusion because the math pulls in opposite directions at different times of the month.
What a Full Monthly Entry Should Look Like
Here's a more complete example spanning two months, showing how the journal evolves as you refine the numbers: February Entry: Income: $4,950 | Fixed expenses: $2,100 | Variable expenses: $1,150 | Irregular expenses: $310 | Savings: $890 | Goal status: $1,110 short of target | Notes: medical bill delayed by two weeks, insurance hasn't billed yet, adjusted March projection accordingly
March Entry: Income: $5,100 | Fixed expenses: $2,100 | Variable expenses: $1,080 | Irregular expenses: $0 | Savings: $1,250 | Goal status: on track for April catch-up | Notes: switched to generic phone plan, saved $63 monthly, redirected to savings immediately The entries get tighter as you go. That's the signal that the journal is working. When you reach a month where your notes just say "clean" and you've already projected the next month's adjustments before you finish writing, you've crossed into habit territory. That's usually around month four or five.
The Spreadsheet Alternative
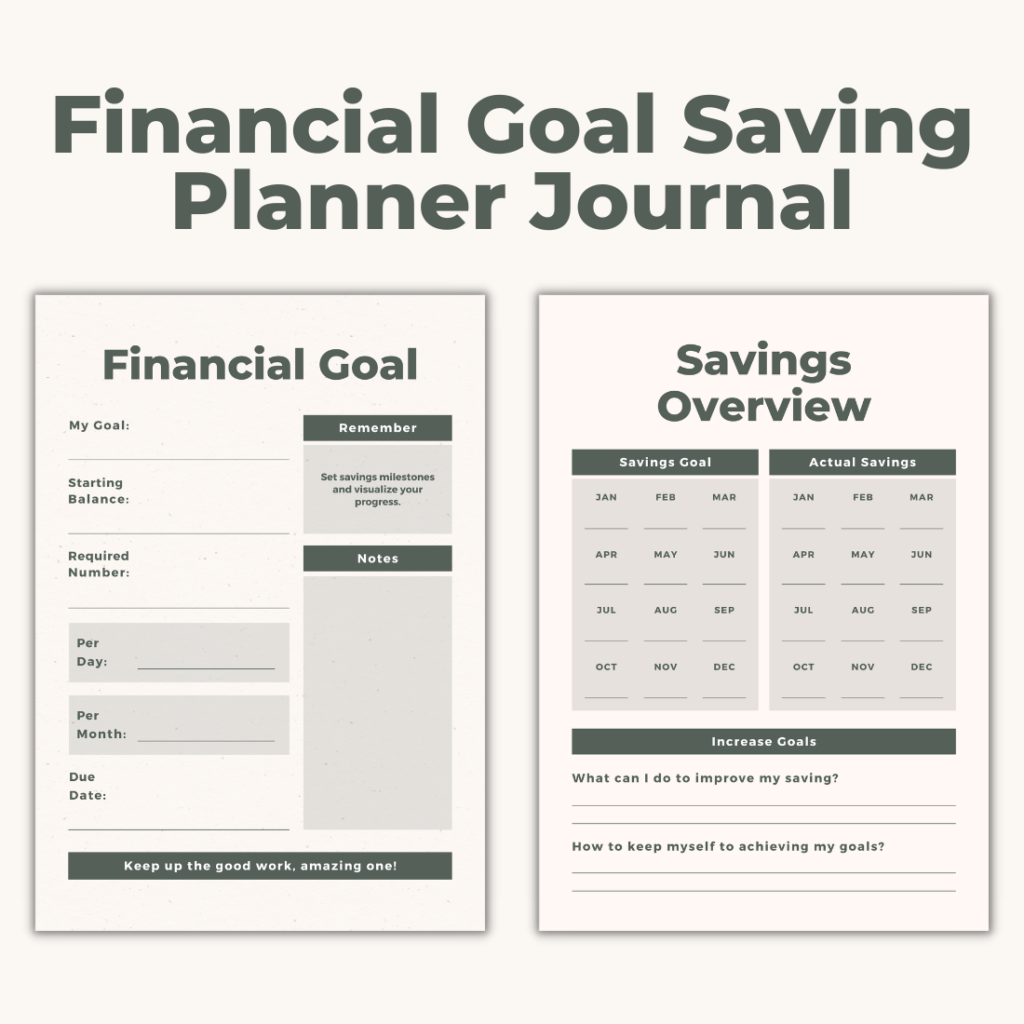
If you want something downloadable, the simplest template uses five columns: Month, Projected savings, Actual savings, Variance, and Adjustment notes. That's it. Fourteen rows for fourteen months. You fill it out once a month and the variance column tells you everything you need to know without requiring any analysis software. Here's a basic structure you can copy into any sheet: Month | Projected | Actual | Variance | Notes

Month 1 | [target] | [actual] | [diff] | [what happened] Month 2 | [revised target] | [actual] | [diff] | [correction applied] Each subsequent month uses the previous month's variance to adjust the projection. This creates a rolling forecast rather than a static goal that never changes, which is what most people end up with and then abandon because the number feels impossible.
Where This Approach Breaks Down
Finance journals for goal setting don't work if your income is irregular to the point of unpredictability. Freelance work, commission-based pay, seasonal employment — if your monthly income swings by more than thirty percent, the journal becomes a guessing game because the baseline shifts every cycle. In those cases, a rolling twelve-month average of income and a quarterly goal review structure works better than monthly tracking. The method also fails when you're managing multiple overlapping financial goals simultaneously. Debt payoff, retirement contributions, a house down payment, and a child's education fund all compete for the same surplus. A single journal collapses under that complexity within a month. You either need separate journals per goal or a significantly more structured system that allocates surplus before recording anything. There's also the documentation problem. If you don't keep receipts or bank statements organized, the journal becomes an exercise in estimation, and estimation is where accuracy goes to die. I once spent three weeks reconstructing a quarter's expenses from memory because I hadn't backed up my transaction history, and the resulting numbers were off by roughly eighteen percent. That error would have invalidated the entire goal projection for that period.
So the honest trade-off is this: the method rewards consistency and penalizes neglect. It's not a tool you can ignore for two months and expect to pick back up without consequences. The journal compounds the same way your money does, which means gaps compound too. That's not a flaw in the system. It's a feature designed to make you pay attention.


