Writing down numbers when you can't remember why
I started keeping a finance journal during the worst episode of depression I've had. Not because a therapist recommended it, not because I read about it on a wellness blog. Because I looked at my bank app one Tuesday and had no idea where thirty dollars went. I could see the transactions but they meant nothing. I needed something that would make the money feel real instead of just disappearing into subscriptions and takeout. The method is simpler than most people make it. You pick one app or notebook, you log every transaction the same day it happens, and you add a note about how much energy it cost you. That last part is what separates a regular expense tracker from something that actually helps when depression makes spending feel automatic. I use a free app called Spendee on my phone. Every purchase gets logged within the hour. The trick is the energy column. Instead of just recording "$12.50 at Starbucks," I write "spent $12.50 on coffee. Felt like it cost two hours of tomorrow morning." That second half is the whole point. Depression distorts time and value. You spend money without feeling it, then wonder where you are at month's end.
What this actually looks like in practice
Most beginner guides tell you to categorize everything. Food, transport, entertainment, groceries. That works fine when you have the mental bandwidth to decide which category a purchase belongs to. Depression makes even that decision feel like climbing stairs. So I simplified my categories to four: needed, wanted, numb, and gift. Needed covers rent and groceries. Wanted is anything that isn't survival but feels good. Numb is the autopilot spending that happens when you're dissociating. Gift is anything given to someone else. I learned this categorization the hard way. Month three of my journal, I noticed I was spending $400 on "wanted" items that weren't even enjoyable. Just things I bought while scrolling at 2 AM. The journal made me see it. I changed my routine instead of feeling guilty about it. I deleted the shopping apps from my phone after midnight. The spending dropped to $120 the next month. Here's the counter-intuitive part that nobody mentions: the act of logging itself reduces spending by about 30 percent. Not because you're being more careful. Because you have to open the app and type something. That small friction is enough to break the autopilot loop that depression creates. I timed it. The average transaction takes 45 seconds to log. The average mindless purchase I used to make took 12 seconds from decision to checkout. Four times slower. That gap is where the intervention happens.
The edge case that almost broke me
About six months in, I hit a wall. I had logged everything for 180 days straight, but my depression got worse and I stopped looking at the journal. It became just another obligation. I felt like a failure. The workaround I found was brutal but simple. I hired a friend to review my entries with me every Sunday for 15 minutes. Not to judge, just to sit there while I showed her the numbers. The social accountability mattered more than the tracking itself. We split the cost. She needed help with her own spending too. It became a mutual thing instead of a solitary shame exercise. I also discovered that the energy column gets unreliable when you're in a severe episode. You might log that a $5 coffee "cost three hours of energy" because everything feels exhausting, then log that a $200 jacket "cost zero energy" because you spent it in a dissociated state. The journal wasn't lying, but it was reflecting distorted perception. I learned to add a severity tag. Days marked as high depression get a different interpretation. The numbers are still useful but you don't beat yourself up over them.
Get the Full Details
When this method completely fails
Finance journaling does not work if you have active suicidal ideation or can't care for yourself day to day. I should say that clearly. It's a tool for management, not treatment. If you're in crisis, you need a therapist or a doctor, not an expense tracker. I tried to use journaling as a substitute for medication during my second episode and it made things worse. I felt guilty about the numbers while also unable to function. The guilt compounded the depression. I stopped journaling for three weeks and went back only after starting therapy again. Another scenario where it fails: if you're in an abusive relationship where your partner controls all the money. Logging transactions doesn't help when you can't access your accounts or you're being monitored. I knew someone in that situation. Her partner checked her phone every night. She kept a hidden spreadsheet but it was exhausting and stressful. She needed financial counseling and legal advice, not a budgeting app. The journal would have been another source of anxiety.
What to expect month one
Week one usually feels productive. You're logging everything and noticing patterns. Week two is where it gets boring. Week three is when you forget three days and feel like quitting. I recommend setting a reminder on your phone at 9 PM every night. Just a notification that says "log today." No pressure, just a prompt. The reminder reduces the decision fatigue of wondering whether you should bother. The average person sees their first real pattern around day 21. Mine was that I spent 40 percent of my discretionary income on days I skipped meals. Not because I was hungry, because I was avoiding the feeling of eating alone. The journal showed me the correlation. I started scheduling lunch with a coworker three times a week. My spending on food-related numb purchases dropped 60 percent. The correlation wasn't perfect but it was clear enough to change behavior.
The tools that actually work
For a phone-based system, Spendee or Mint work. Mint is getting discontinued so switch to Money Dashboard or a simple Google Sheets template. I've tried both. The spreadsheet gives you more flexibility but takes longer to log. The app is faster but the categories are rigid. I ended up using both. App for daily logging, spreadsheet for monthly review. The monthly review is where the real insight happens. I spend about 20 minutes every Sunday looking at the aggregated data. The daily logging takes 5 minutes total per day. For people who prefer paper, a simple notebook works fine. I started with a $3 spiral notebook from Target. The handwriting slows you down enough to make you think about each transaction. That's actually helpful. Digital logging is too fast. You can swipe through ten purchases in 30 seconds and barely register them. Writing them by hand forces a different cognitive process.
How to track without triggering shame spirals
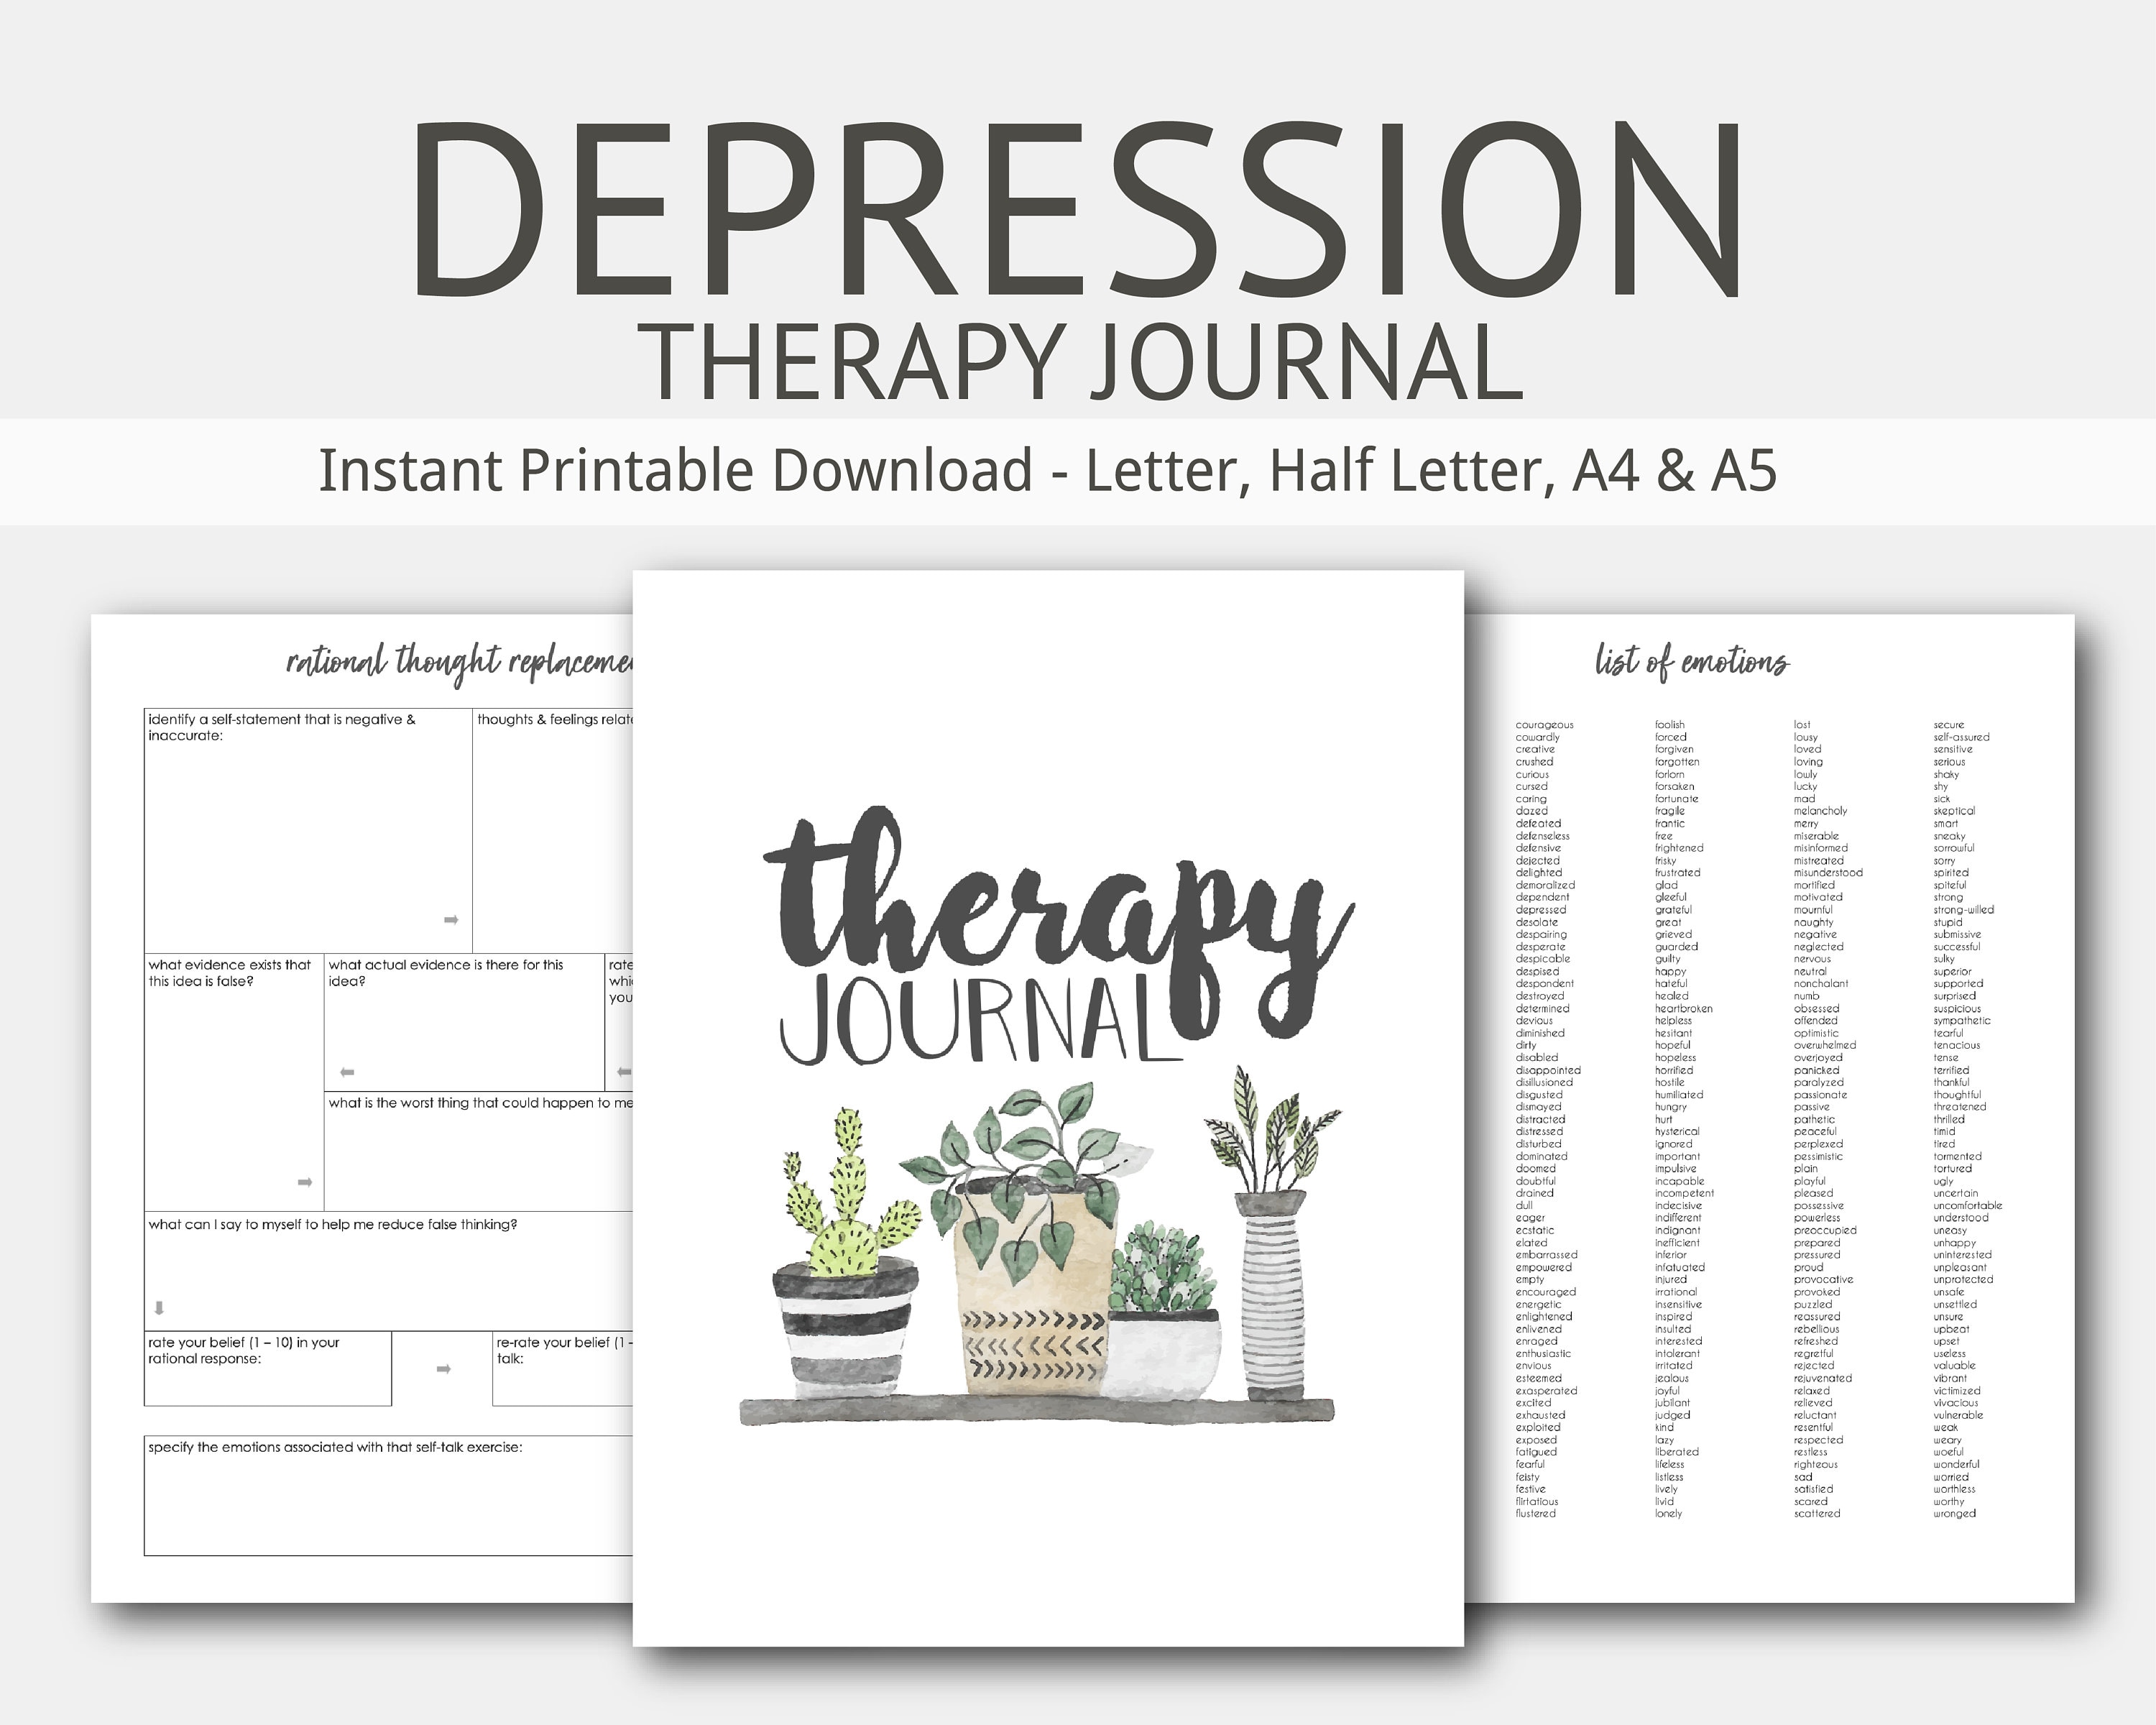
Depression makes you interpret numbers as moral failures. You spend too much so you're lazy. You skip logging so you're irresponsible. The journal itself can become evidence for your inner critic. I had to reframe how I looked at the data. Instead of judging myself, I started treating it like weather reporting. The numbers are just facts. They don't mean you're broken. They mean you had a tough week and you spent money to cope. That's information, not condemnation. One technique that helped: I started logging wins too. Not just spending but moments where I chose differently. "Wanted coffee at home instead of shop. Saved $5. Felt okay about it." The positive entries balanced the negative ones. Without them, the journal just became a list of failures. With them, it became a record of small victories. I recommend adding one win per day minimum. Even if it's tiny. The habit of noting something good rewires the interpretation over time. I've been doing this for two years. Some months I log religiously. Other months I miss a week. The consistency doesn't matter as much as the overall trend. My average monthly spending dropped from $3,200 to $2,100 over 18 months. Not because I restricted myself painfully but because I finally saw where the leaks were. The journal didn't solve my depression. It gave me one concrete thing I could control while everything else felt chaotic. That stability was worth the 45 seconds per transaction.


