Writing is a business if you treat it like one
I spent years trying to figure out my income tax situation as a freelance writer. Receipts everywhere, random checks, expenses I couldn't remember what was for. Eventually I just built something myself to track it all, and that became the Finance Journal For Writers. It started as a messy Google Sheet with terrible color-coding, then turned into something I use every week, then something other writers asked about, then a proper downloadable template. Here is how it actually works and what the setup looks like.
Setting up the Finance Journal For Writers
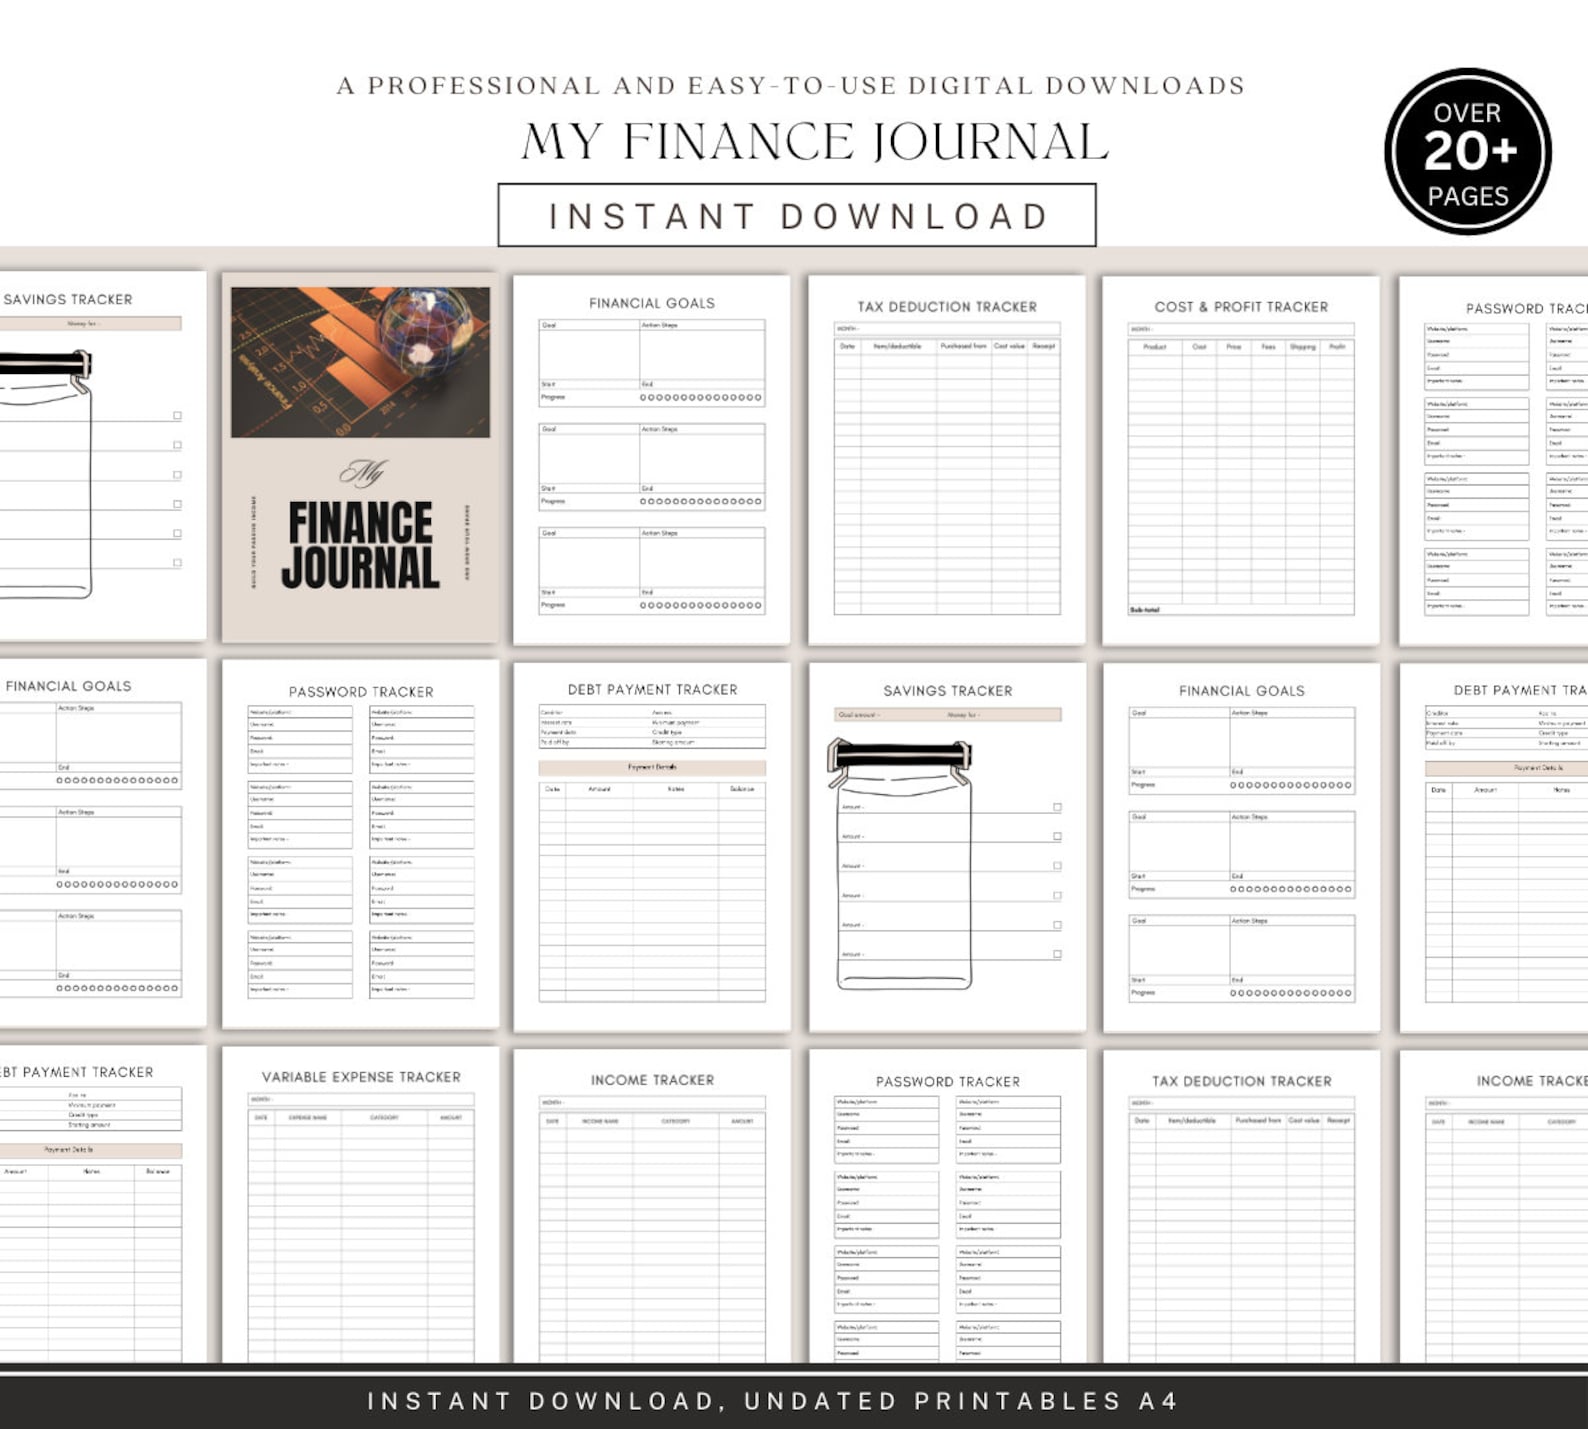
The core is straightforward. You have three tabs. The first tab is your income log. The second is your expense tracker. The third is your monthly summary with basic profitability metrics. That is it. Most templates out there are way more complicated than they need to be. Open the spreadsheet and fill in column A as the date, column B as the client or project name, column C as the invoice number if you have one, column D as the gross amount, column E as the payment method, column F as the date received, and column G as the net amount after any platform fees. Platform fees matter a lot. Upwork takes fifteen percent. Fiverr takes twenty. If you do not subtract those before calling it income, your numbers are wrong and your taxes will be wrong. On the expense tab, I track date, vendor, category, amount paid, payment method, and whether it is deductible or not. The categories I use are software subscriptions, hosting, webinars or courses, office supplies, shipping costs, professional dues, mileage, and home office portion. Some of these sound silly until you realize your entire work happens from your kitchen table.
The monthly summary pulls data from the other two tabs automatically. It shows your total gross income, total expenses, taxable income, and effective tax rate based on whatever bracket you enter. The effective tax rate is the number most writers never think about but should.
Get the Full Details
A real problem I ran into
Two years ago I missed a whole quarter of expense logging because I was juggling three long-term clients and feeling guilty about spending time on paperwork instead of writing. When I finally opened my journal, the rows were inconsistent. Some vendors had receipts attached and some did not. The sums were off by about four hundred dollars. I could not tell which line items were duplicated. The workaround was brutal but effective. I printed the entire spreadsheet and went through it row by row with a pen. I crossed out anything without a corresponding receipt, re-entered the clean data into a fresh tab, and then wrote a note in the comments section explaining what happened. That note saved me when the IRS asked for clarification on a deduction three years later. They did not care about the drama. They cared that the numbers matched my receipts. Writing that explanation in the sheet itself was faster than pulling out old emails.
What most writers get wrong
The biggest mistake I see is mixing personal and business expenses in the same column. I know. You are buying groceries and printer paper on the same card. But your accountant cannot untangle that later without charging you for it. Open a separate business checking account. Even if it has zero balance for three months, just keep it open. The moment you start commingling funds, everything gets messier and the IRS view of your business shifts from legitimate to something else. Another common error is forgetting to log cash payments. I once wrote off two hundred dollars in cash tip money to a bar owner who hosted a networking event. No receipt, no record. When I tried to claim it later, the deduction was denied because I had nothing to show. Cash payments still count. Just write them down immediately and take a photo of the venue receipt if there is one.
Advanced tracking habits
Once you are comfortable with the basics, there are a few things that make the system actually useful instead of just another chore. The first is project-level tracking. Add a column labeled Project Code and give each assignment a short identifier. It sounds like overkill until you are sitting in front of a tax preparer and trying to figure out which client paid you the most per hour. With a project code, you can filter and pivot instantly. The second is quarterly estimated tax calculations. The finance journal should include a section where you estimate what you owe each quarter based on your YTD income and deductions. Most writers wing this and then panic in April. I calculate mine every January, April, July, and October. The numbers change as the year goes on, but having the estimate in the sheet means I am never surprised. The third habit is saving every receipt in a single folder with a consistent naming convention. I use the format YYYY-MM-DD Vendor Category Amount.pdf. It takes five seconds per file and saves hours during tax season. Your journal entry can link directly to that file if you store everything in cloud storage.

Where this system breaks down
Not everything about this approach works smoothly. If you work with multiple currencies, the spreadsheet gets annoying because exchange rates change daily and you have to update them manually. I used to handle this by logging the rate at the top of each month and applying it to all transactions in that period. It is not precise. It is close enough for most people. If you need exact precision, you need a different tool. Another limitation is that this system is designed for freelancers and independent contractors, not W-2 employees with side gigs. If you have a day job and write on the side, the deductions look very different. You cannot write off home office space the same way. You have to be more careful about the fifty percent rule for mixed-use expenses. The spreadsheet can still work for you, but you need to adjust the category definitions and probably run your numbers past a CPA who understands both employment income and self-employment income. Also, this is not a replacement for accounting software if you scale up. Once you cross about one hundred fifty thousand in annual revenue, manual tracking starts to create more work than it prevents. At that point, tools like QuickBooks or FreshBooks become worth the monthly cost because they automate category matching and generate reports you would otherwise build by hand.
Downloading and using the template
You can find the Finance Journal For Writers template at writersfinancejournal.com/download. It comes in both Google Sheets and Excel format. There are three versions: the basic tracker, the advanced version with project codes and quarterly tax estimates, and the combined version for writers who also do editing or coaching work. Import it, rename the sample rows to your actual data, and spend thirty minutes setting up the formulas if you are using the advanced version. The formulas are locked so you cannot accidentally break them. Everything updates automatically once you start entering data. You will probably forget to log a transaction once a week. That is normal. Do not let it make you quit. The system works if you use it at least once a month, even if you miss weeks in between. One thing I want to make clear: this template does not file your taxes. It does not talk to the IRS. It is a tracking tool. If you need tax filing help, hire someone. The spreadsheet will save you money on that help because your records will be organized when you sit down with them instead of having a shoebox full of papers.
I have used this exact workflow for four years now. I still make mistakes. I still forget receipts. I still occasionally categorize something wrong and spend twenty minutes fixing it later. But the alternative used to be me digging through bank statements every January and realizing I had no idea where the year went. This journal gives me a picture in real time instead of a blurry snapshot once a year. If you are serious about writing as a career, or even as a side hustle that you want to treat seriously, building a habit around this kind of financial tracking is not optional. It is the difference between making money and just working for free while hoping taxes sort themselves out. They will not.