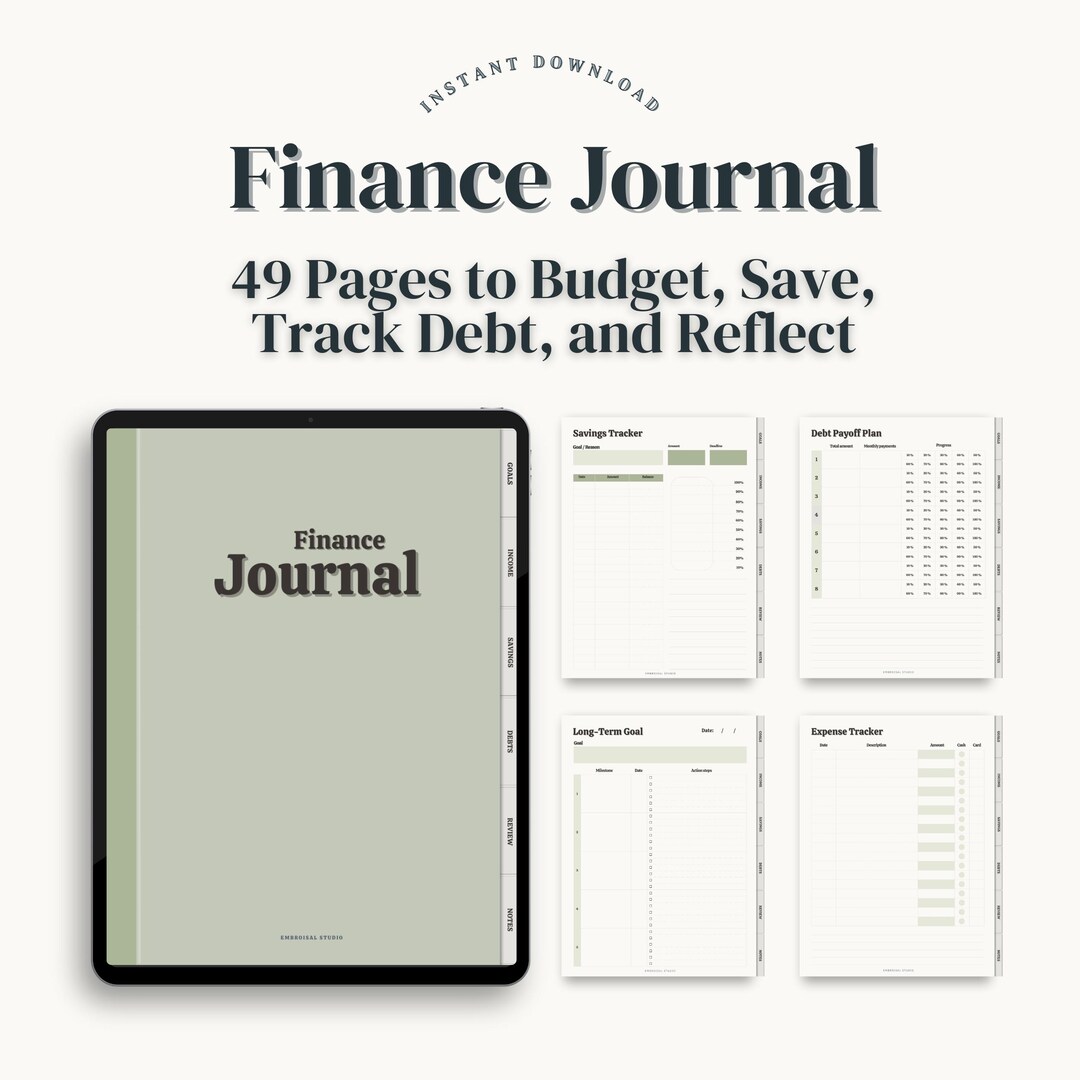
Keeping a Finance Journal in GoodNotes
GoodNotes is a PDF annotation tool first and foremost. A lot of people try to repurpose it for things it wasn't built for, like structured financial tracking. It can work, but you have to understand what the app actually does before you start fighting it. I spent about six months trying to make a monthly budget spreadsheet live inside GoodNotes and learned pretty quickly that it doesn't handle cell formulas or data validation the way Excel or Google Sheets do. The workaround I ended up using was much simpler than I expected. Here's how I actually set it up, and what went wrong along the way.
What a Finance Journal in GoodNotes Actually Looks Like
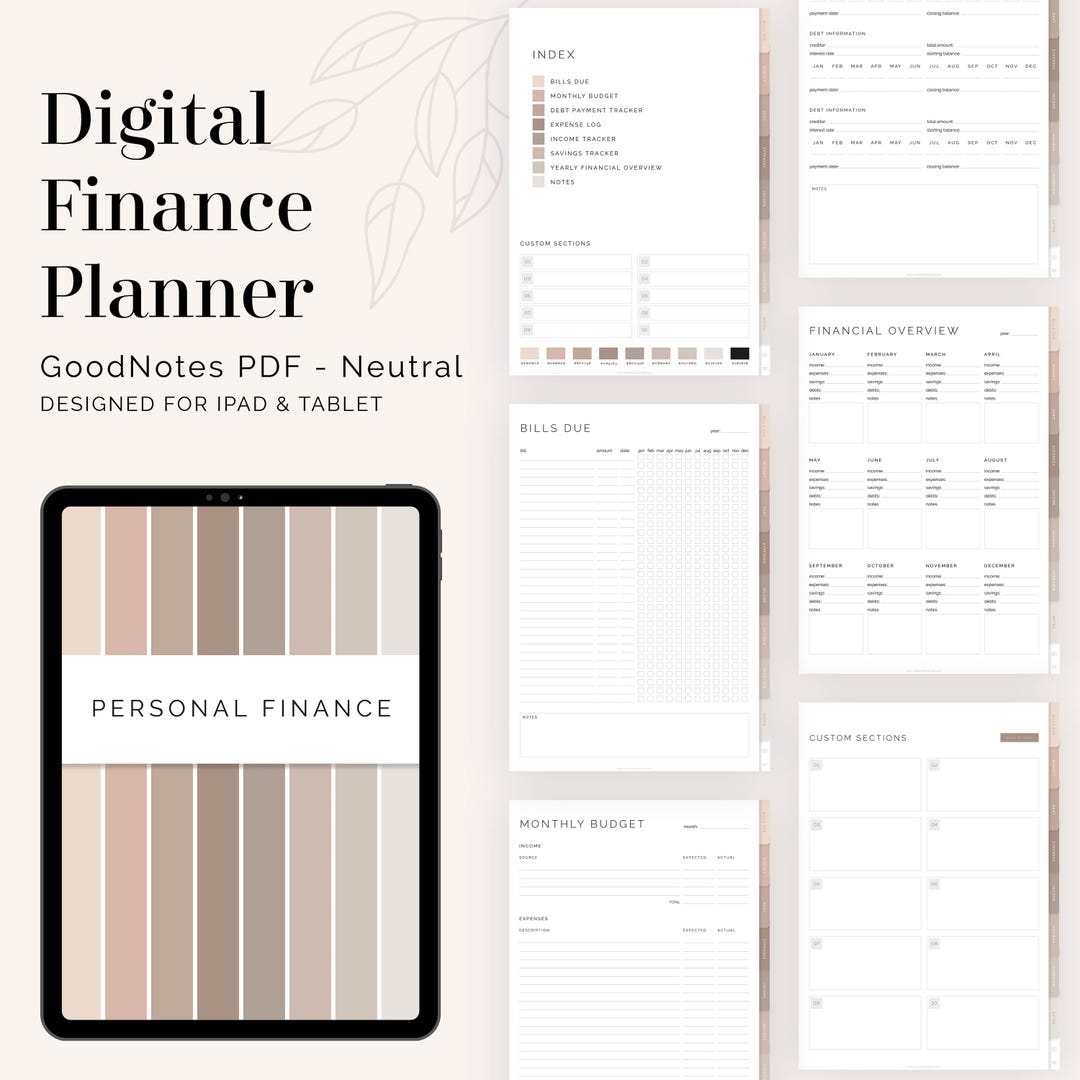
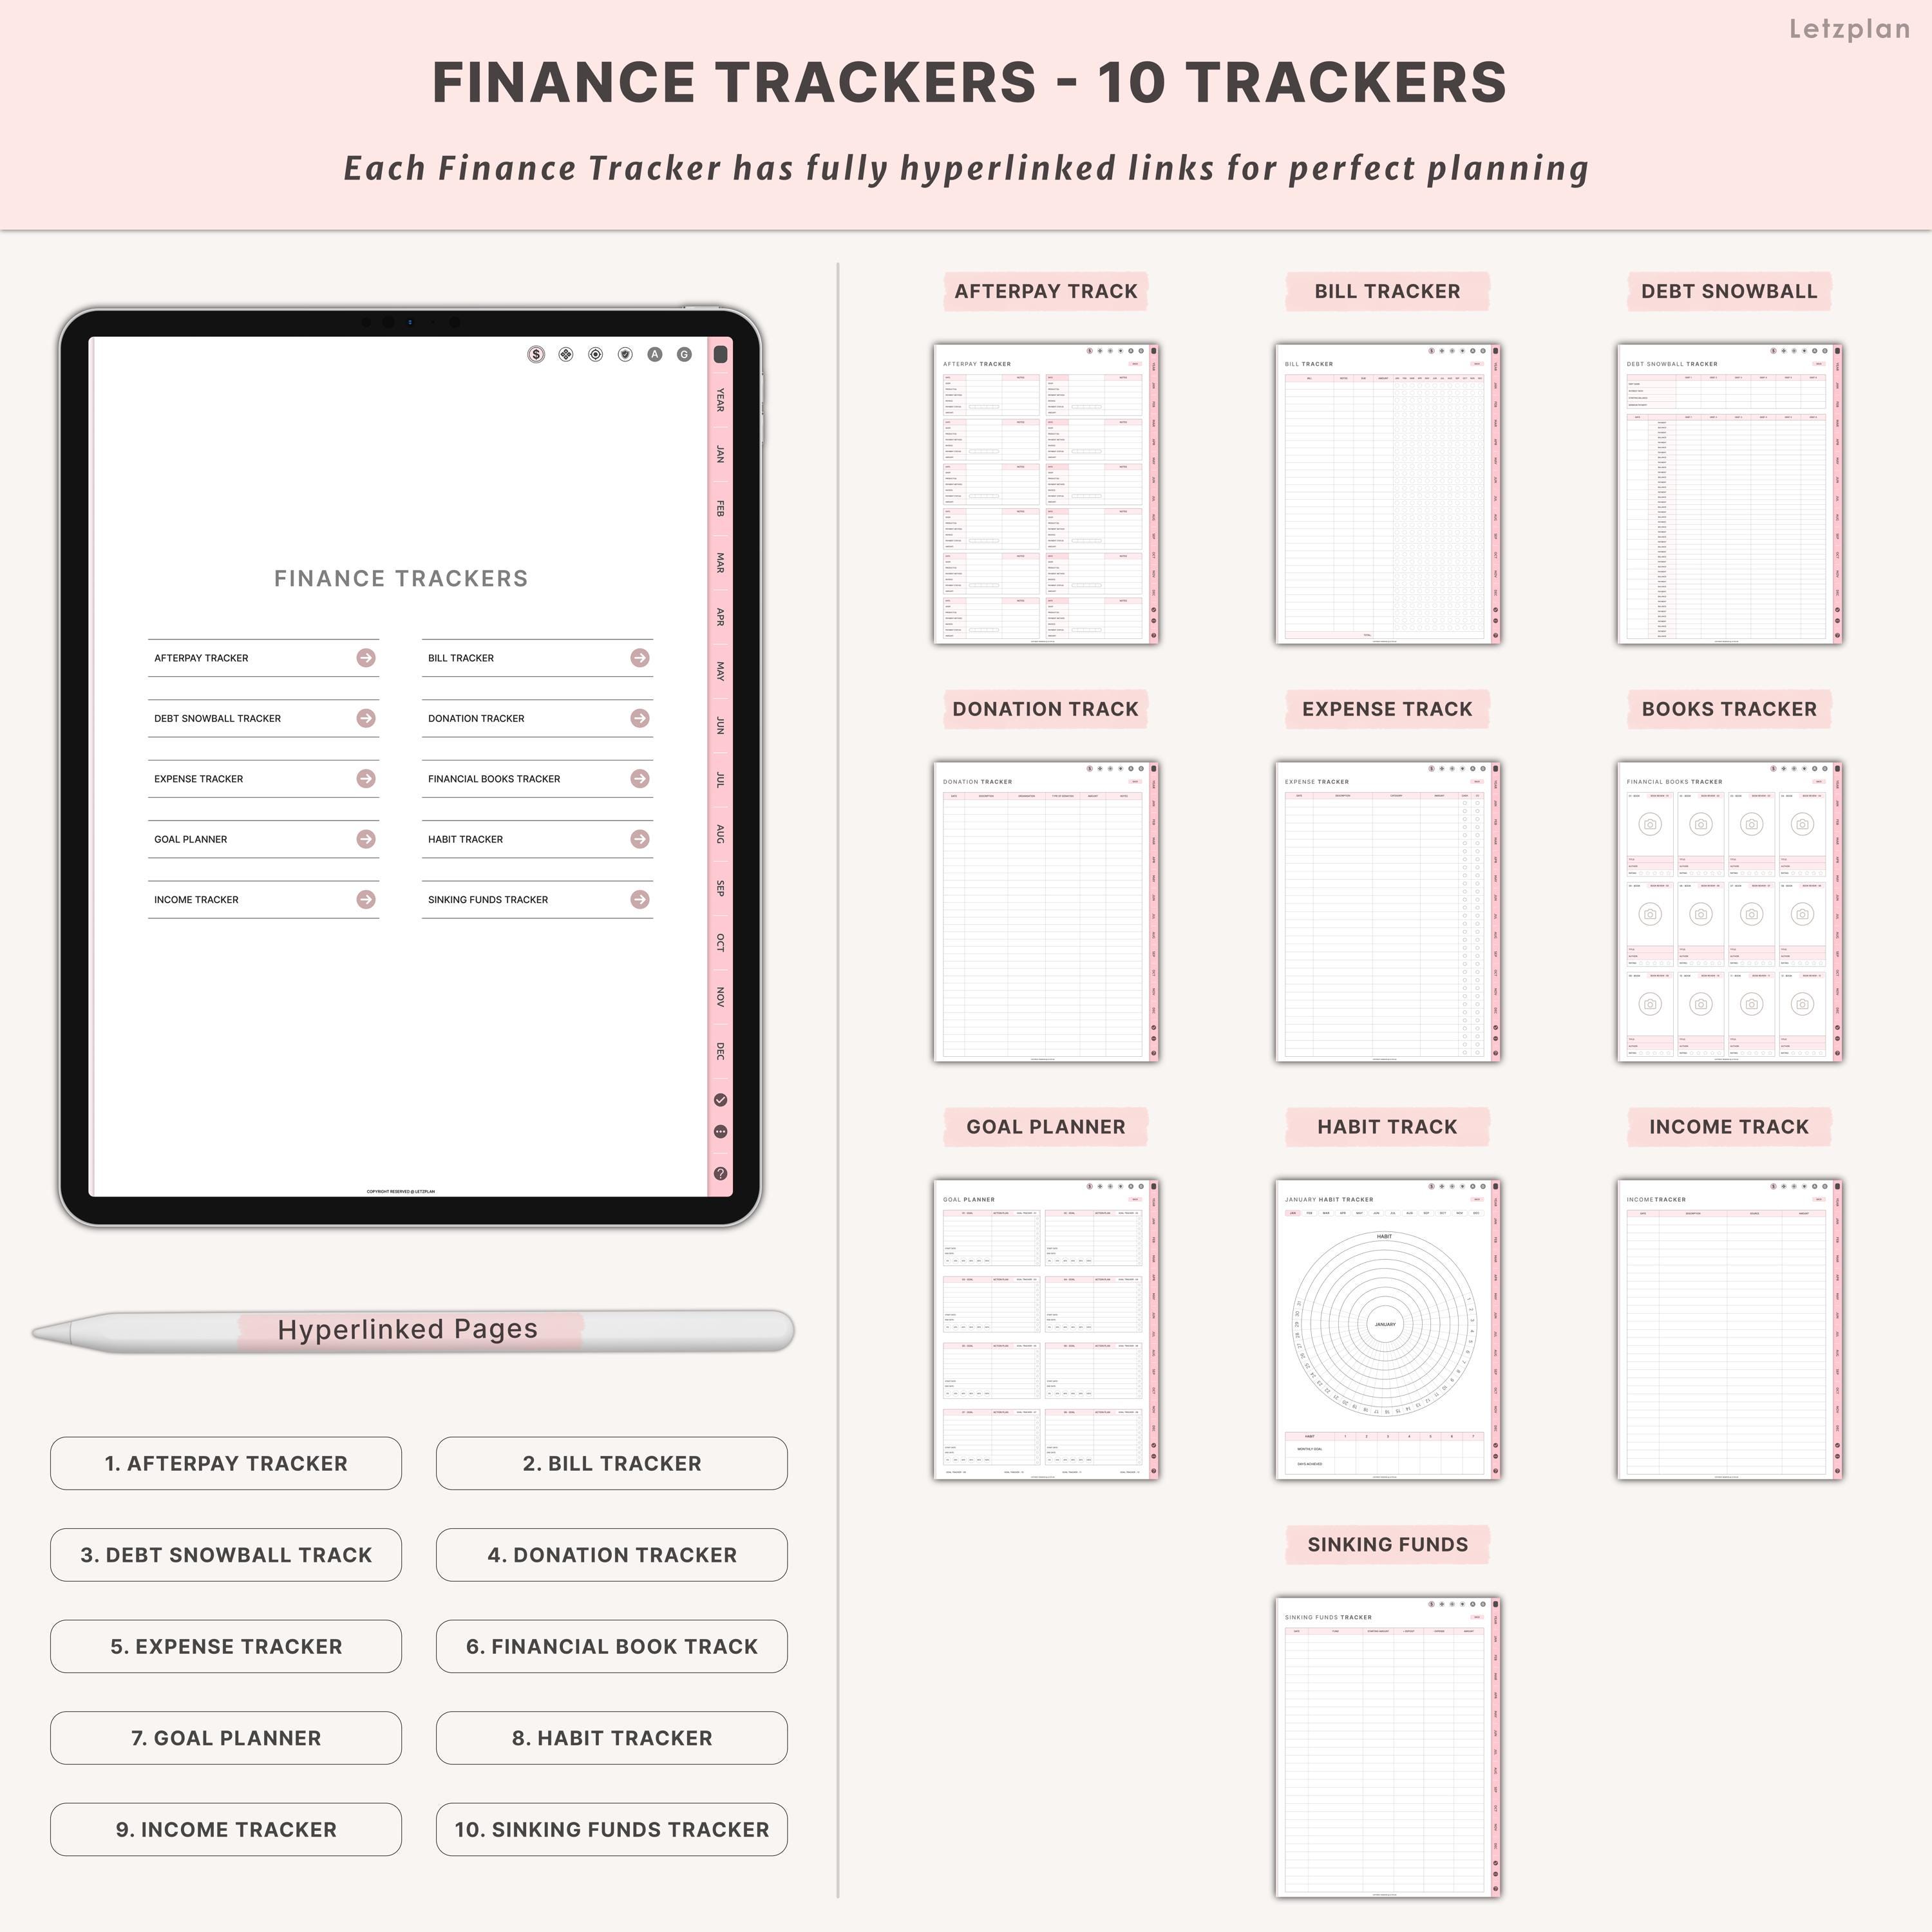
A finance journal is just a place where you record income, expenses, and savings targets over time. In GoodNotes, that means you're working with PDF templates — printed-style layouts that you fill in by hand using an Apple Pencil or stylus. You're not building a relational database. You're writing. The act of handwriting your numbers forces you to slow down and actually look at each transaction instead of mindlessly tapping "approve" in an app. That's the whole point for most people who choose this route. I used the Finance Journal Goodnotes For Adults template system, which is just a community-shared term for the various pre-made PDF layouts you can find on sites like TeachersPayTeachers, Etsy, and the GoodNotes Gallery. They come in different formats — weekly trackers, monthly summaries, debt payoff logs, cash envelope sheets. Some of them are gorgeous. Most of them are also missing fields you'll actually need within three weeks.
Setting It Up (The Part Nobody Warns You About)
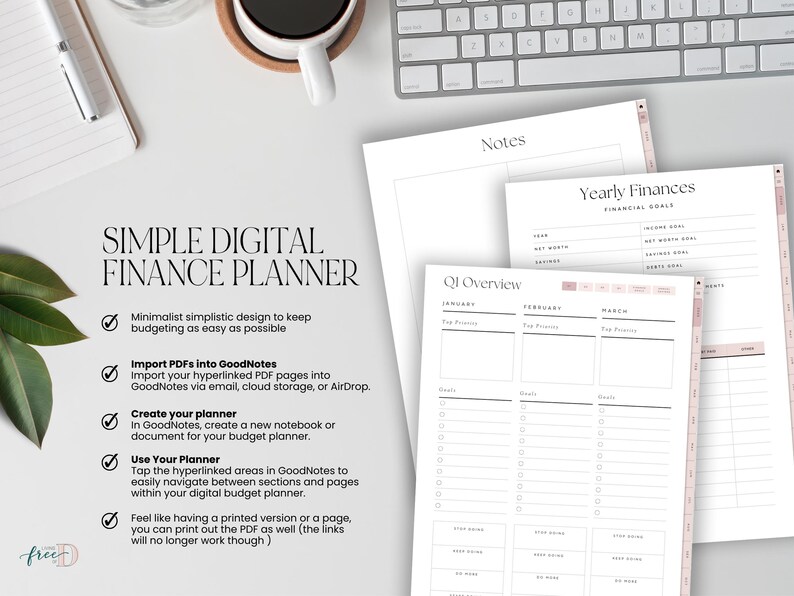
First, you need GoodNotes installed. On iPad it's free to try, then about ten dollars. On Android there's a similar app called Nebo, but the finance journal template ecosystem is much smaller. Stick with GoodNotes if you can. Download or import your chosen PDF template into GoodNotes. Create a new folder labeled "Finance Journal" so it doesn't get buried under whatever random documents you've already got sitting in your library. When you open the template, you'll see a blank page or a grid of tables. That's your workspace. Use the pen tool — the fine liner is usually best for numbers, the brush for headings if you want them to stand out. Set up a color system that actually lasts. I tried using five different highlighter colors in month one and gave up by day fourteen. Two colors, maybe three if you're tracking debt separately. Blue for income, black for expenses, red only for things that went wrong. Keep it boring. Here's a problem I ran into that almost made me quit the whole thing: I imported a monthly template that had fixed boxes for every day of the month. Then February came around and I had an extra day sitting there with no box. I almost threw the whole template out. Instead I just drew a new box by hand, extended the grid lines, and moved on. GoodNotes lets you do that. You're not locked into the original layout unless you want to be. That flexibility is probably the biggest advantage this has over actual spreadsheet software for casual tracking.
Get the Full Details
How I Actually Used It Day to Day
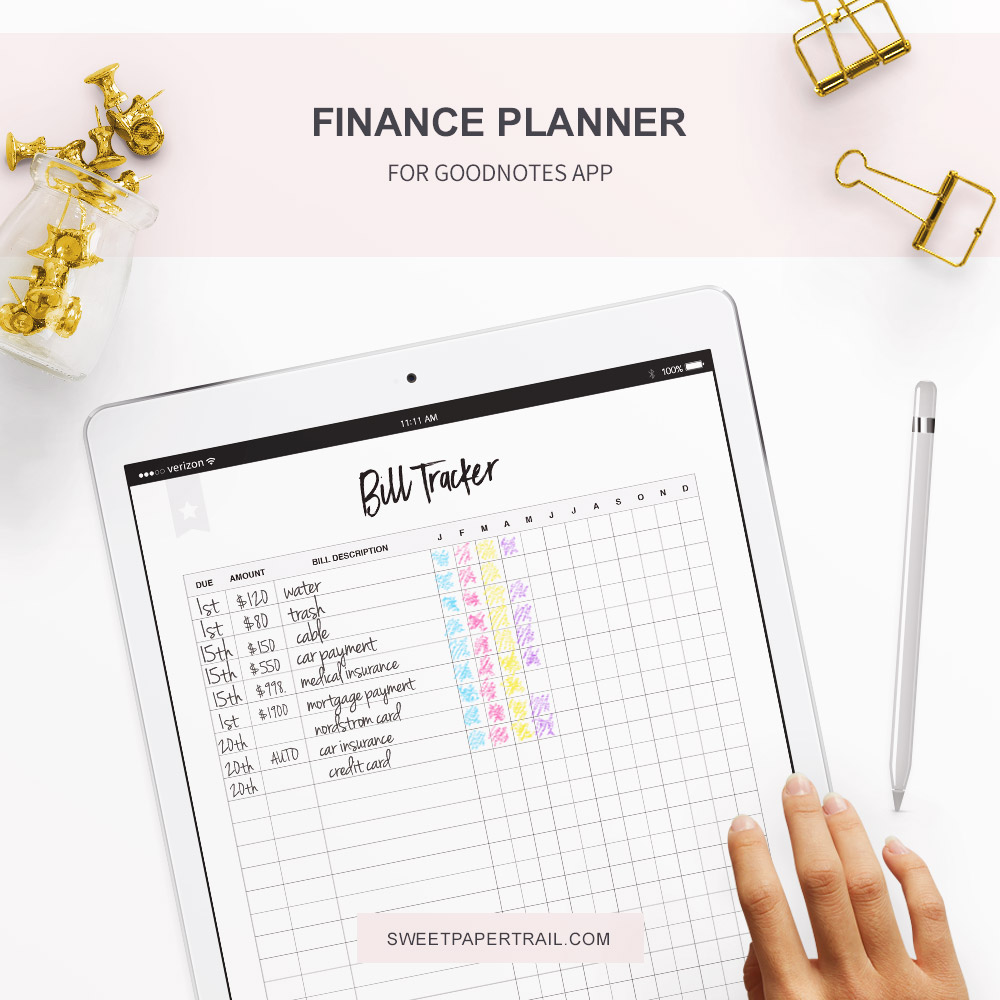
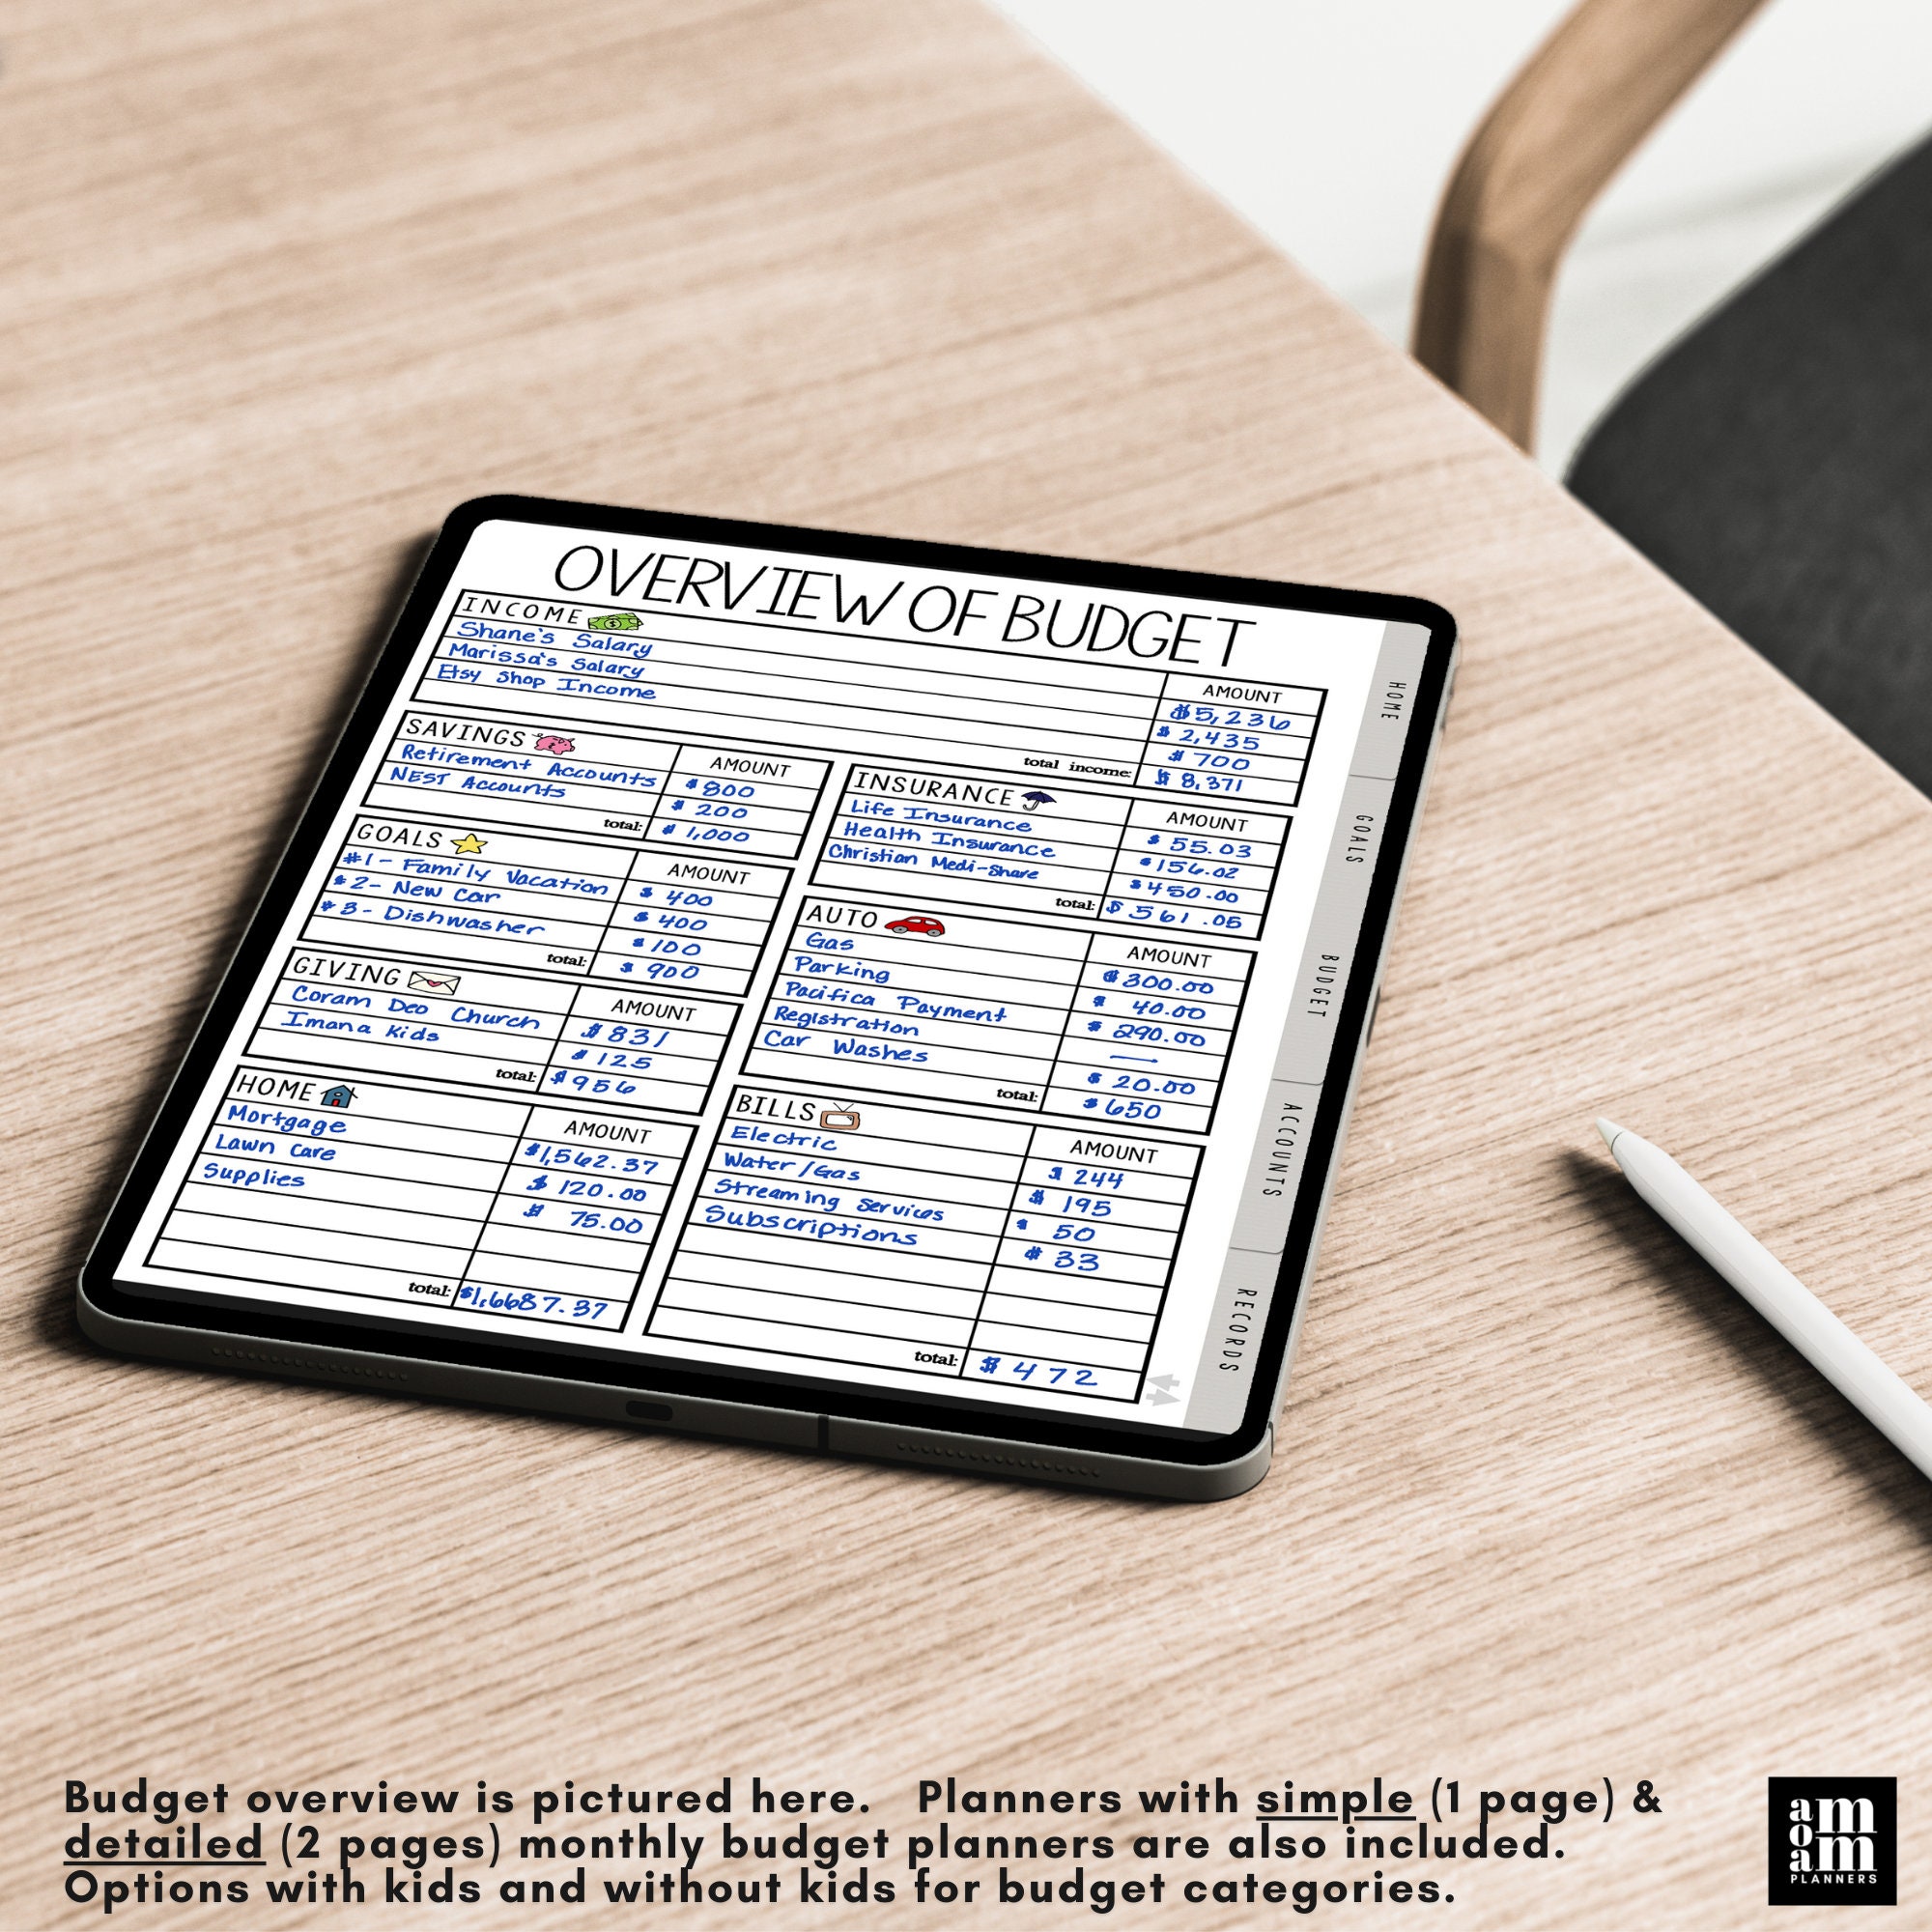
I kept GoodNotes open on my iPad every evening while I made dinner. Receipts were scanned into a separate folder — I used the Notes app for that, not GoodNotes — and I'd transfer the key numbers into my journal by hand. Spending twelve dollars on groceries gets a different kind of attention when you physically write "$12.47 — groceries — Whole Foods" instead of just scrolling past a notification. It sounds dramatic but it works. The friction is the feature. For recurring bills, I made a separate reference sheet in the same notebook. Rent, phone, car payment, insurance — everything with a due date column. I reviewed it once a month and updated the status of each one. That way my main journal page stayed clean and focused on the stuff that actually changed every day. The trick that most people miss is syncing. Get your GoodNotes set up to sync through iCloud or OneDrive, then access it from your Mac or PC too. I do backups that way and I occasionally pull up last month's pages on my laptop to compare spending patterns. It's slower than a pivot table but good enough for something you're looking at once a month.
The Downsides, Honestly
GoodNotes doesn't sum columns. If you want a total, you calculate it yourself or use a calculator. This isn't a bug, it's just how the app works, but if you're coming from spreadsheets it feels annoying at first. I just switched to doing the math on a small scratch paper area I keep at the bottom of each page. Takes thirty seconds instead of zero, but it's still fast. Another issue: the search function works on printed text but not on handwritten text unless you've enabled the handwriting recognition feature. It's okay but not great. I ended up giving each page a typed label in the GoodNotes file browser instead of relying on search. Much more reliable. And the biggest limitation: if you lose your iPad or your cloud account glitches, you don't have a safety net unless you've been backing up. I learned this the hard way when iCloud refused to sync for about forty-eight hours during a trip and I couldn't access my journal at all. Now I export a copy to my computer every Sunday. Five minutes, done.
Alternatives Worth Considering
If handwriting everything sounds like too much work, you could just use a spreadsheet. Google Sheets works fine for this, it's free, and it actually adds things up for you. If you want something between a spreadsheet and handwriting, YNAB or Monarch Money handle the math and let you add notes if you want. Neither one has the tactile satisfaction of putting pen to paper, but they're more functional. Some people use Botha, a GoodNotes-based system specifically built for finance tracking. It's more structured than my approach and costs money, but if you're serious about this kind of manual tracking it might save you the trial-and-error time I went through. The finance journal Goodnotes For Adults setup isn't for everyone. It requires a habit, a device with a stylus, and the patience to write out numbers instead of letting software do it. But for the people who actually stick with it — and that's the hard part, not the setup — it tends to change how they think about money in a way that automatic trackers never do. The slowness is the whole point.