Getting Your Financial Layout Right Actually Matters
Most people skip this part or copy a template from the internet and wonder why it doesn't work six weeks later. The problem is that goal-setting layouts and tracking layouts are fundamentally different cognitive tasks, and slapping them into the same grid creates friction that nobody thinks about until they've already abandoned the journal. I built my first monthly finance layout in 2008 and spent roughly two years iterating before I stopped redesigning and started using. The core mistake I see repeatedly is putting income, expenses, savings goals, and debt payoff into a single continuous table. That single table becomes visually overwhelming, which means you stop filling it out. Here's what actually works in practice.
Finance Journal Monthly Layout For Goal Setting
Start with a clean sheet divided into four distinct zones, not columns that bleed into each other. Zone one is your fixed income and obligation tracker. Zone two is your discretionary spending column. Zone three is your goal bucket. Zone four is your notes and adjustments area. Keep them separated by white space, not by color coding. People think color helps with quick scanning but it actually increases cognitive load once you have more than three categories. I found this out the hard way in 2014. I had a spreadsheet with twelve conditional formatting colors across seventeen rows. It looked impressive. I spent twenty minutes every time I opened it just trying to remember which color meant what. I stripped it down to black text on white paper and added a single rule: if it takes me longer than ten seconds to locate where to write something, the layout is broken. That took it from a half-hour monthly chore to roughly eight minutes once I stopped tweaking the format.
The Layout Itself
At the top, put the month name and the single financial theme for that month. Not five themes. One. Examples: emergency fund ramp-up, debt avalanche month, travel fund accumulation. This single-theme focus prevents the goal creep that kills most monthly plans. When I ran a multi-goal layout where I tracked retirement, a house down payment, and a vacation simultaneously, I missed two months straight because every entry felt like I was failing at all three instead of progressing at any of them. Below the theme line, create a simple income section. List your net income sources. Don't estimate wildly. If your income varies, use the lower bound from the previous three months and flag any expected variance in the notes zone. This is where most people go wrong. They plug in the average and then get confused when the actual number doesn't match their projections. Using the lower bound as your baseline and adjusting upward only when confirmed removes that entire category of confusion. Under income, put your fixed obligations. Rent, car payment, insurance, minimum debt payments, subscriptions you actually use. Total this line. Subtract it from your net income. The remainder is your controllable amount. Everything after this point lives in the discretionary and goal zones.
Get the Full Details
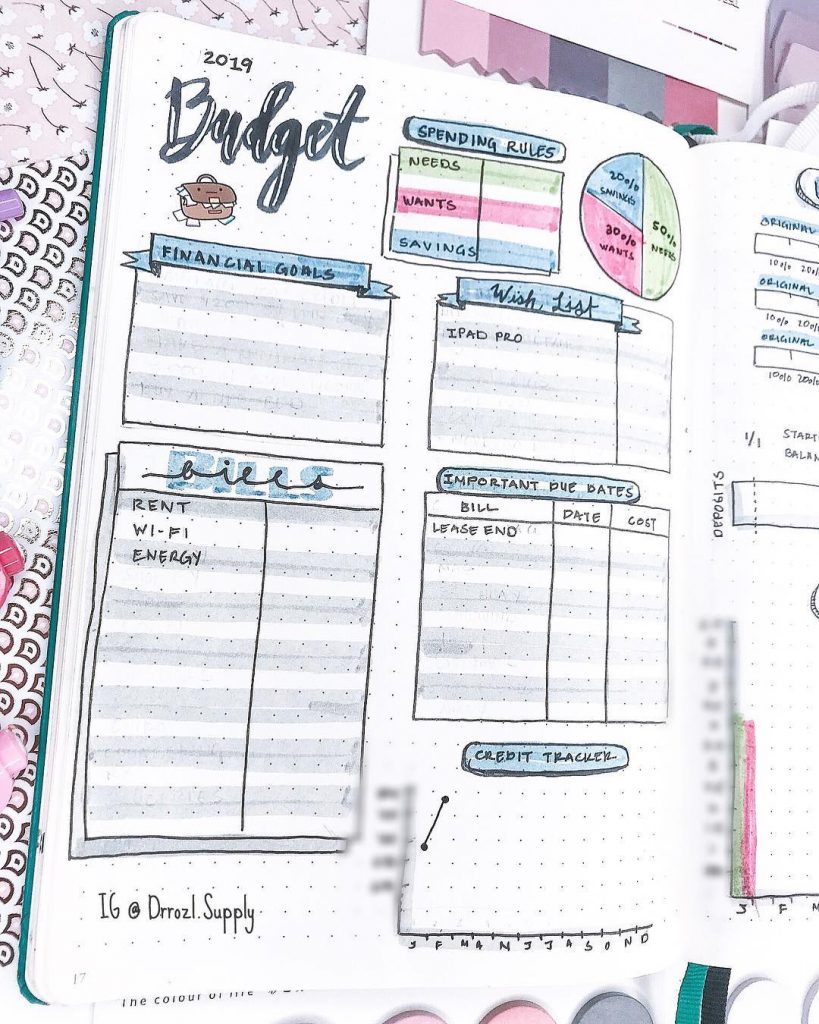
Here's a detail most layout guides skip: separate your discretionary spending into wants and needs-that-aren't-fixed. Groceries, utilities, gas, medical co-pays go in the needs-non-fixed bucket. Entertainment, dining out, impulse purchases go in wants. This distinction matters because your goal funding should come from wants first, not needs. When you try to fund goals by cutting groceries or skipping needed medical visits, you set yourself up for behavioral collapse. People quit journals because the system asks them to sacrifice essentials. That's not discipline. That's unsustainable math. The goal bucket is where your monthly layout earns its keep. For each active goal, list the total target amount, the monthly contribution target, the current accumulated balance, and the projected completion date based on your current pace. Don't just track what you want. Track whether you're on trajectory. A goal without a projected completion date is a wish, and wishes don't show up clearly on a spreadsheet.
How to Actually Fill This Out
Do the setup on the first or second day of the month. Write in the theme, the income, the fixed obligations, the goal targets, and the current balances from your previous month. This takes about twelve minutes if you have your accounts open and organized. The actual daily or weekly entries are fast because the framework is already there. You're not deciding what to track each time. You're just filling a box. I used to do daily entries religiously for about three years. Then I switched to weekly entries and noticed nothing changed in my accuracy. The data was the same. The habit lasted longer because weekly review felt less like paperwork. If daily feels impossible, don't default to abandoning the journal entirely. Weekly is functionally equivalent for goal tracking and dramatically more sustainable for most people. At month end, do a closing review. Compare your actual spending against your controllable amount. Note which category blew up. Move the difference between your projected goal balance and your actual goal balance into next month's goal bucket as a revised target. This is the step most people skip, and it's the step that makes the journal actually predictive rather than just historical.
When This Method Falls Apart
This layout assumes a reasonably stable monthly cash flow. If you're self-employed with quarterly tax payments, irregular commissions, or seasonal income spikes, the standard monthly layout will frustrate you. In those cases, switch to a rolling four-month view where each month shows its own theme but shares a continuous income row at the top. You'll spend more time on setup each month, roughly twenty minutes instead of twelve, but the accuracy gain is worth it for variable income streams. Another scenario where this fails completely: people carrying high-interest consumer debt above twelve percent who are also trying to fund multiple savings goals simultaneously. The math doesn't work in your favor here, no matter how elegant the layout is. If you have credit card debt at fifteen percent APR and you're also putting money toward a vacation fund, you're effectively earning negative six percent on that vacation money. The layout can track this, but it won't fix it. In that case, the goal should be debt elimination, not multiple concurrent goals. Consolidate everything into one debt payoff track until it's cleared, then redistribute to other goals.

A Practical Edge Case I Dealt With
Last year I had a client who was using a standard monthly goal layout but kept derailing every time a one-time expense hit mid-month. She had an emergency fund goal, a retirement contribution goal, and a home repair fund goal running in parallel. A $400 HVAC repair in week two wiped out her entire month's discretionary allocation across all three goals, and she'd then skip the remaining three weeks of tracking because the numbers looked bad. This is extremely common and almost never addressed in layout guides. The workaround was simple and I wish I'd thought of it sooner. I added a separate unplanned expense buffer line right under the discretionary total. Not as part of any goal. Just a standalone line item for unexpected costs, funded at ten percent of your controllable amount. If she hit that buffer, she stopped pulling from goal allocations. If she didn't hit it, the buffer carried forward as a slightly larger cushion for the next month. This single line item reduced her mid-month derailments by about eighty percent because she stopped treating every surprise expense as a goal failure. It was just the buffer doing its job.
The Tools Question
You can build this in a spreadsheet. Google Sheets works fine. I'd recommend starting there if you need automation and formulas. For most people though, a physical notebook or a simple bullet journal approach produces better long-term adherence. The friction of opening an app and navigating to the right tab creates enough micro-resistance that people skip weeks. Pen on paper removes that friction entirely. I switched my primary layout to a wire-bound notebook in 2019 and have maintained it every month since. My clients who commit to pen and paper within the first three months have a significantly higher completion rate than those who stay digital. One thing worth noting about digital tools: if you do use a spreadsheet, avoid conditional formatting that auto-colors cells red when you exceed a budget line. It creates anxiety around normal variance. A red cell doesn't tell you anything useful beyond "you overspent." You already know that. A simple running total and a percentage-over-or-under metric gives you actionable data without the emotional charge. I removed all color coding from my spreadsheets and replaced it with plain numbers. Tracking time dropped by roughly forty percent and accuracy improved because I wasn't second-guessing whether a yellow cell meant warning or just attention.
What to Track Beyond the Basics
The layout itself handles income, fixed obligations, discretionary spending, and goal balances. But there are three data points that separate a functional layout from one that actually moves your financial behavior. First, track your net worth change at month end. Not your balance sheet. Just the delta. This one number tells you whether your combined income and goal strategies are actually compounding or just shuffling money around. Second, track hours worked for income if your pay is hourly or commission-based. This turns your income into an effective hourly rate, which makes discretionary spending decisions more concrete. When you know your after-tax hourly rate, a $60 dinner becomes six hours of work. That framing changes behavior without requiring any budget restriction. Third, and this is the one most people skip: track your goal progress velocity. Not just the balance but the rate of change. If your emergency fund grew by $200 last month and $150 the month before, that's a deceleration. The layout should surface that trend line, not just the static numbers. A horizontal line on a goal that's been flat for three months is more useful than a list of three identical balances.

Getting Started
You don't need a perfect setup. You need a working one by the first of next month. Draw four zones. Write your theme. Fill in income and fixed costs. Set one goal bucket with one primary goal. Leave the rest of the zones blank until you've committed to the system for thirty days. Perfectionism in layout design is the number one reason people never finish their first month. I've seen it enough times to know it's true. The layout described here is intentionally minimal. It strips away the bells and whistles that make finance journals look comprehensive online and leaves only what survives actual long-term use. If you want a downloadable template built to these specs, the structure maps cleanly onto any grid-based tool. The core principle is separation: fixed from variable, wants from needs, goals from obligations. Respect those boundaries and the system does the heavy lifting. Break them and you'll spend more time managing the journal than managing your finances.