Getting Started With a Finance Journal Notebook
I picked up a paper notebook about seven years ago when my banking apps stopped making sense. They showed me numbers but never told me where those numbers came from. The spreadsheet route failed quickly because I was too tired after work to log transactions. A notebook forced me to sit down and look at what I actually spent. The basic setup is simple. Buy any ruled notebook, preferably one that lies flat. Pick a pen you like writing with. On the first page, write your total balance across every account you have, then start fresh each month with a clean two-page spread for income and another two pages for expenses. That is it. Everything else is just detail work.
Finance Journal Notebook For Adults: The Monthly Framework
Here is how the system actually works in practice. At the top of your expense pages, write down your fixed monthly obligations first: rent, insurance, subscriptions, loan payments. These numbers do not change much so they are easy to transfer month to month. Below that, create sections for variable categories like groceries, dining out, fuel, and entertainment. Leave enough room in each section for at least a dozen entries per category before you run out of space. The income side goes on the opposite page. List every source of money coming in for the month with the amount and date. Subtract total expenses from total income. What remains is your surplus or deficit. Do this calculation every single month even if it feels repetitive. The pattern it reveals usually shows something you did not notice otherwise. I ran into a real problem during year three of using this system. I had a category labeled "miscellaneous" that swallowed roughly $200 a month without explanation. I thought it was just small purchases I forgot about, but one month I forced myself to write down the exact description next to each misc entry instead of just noting the amount. The entries that month totaled $187 and included things like a gym bag replacement, three coffee shop visits, a phone case, parking fees, and a book from a convenience store. None of those were emergencies. They were all friction spending, the kind you make without really deciding to spend. I renamed that category to "unplanned purchases" and set a hard monthly limit of $50. My spending in that area dropped to $34 within two months.
The tricky part with any notebook system is maintaining it long enough for it to matter. Most people quit within six weeks because the novelty fades and the entries feel like homework. The workaround I found was to stop trying to be perfectly detailed. I switched to recording only transactions above $20 and grouping smaller items under rough daily totals. This cut my nightly logging time from about twenty minutes to roughly five minutes. The data quality dropped slightly but the consistency went way up, and consistency is what actually matters for spotting trends. Another thing nobody tells you about notebook-based finance tracking is that it changes how you spend in real time. When you have to physically write "dinner at Olive Garden $67" in a book in front of you at a restaurant, something about that act makes you reconsider. It is slower than tapping a card. That slowness is the point. Digital payments remove the psychological weight of spending money. A notebook puts it back. There are real limitations to this approach. You cannot search your data quickly the way you can with a spreadsheet. If you lose the notebook, you lose everything you recorded. Reconciling entries against bank statements is a manual process that takes time. And if you have complex financial situations involving multiple investment accounts, crypto holdings, or irregular freelance income, a simple notebook might not give you enough structure. In those cases, a hybrid approach works better: use the notebook for daily spending tracking and a spreadsheet or app for investment and debt management.
Get the Full Details
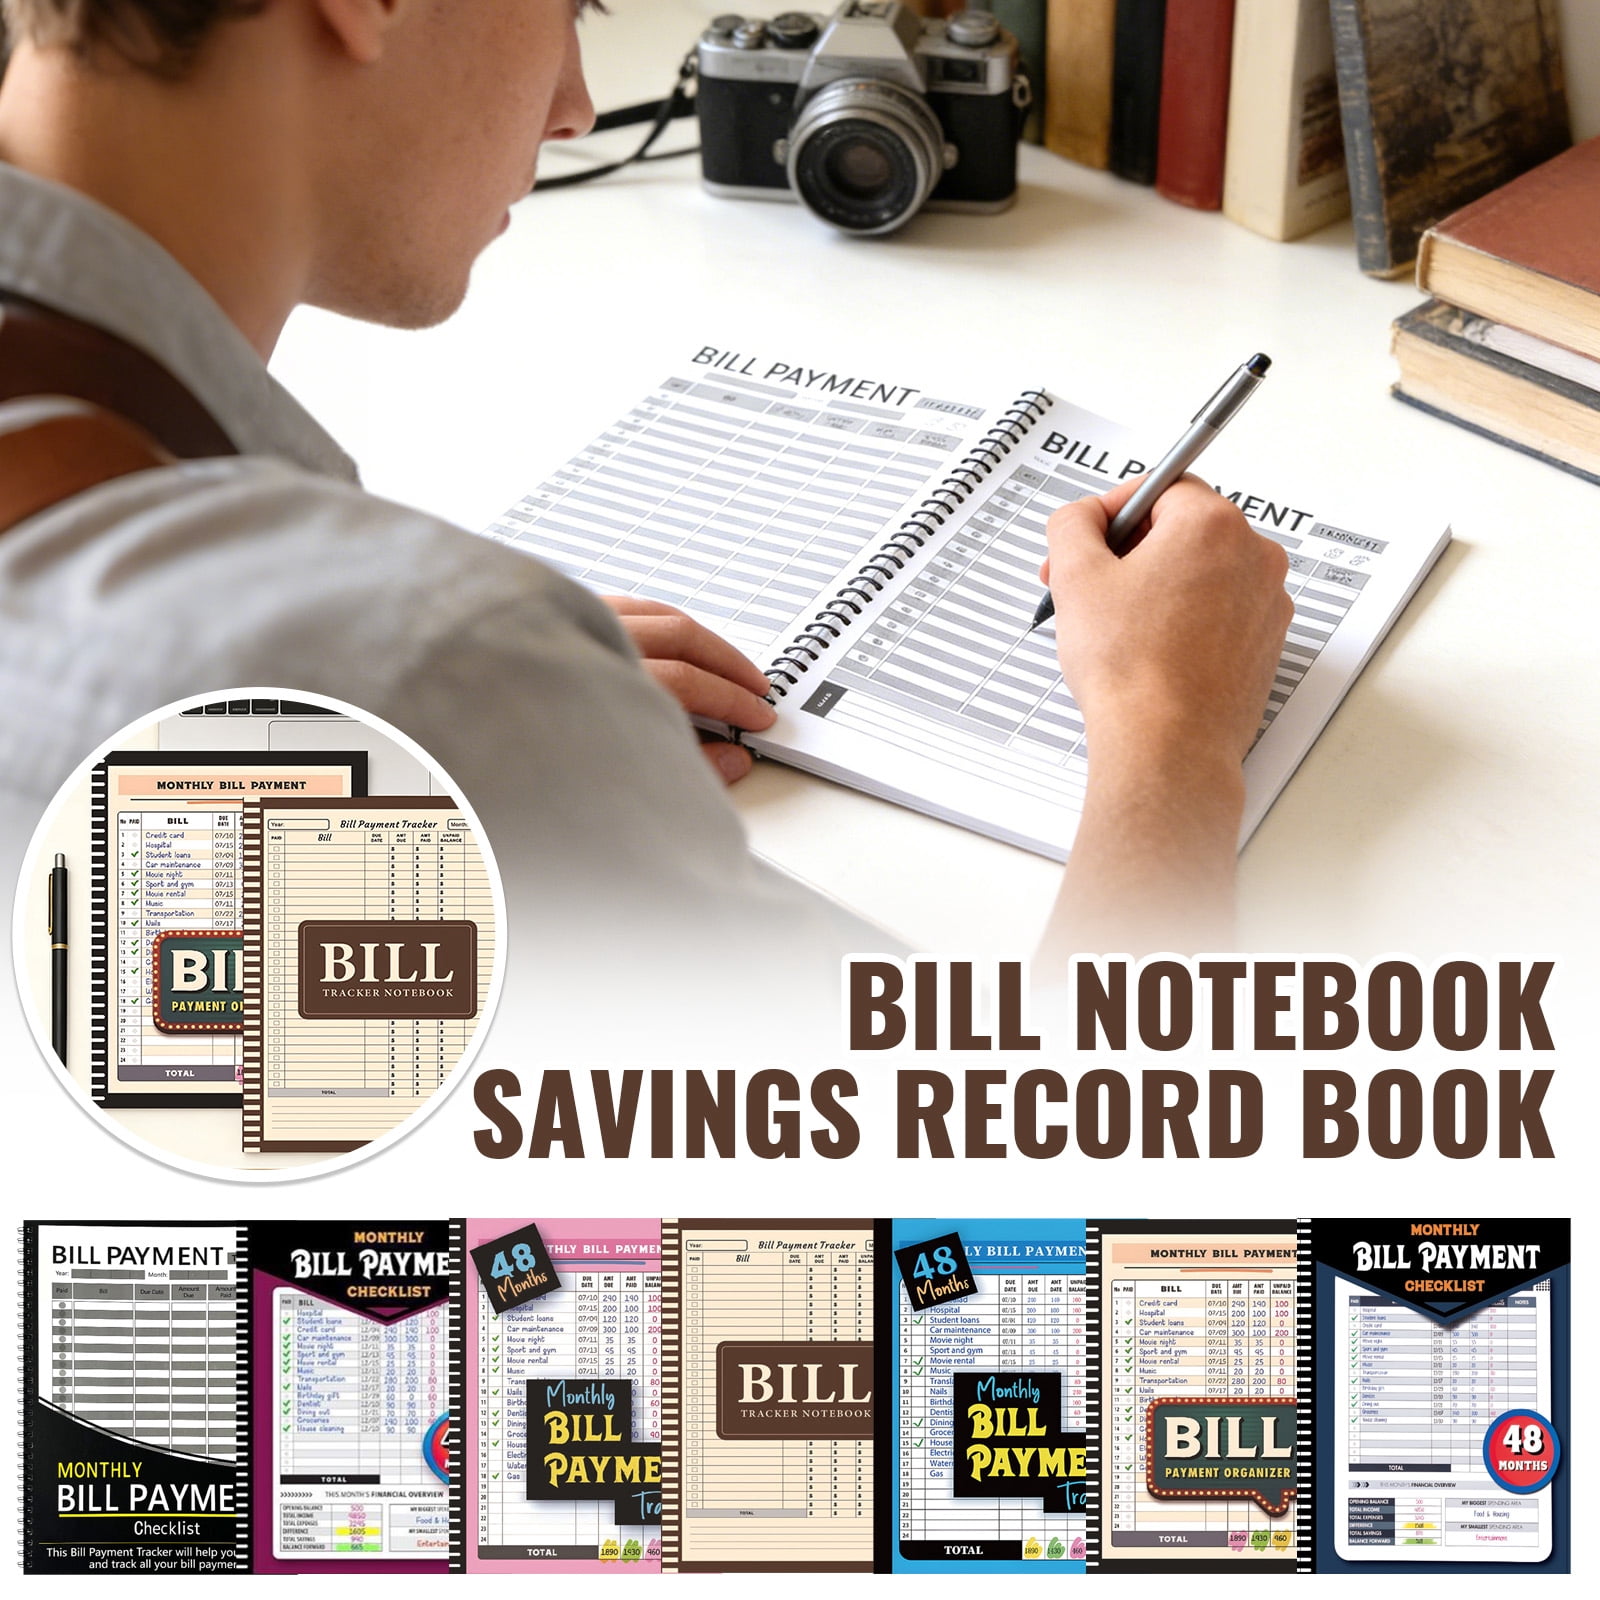
If you want to start with a structured format, there are pre-printed finance journal notebooks available online that handle the layout for you. These usually include monthly budget templates, savings goal trackers, and debt payoff sections built in. The tradeoff is that they cost more than a plain notebook and you are locked into whatever framework the publisher chose. A blank notebook gives you full control over the structure but requires you to design it yourself. The most practical advice I can give is to begin with just one month. Do not plan to use this forever. Commit to thirty days, record everything you can remember, and see what the data looks like at the end. If you finish that month and nothing useful jumped out at you, the problem is probably with your recording method, not the concept itself. Adjust the categories, try a different notebook format, and run another thirty days. The system only works if you actually use it, and the only way to figure out what works for you is to run a trial period and observe the results. For anyone reading this who wants a download of a blank monthly template to print and paste into a notebook, I have one available. It is a simple PDF with income tracking, expense categories, and a surplus calculation section on each two-page spread. Search for "blank finance journal template PDF" and you should find several free options. The ones that actually work tend to be the plainest ones with enough white space to write comfortably. Anything overly designed with too many boxes and charts usually becomes a chore to fill in and gets abandoned.