How I actually use spreadsheets to track my life without going insane
Most people approach personal finance spreadsheets the wrong way from the beginning. They try to build something that looks like a professional accounting ledger and then get frustrated when it becomes a chore to maintain. I spent about three years doing exactly that before realizing the spreadsheet should serve the habit, not the other way around.
Finance Journal Spreads For Self Improvement
The core idea is simple: you record every financial transaction with enough context that reviewing it later actually tells you something useful. Not just the amount and date, but the category, the emotion behind the purchase, and whether you'd do it again. That last column is what separates a budgeting tool from a journaling tool.
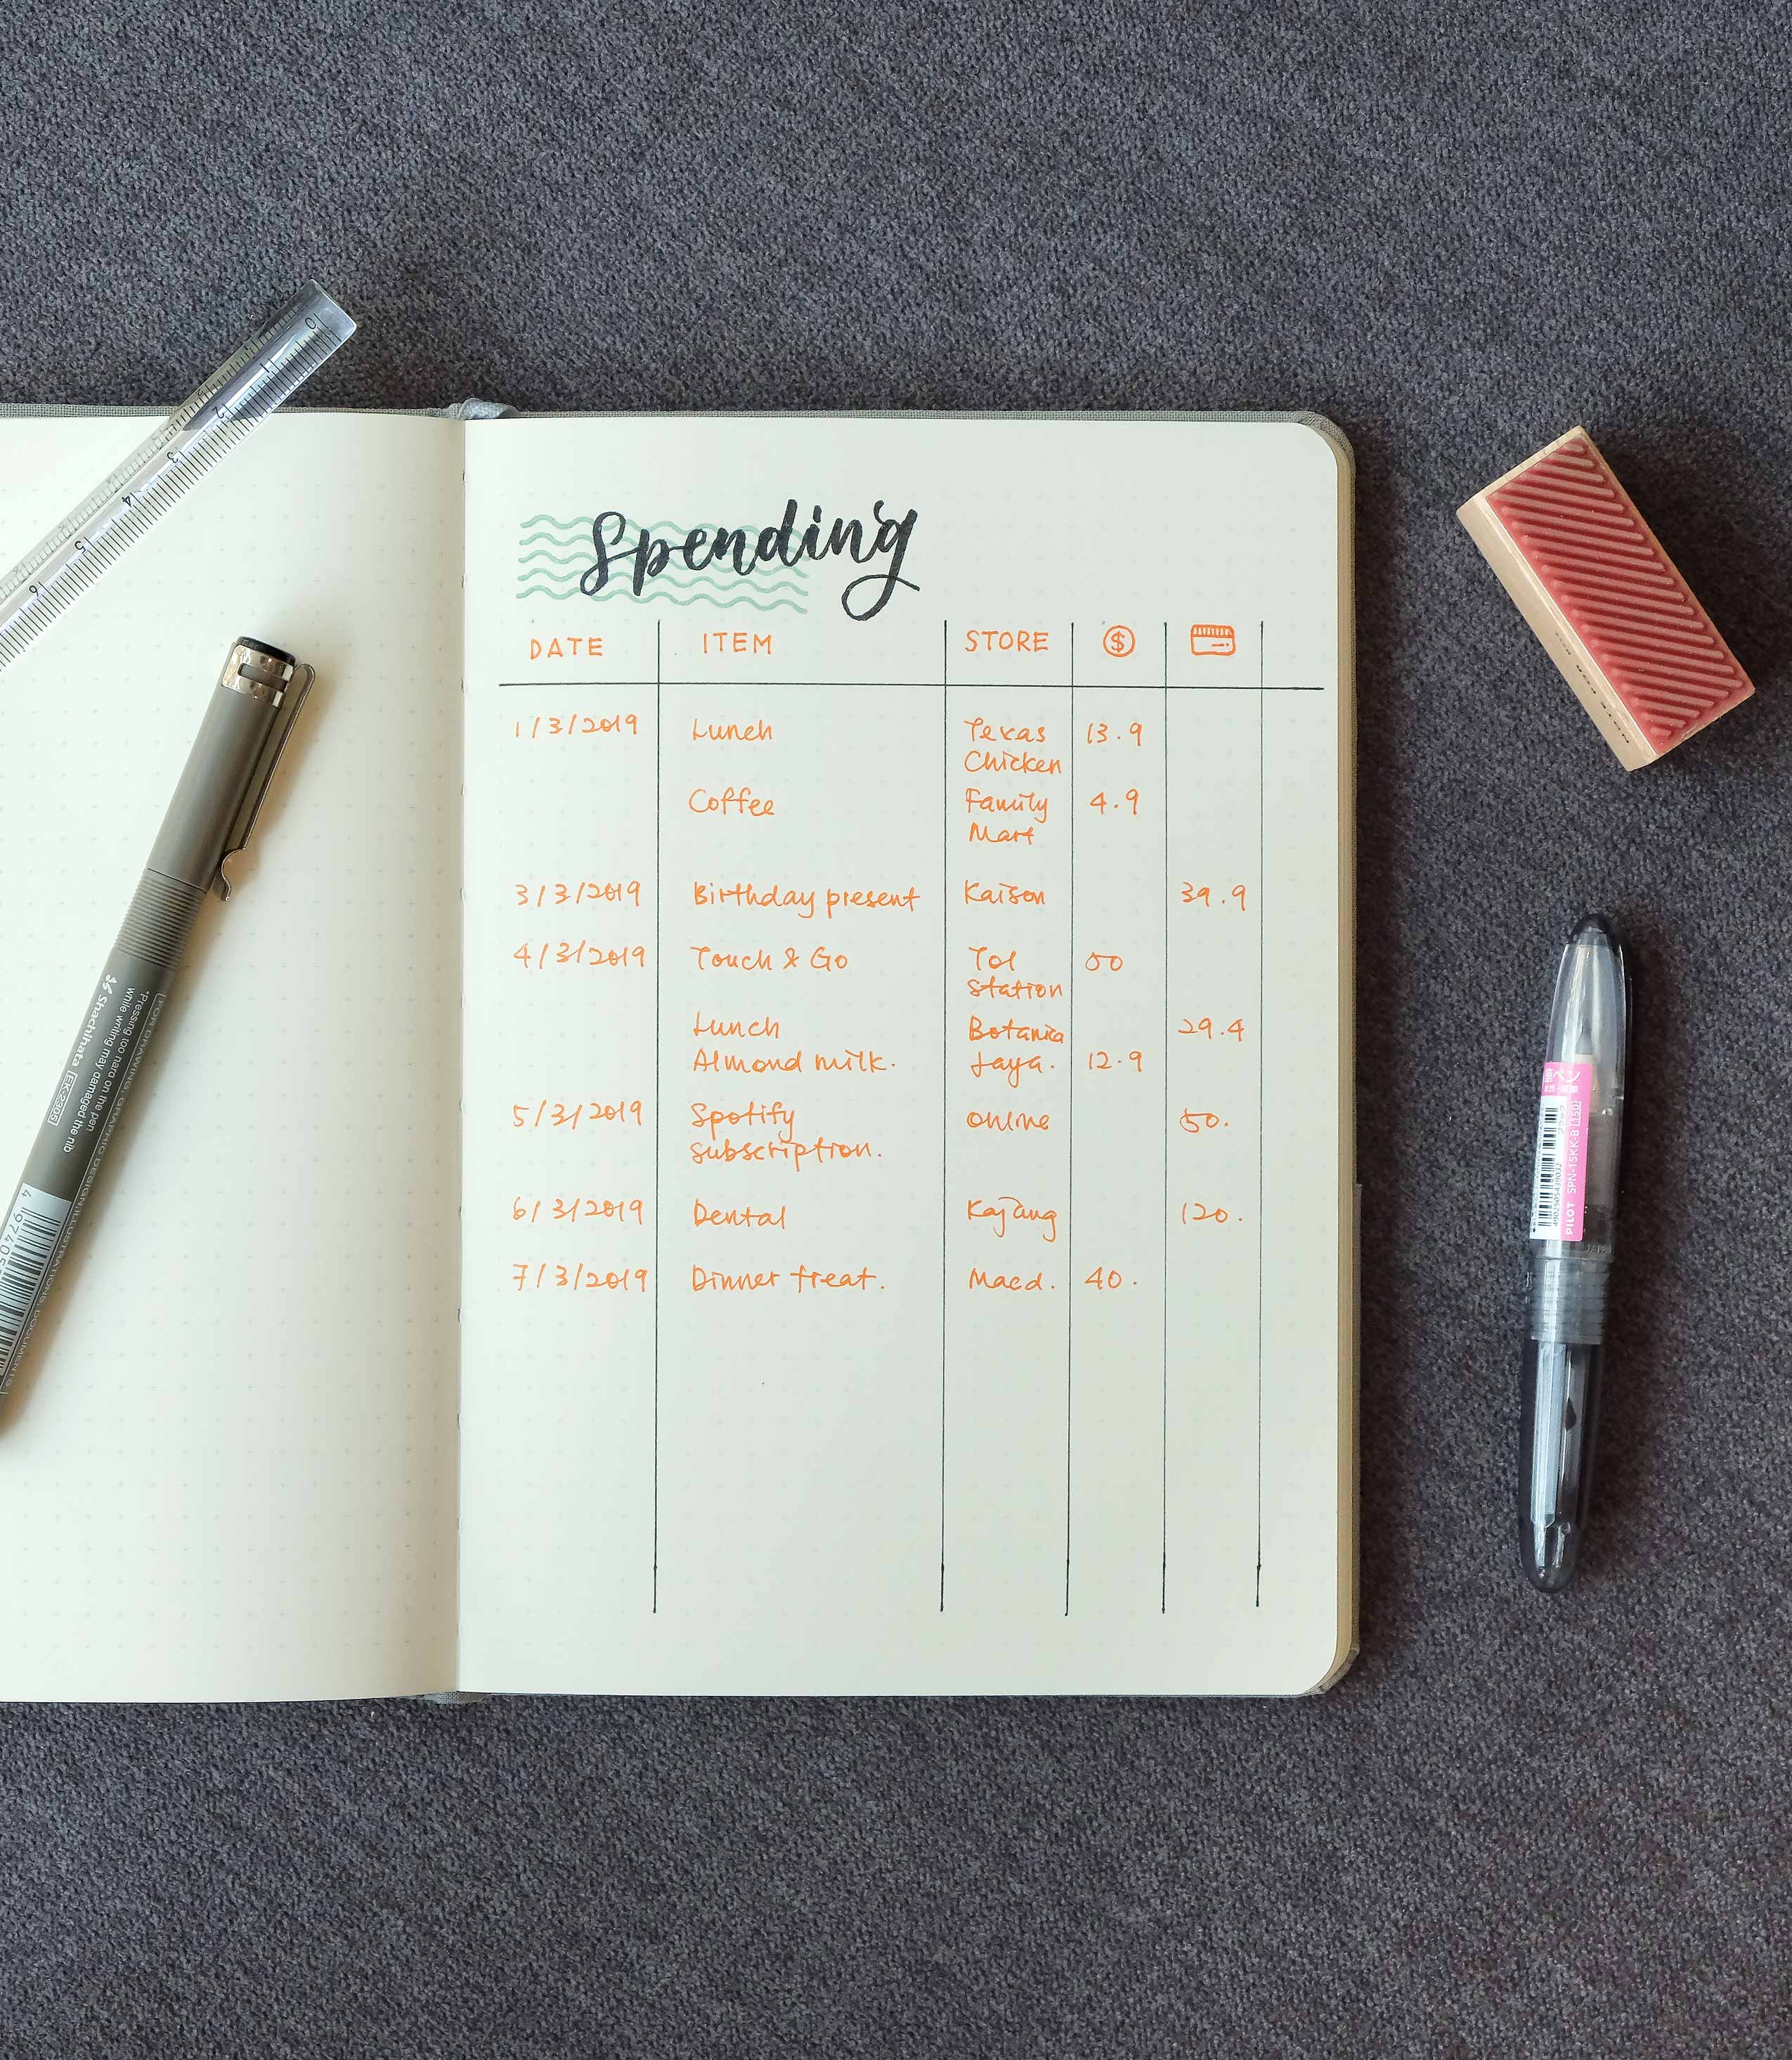
Here's what my actual setup looks like. I have a running transaction log with columns for date, description, amount, category, payment method, mood tag, and a notes field. The mood tag uses a five-point scale from "necessary" to "impulse regret." That sounds excessive until you've reviewed six months of data and noticed you spend roughly $400 per month on food delivery apps specifically when your mood tag reads "stressed" or "bored." That pattern is not obvious when you're just looking at totals.
I built my first version in Google Sheets around 2018. The one I use now started as a copy of that same sheet and has been iteratively stripped down to only the columns I actually reference during review. Everything else got deleted because I was never looking at it. The sheet currently has fourteen columns total, three conditional formatting rules, and two lookup tables for categories. It takes about forty-five seconds to enter a transaction.
The review process matters more than the data entry. I do a weekly scan every Sunday evening that takes approximately twelve minutes. I look at spending by category, check the mood-tagged entries against stress or social events on my calendar, and note any recurring subscriptions I forgot about. The monthly review takes longer, around twenty-five minutes, because I pull a pivot table by category and compare it to the previous month. This is where most people give up. The time investment is real.
One specific edge case that almost made me abandon the whole system: I have a joint account with my partner for household expenses. About fourteen months into using the spreadsheet, I kept double-counting shared purchases because both of us were entering them. The workaround was ugly but effective. I created a shared Google Sheet view-only link, and only one of us enters transactions from the joint account. The other person's individual spending goes into a separate personal tab. It's not elegant, but it solved the double-counting problem permanently.
Here's something beginners consistently miss. Category granularity follows diminishing returns. Tracking fifteen broad categories is manageable and usually sufficient. Tracking forty-seven subcategories turns the system into its own form of busywork. I learned this after spending six months maintaining a granular system and realizing I could predict my spending patterns accurately with just nine categories: housing, utilities, groceries, transportation, dining out, entertainment, healthcare, debt payments, and miscellaneous. That's it.
Another counter-intuitive point: the spreadsheet will not fix behavioral problems by itself. A friend of mine maintained a meticulously formatted budget for eight months and still overspent every single month. The spreadsheet showed him exactly where the money went, which should have been enough. It wasn't, because the data entry happened after the fact. The gap between impulse and recording is where the behavior lives. What eventually helped him was adding a mandatory thirty-second reflection in the notes field before submitting each transaction. Writing "this was a mistake" in lowercase took twelve seconds and somehow changed his purchasing decisions more than any total or chart ever did.
There are real limitations worth stating plainly. Spreadsheets require manual data entry, which means they only work if you actually do them. Automated bank feeds exist and solve this problem, but they introduce their own issues like misclassification and privacy concerns. If you have a high-volume transaction account with hundreds of entries per month, a spreadsheet becomes a full-time job. In those cases, tools likeYNAB or Even Dollar handle the automation better. The spreadsheet approach works best for people with moderate transaction volumes who want more narrative context than an app can provide.
Another honest limitation: spreadsheets are fragile. A deleted formula, a misplaced decimal, or a corrupt cell reference can silently corrupt months of data. I've had this happen twice. The second time cost me approximately two hours of reconstruction. Always maintain a monthly backup copy with a date-stamped filename. This takes thirty seconds and prevents an afternoon of frustration.
For getting started, download a blank template rather than trying to build from scratch. I keep a minimal version at this link that includes the transaction log, the weekly review pivot, and the mood-tag reference table. No charts, no dashboards, no automated formulas that break when you add a row. Just the core structure.
The actual learning happens during the third or fourth month of consistent use. That's when you have enough data to see real patterns instead of noise. Before that point, you're mostly just building the habit of paying attention. Don't expect breakthroughs in week one. Expect to forget to enter transactions, then remember, then build a slightly longer streak, then realize you spent more on takeout than you thought.
Gallery Finance Journal Spreads For Self Improvement
Finance Logs - Bullet Journal
12 Stunning Bullet Journal Spreads That Will Make You Actually Want to Budget
Managing Your Finance With Bullet Journal – Summorie
Self-Worth Journal — The Wellbeing Hub
Managing Your Finance With Bullet Journal – Summorie