Why Most Finance Journaling Falls Apart Before January Is Over
Most people set financial goals and write them into a journal with good intentions, then abandon it within three months. The problem isn't motivation. It's that the journal theme itself doesn't actually connect to how money works in daily life.
I've watched this play out with clients for years. The ones who stick with it don't use fancy apps or spend hours journaling. They pick a structure that mirrors their actual spending patterns and adjust it once per quarter. That's it.
Finance Journal Themes For Goal Setting That Actually Work
The core insight nobody talks about is that a finance journal needs a thematic anchor, not just blank pages. Without a theme, you end up writing the same transactions over and over with no pattern recognition. The theme gives you a lens to filter what matters.
Here's what I use with my own tracking and what I recommend to people who want something that holds up long-term:
Theme one: the category constraint. Instead of journaling by date or by transaction, you journal by spending category and set a monthly envelope for each. Income goes in, expenses come out, and the remaining balance is your real discretionary pool. This sounds basic until you realize most people don't actually know their discretionary income. They look at their bank balance and think they're fine. The category constraint reveals the gap immediately.
Theme two: the goal-debt pairing. Every financial goal gets paired with its corresponding cost of inaction. If you have a goal to save thirty thousand dollars for a down payment, you also track the opportunity cost of every dollar not going toward that goal. This is uncomfortable. It makes spending decisions visible in a way that standard budgeting apps never do.
Theme three: the lifestyle audit. This one takes more setup but pays off fast. You document your baseline monthly costs, then add lifestyle upgrades as separate line items. When you want to buy something expensive, you check whether it fits under an upgrade category or if it comes out of core living expenses. I had a client who wanted to buy a twelve-hundred-dollar standing desk. Under the lifestyle audit theme, he could see that his core expenses already ate ninety-two percent of his income. The desk would have pushed him into overdraft territory for three months straight. He bought it anyway but adjusted his grocery budget accordingly. That's the theme doing its job.
How to Set Up a Working System
Start with a simple spreadsheet or a notebook. Don't overthink the tool. The tool doesn't matter. The theme matters.
Pick one theme from above and commit to it for at least sixty days. Track every dollar that moves through your accounts. At the end of the first month, review the entries and identify which categories are eating your goal progress. Adjust the envelope amounts or the pairing ratios.
I once had someone using the goal-debt pairing theme who discovered that his student loan was costing him forty-three hundred dollars in lost compound growth over ten years compared to throwing that same payment at a rental property investment. He didn't switch to real estate. He just changed how he talked about the debt. Instead of "I owe this," it became "I'm paying forty-three hundred to keep this." The emotional weight shifted, and he started making extra payments without relying on willpower.
The counter-intuitive part is that journaling less often leads to better results. A twenty-minute weekly review beats a two-hour monthly catch-up. Weekly reviews catch problems before they compound. Monthly reviews let small issues snowball into full-blown discrepancies.
Here's where the method breaks down. It doesn't work well if your income is highly variable. Commission-based earners and seasonal workers need a different approach. I switch those people to the lifestyle audit theme but with a rolling twelve-month average instead of monthly envelopes. The average smooths out the spikes. You set your budget based on the lowest quarter you've seen in the past year, not the average. That way you're prepared for the dry months.
Another pitfall is tracking everything. People try to journal every coffee and every subscription. The signal-to-noise ratio becomes so bad that they stop reading the journal. Focus on the large items first. Transactions under fifty dollars can go in a general bucket unless you're actively trying to cut a specific habit.
What a Realistic Download Structure Looks Like
If you want a pre-built template to start with, here's what a functional download should contain:
A spreadsheet with three sheets. Sheet one is your daily or weekly transaction log. Sheet two is your theme-specific view. If you're using the category constraint, this sheet shows envelope balances. If you're using the goal-debt pairing, it shows goal progress alongside opportunity cost. Sheet three is your quarterly review template with prompts for adjusting the theme parameters.
Keep the transaction log simple. Date, amount, category, and a note field. That's four columns. Anything more and you'll stop filling it out.
The theme view should auto-calculate. No manual entry required beyond the raw data. If you're spending more time looking at the theme sheet than entering data, the setup is wrong.
The quarterly review template should have these prompts: which category consistently overruns? which goal has stalled and why? what lifestyle upgrades are justified versus impulsive? what adjustment do I make for the next quarter?
You can build this yourself in about twenty minutes or find free templates online. I've seen too many people pay forty dollars for a "finance journal" that amounts to a few blank spreadsheets with cute fonts. The value is in the structure, not the design.
One last thing. The theme you pick should match how your brain processes money. Some people are visual and need charts. Some people need narrative and write in paragraphs. A picture journal where you sketch each month's spending as a pie can work just as well as a spreadsheet. The medium is secondary. The consistency is what matters, and consistency comes from reducing friction, not increasing effort.
Gallery Finance Journal Themes For Goal Setting
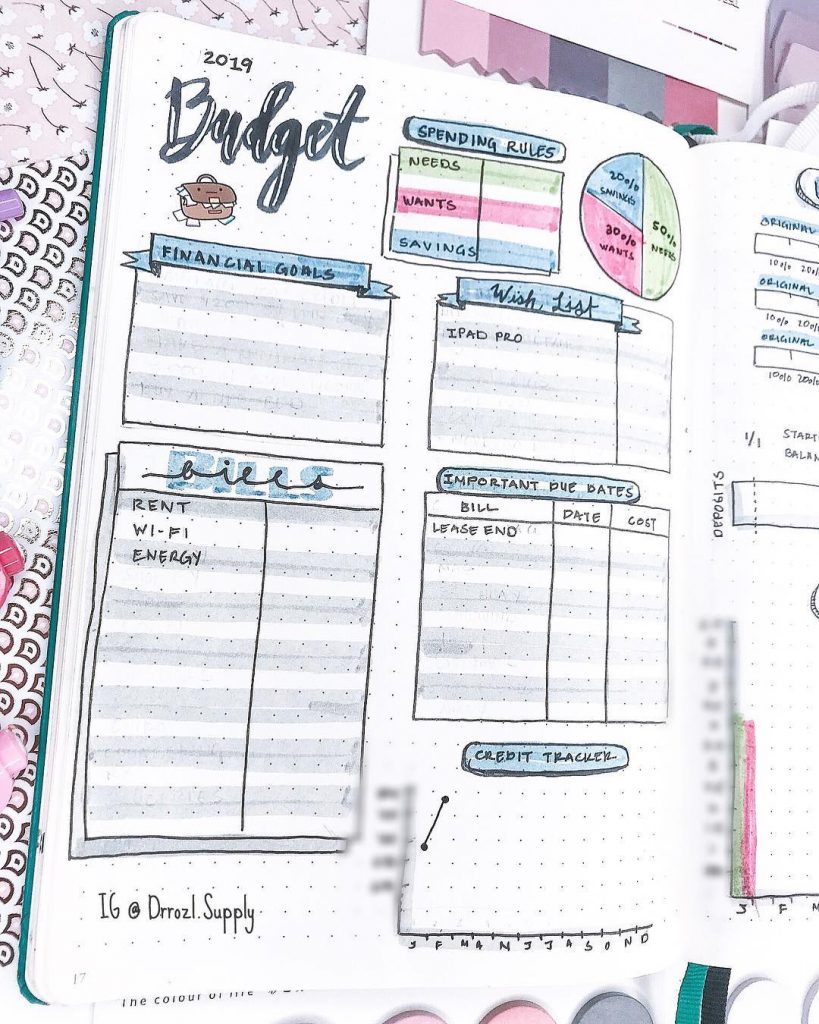
20 Creative Finance Tracking Bullet Journal Ideas - Craftsy Hacks
21 Finance Tracker & Budget Planner Bullet Journal Ideas You Need Now
16 Bullet Journal Ideas To Manage Your Finance - Live Better Lifestyle
Goal Journal Template, Smart Goals Worksheet, Routine Planner, Organisation Ideas Planners ...
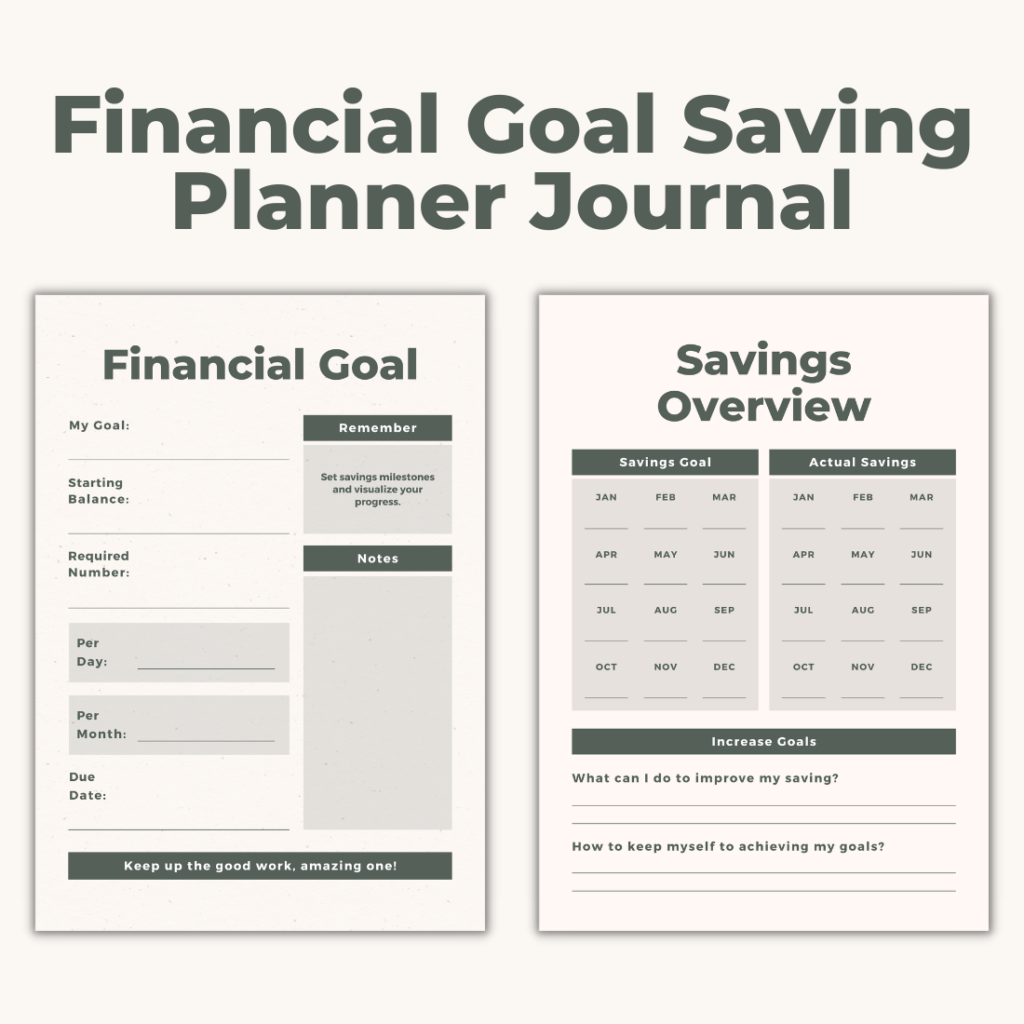
Financial Goal Saving Planner Journal Template - MasterBundles