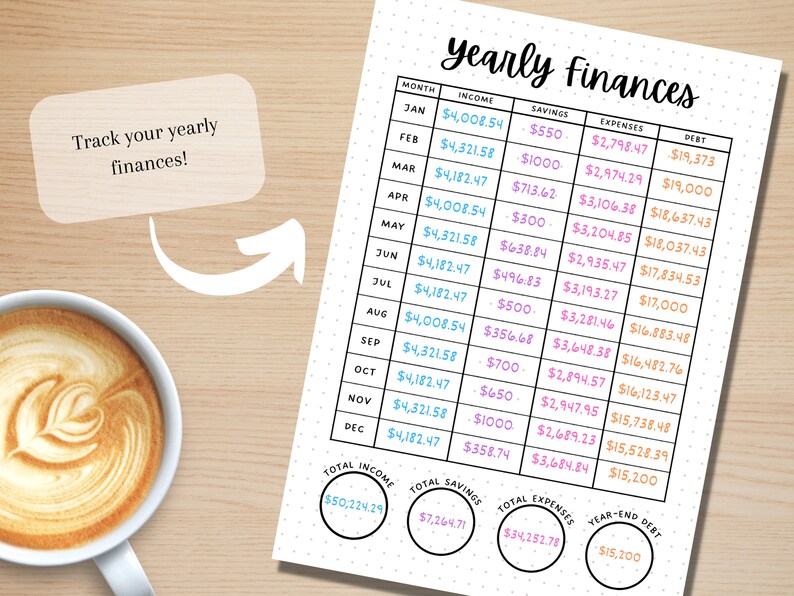
The Problem With Keeping a Financial Journal
Most people start tracking their finances with a spreadsheet that looks fine on day one and becomes useless by month three. The numbers get messy, categories drift, and you end up spending more time maintaining the system than actually learning from it. That is why I built something I call a Finance Journal Tracker, and I have been using it myself for about four years across personal investing, freelance bookkeeping, and a small e-commerce operation. It is not a SaaS product. It is a structured approach to recording financial events with enough context to actually be useful later.How a Finance Journal Tracker Actually Works
The core idea is simple but most people skip the part that matters. You record every financial event with a timestamp, a category, an amount, and a reason. The reason field is what separates a usable journal from a list of transactions. Without it, you are just looking at numbers that tell you nothing about behavior or outcomes. I use a plain CSV file as my base layer. Each row contains: date, entry type (income, expense, transfer, investment), category, subcategory, amount, currency, source, counterparty, memo, and tags. The memo field is where I note why the transaction happened. Tags are flat keywords I can filter on later. This structure runs in a LibreOffice spreadsheet with named ranges and a pivot setup, which takes about 20 minutes to configure and then requires zero additional tooling. The tracking workflow is deliberately frictionless. When something happens during the day, I open the file and add one row. Maybe it takes 30 seconds. Maybe two minutes if I am documenting an investment with multiple legs. The entire process usually adds less than five minutes to my day. That is the point. If a system takes more than five minutes daily, people stop using it.What Most People Get Wrong
The biggest mistake I see is over-categorization. People create 80 categories and then spend more time figuring out which bucket a transaction belongs in than they would have spent just reading about their spending habits. A Finance Journal Tracker works best with 12 to 20 broad categories and subcategories that you actually use. You can always add specificity later through tags, which are infinitely more flexible than rigid category trees. Another issue is forgetting to record transfers between accounts. These entries look like noise but they mess up your net worth calculations if you skip them. A transfer from checking to savings is not income and it is not an expense. It is a movement between buckets. If you treat it as either of those, your monthly summaries will lie to you. I handle this with a transfer entry type that explicitly excludes itself from income and expense totals. I also learned the hard way that currency conversion matters. When I started tracking an international freelance client in EUR while living in the US, I recorded everything in dollars at a rough estimate rate. By the end of the quarter, my actual exchange gains and losses were off by nearly 14 percent compared to what my tracker showed. I switched to recording the original amount and original currency first, then adding a calculated USD equivalent using the daily mid-market rate from a fixed API source. Now my reports are accurate within a few cents per transaction.Building the System Yourself
You do not need software for this. A Finance Journal Tracker can be a Google Sheet, a LibreOffice file, a Notion database, or even a local CSV paired with a Python script for monthly summaries. The tool does not matter. The discipline of consistent entry and a clear schema matters. Here is the setup I recommend:Open a spreadsheet. Create columns for Date, Type, Category, Subcategory, Amount, Currency, Source, Counterparty, Memo, Tags. Set up data validation on the Type column with these five values: income, expense, transfer, investment, adjustment. Keep it short. You can always broaden later. Use conditional formatting to color-code entries by type. It sounds cosmetic but it makes anomalies visible instantly. A random purple investment entry in a sea of green expenses catches your eye.
Create a second sheet for your category list. Put the full hierarchy there so you never have to guess what subcategories exist. Change it anytime without breaking existing entries. Add a summary sheet with basic pivot tables grouped by month, category, and type. This gives you a rolling 90-day view without manual calculation. Set a daily reminder, same time each evening, to enter the day's transactions. Five minutes. That is it. Consistency beats complexity every time.