How mortgage calculators actually work under the hood
A mortgage calculator is a simple piece of software that takes your loan amount, interest rate, and term length and spits out a monthly payment using the standard amortization formula. That's it. Most online versions you'll find are just basic implementations of the same formula bankers have used since the 1970s: M = P * [r(1+r)^n] / [(1+r)^n - 1]. P is the principal, r is your monthly interest rate, and n is the total number of payments. What most people don't realize is that this formula only gives you principal and interest. It does not include taxes, insurance, HOA fees, PMI, or any of the other line items that actually show up on your monthly statement. I've seen borrowers get blindsided multiple times because they assumed the calculator number was their total payment when it was literally half of it. A calculator showing $1,800 per month doesn't mean your check to the bank is $1,800. It means $1,800 goes toward the loan itself. Add property tax, homeowners insurance, and possibly private mortgage insurance and you're looking at $2,200 or more depending on your location.
What to look for in a Finance Mortgage Calculator
The calculators that are actually useful separate principal and interest from escrow components. You want one where you can enter property tax rate and annual insurance cost as inputs, not just guess at them later. The best ones also let you toggle between fixed and adjustable rates, include extra payment fields, and generate a full amortization schedule you can export. If you're evaluating multiple properties or trying to understand the impact of a down payment change, the right tool will let you adjust one variable and immediately see how it cascades through your monthly payment and total interest paid over the life of the loan. That's where most free online calculators fall apart. They show you a single static number and stop there. Not useful when you're comparing a 30-year fixed against a 15-year, or trying to figure out whether putting 20% down versus 15% saves enough on PMI to justify the extra cash upfront. Here's something most guides won't tell you: the interest rate alone is not the most important number in your decision. The annual percentage rate, or APR, is far more meaningful because it factors in origination fees, discount points, and other closing costs rolled into the loan terms. Two loans with identical stated rates can have very different APRs if one lender charges higher fees. I worked through a scenario recently where two lenders quoted the same 6.5% rate, but one had an APR of 6.72% and the other 7.01%. Over a 30-year loan on $400,000, that 0.29% APR difference translated to roughly $3,200 in extra interest cost. The lower rate lender was actually the more expensive loan once you looked past the headline number.
Another thing nobody bothers explaining: your monthly payment doesn't stay constant in real life even with a fixed-rate mortgage. Property taxes increase, insurance premiums go up, and if you started with less than 20% down, your PMI payment drops off at a certain point but only if you request its removal or hit the automatic cancellation threshold. A good Finance Mortgage Calculator will let you model those changes over time, not just give you a single snapshot. Most don't, which is why the numbers look more stable than they actually are. When I was dealing with a client who wanted to model a refinance scenario, we hit a wall with every standard calculator on the market. They couldn't handle the edge case where the borrower was switching from an ARM to a fixed loan while also changing the loan term and adding cash-out equity at the same time. The calculator would either error out or silently use incorrect assumptions and give a misleading payment estimate. What worked was taking the loan details into a spreadsheet, building the amortization manually using the PMT function in Excel, and then layering in the escrow estimates based on local tax rates and insurance quotes. It took about twenty minutes to set up correctly, but it gave us a result we could actually trust. The key insight there was that no pre-built calculator covered all the variables simultaneously, so the tool had to be flexible enough to let you adjust each component independently. There's also the question of how calculators handle down payment thresholds. The 20% rule is not a law, it's a convention tied to PMI cancellation. Some loans like FHA require mortgage insurance regardless of down payment size. VA and USDA loans don't require it at all. If your calculator doesn't account for loan type variations in its PMI logic, the output is wrong for any non-conventional loan. I've lost track of how many people I've seen get advice from a calculator that assumed conforming loan rules when they were actually looking at an FHA product.
Get the Full Details
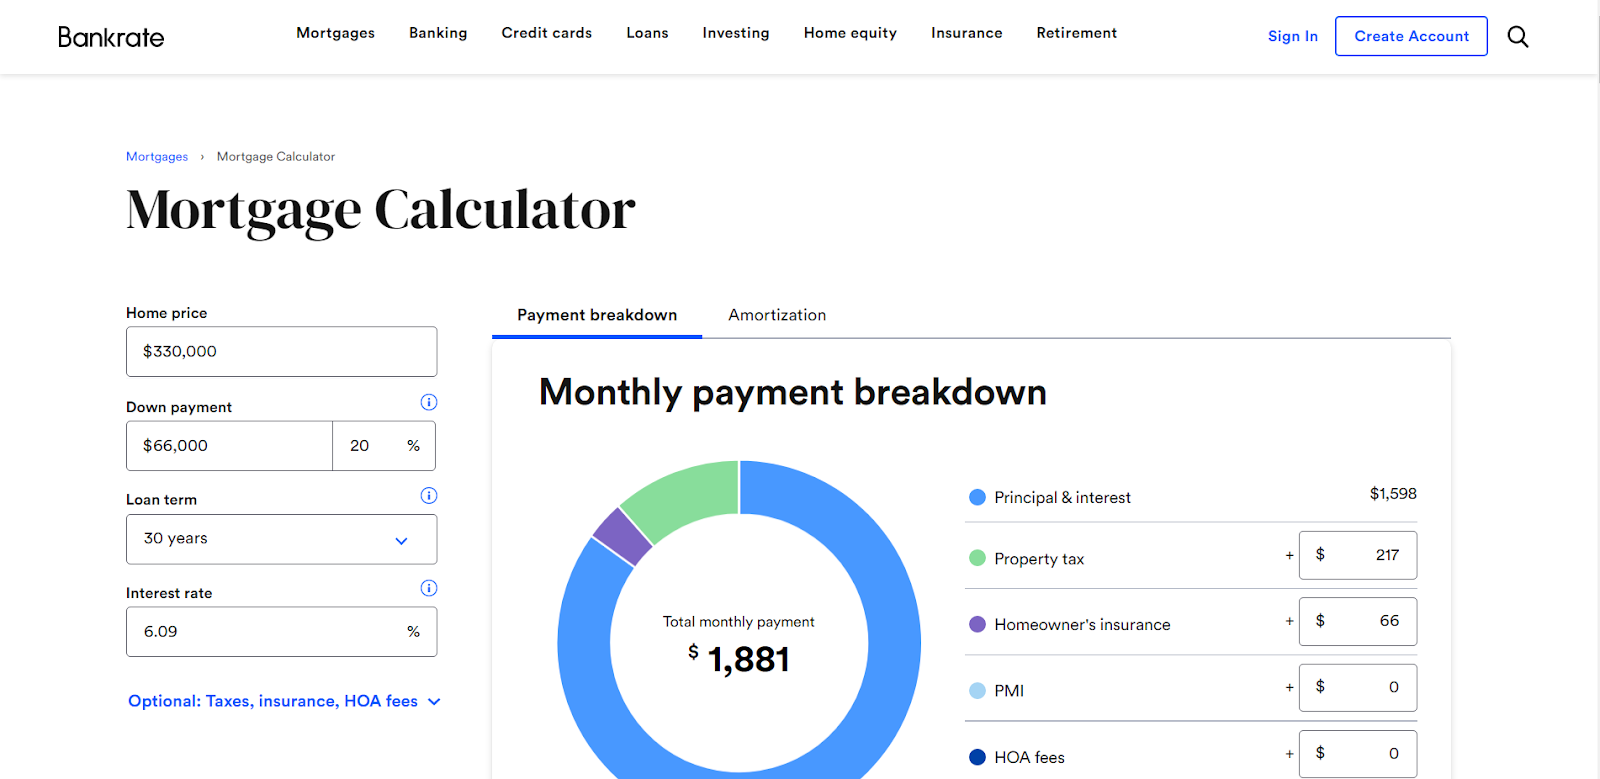
The other limitation worth being honest about is that calculators cannot predict your actual qualifying payment. Underwriting looks at debt-to-income ratios, credit score, employment history, reserve requirements, and a dozen other factors that have nothing to do with the math. A calculator might tell you your payment is $2,100 per month, but if your DTI pushes you above 43% with other debts included, you may not qualify for that loan amount at all. The calculator is a planning tool, not a pre-approval. I've seen buyers get emotionally attached to a house based purely on a calculator number and then get rejected because the lender's underwriting guidelines were stricter than the algorithm's assumptions. If you want something practical, start by building or finding a calculator that lets you input property tax as a percentage of home value, annual insurance cost, HOA monthly fee, and PMI rate as separate line items. Run your numbers with and without extra payments to see the real impact on total interest. Then take those results to a lender and compare the actual Loan Estimate document against your calculator output. If they're off by more than a few percent, your calculator is missing something or using the wrong assumptions. That's usually where you learn what the lender's specific pricing includes versus what the generic tool omitted.