Building a Finance Planner That Actually Works
The first time I tried to set up a personal budgeting system, I used a spreadsheet with twenty columns and conditional formatting that turned red every time I missed a category. It took me four hours to build and three weeks before I stopped using it. The problem wasn't the tool, it was that I was designing for the version of myself who had energy and discipline after work. That version of me doesn't exist. What I ended up doing instead was simpler than anything I'd read in any tutorial, and it took about twenty minutes to implement. I built a Finance Planner as a bare-bones tracking sheet with just five fields: date, description, amount, category, and running balance. That's it. No data validation, no dropdowns, no macros. Just rows and a subtraction formula. The trick that actually made it stick was something nobody talks about in personal finance guides. I set the sheet to open automatically when my computer boots, and I committed to entering transactions the moment I got home from work, not at the end of the month. The friction of context switching is a lot more damaging to consistency than people admit. When you switch from work mode to "figuring out where your money went" mode, you tend to skip it. Making it the first thing you do when you walk through the door removes that decision point entirely.
How I Structure My Finance Planner
Here's what my current setup looks like. The categories are fixed at fifteen, not fifty. I found that going beyond fifteen categories causes decision paralysis when you're trying to log something in thirty seconds. Things like "dining out," "groceries," "transport," "utilities," "entertainment," "healthcare," "shopping," "subscriptions," "education," "gifts," "investment contributions," "debt payments," "home costs," "personal care," and "miscellaneous." If something doesn't fit, it goes in miscellaneous and I review it at the end of the month to see if a new category is warranted. The running balance column is probably the most important part, and also the part most people skip. I keep a separate sheet tab for my starting balance and monthly income, then the main tracker subtracts expenses from that. At any point I can see exactly where I stand without doing mental math. This caught me once when I thought I was spending normally but the running balance showed I was actually $400 over my intended monthly cap because I'd mis-categorized a large purchase as "shopping" instead of "home costs." The category didn't matter to the total, but it mattered for seeing which area was actually inflating. I use Google Sheets because it syncs across devices, but the same approach works in any spreadsheet or even a properly structured notebook if you prefer paper. The platform doesn't matter. The daily entry habit matters.
Common Pitfalls That Break Most Budgeting Attempts
The biggest mistake I see people make is setting budgets for every single category before they have a month of actual data. You can't reasonably budget for groceries if you've never tracked how much you actually spend on groceries. That's not a budget, it's a guess wearing a suit. Track for at least thirty days first, then set targets based on real numbers. Another one: people treat their Finance Planner like a punishment tool. They feel guilty when they overshoot a category, and that guilt makes them avoid opening the sheet, which makes them overshoot more, which creates a negative feedback loop. The sheet should be a neutral tracking mechanism, not a moral judgment device. Overspending on entertainment this month doesn't make you a bad person. It makes you a person with data. Use the data next month. I also used to try to reconcile my bank statement every single day. This was a mistake. Daily reconciliation takes about twelve minutes per session, and I was burning through forty-eight minutes a week on something that doesn't need that level of scrutiny. Switching to weekly reconciliation cut that to about twelve minutes total and caught the same errors. The only time I do daily reconciliation is when I suspect a duplicate charge or unauthorized transaction, which is rare.
Get the Full Details
There's also the problem of cash expenses. If you pay for things in cash and don't log them, your planner will consistently show a higher balance than your actual bank account. I solved this by keeping a small envelope labeled "cash" at home. Every time I pull cash out, I log it immediately as a transfer, not an expense. The money still exists, it just moved from my wallet to my pocket. The category stays accurate.
Advanced Usage: Rolling Averages and Variance Tracking
Once you have three months of consistent data, you can start doing things that are actually useful instead of just recording history. I calculate a rolling three-month average for each category and flag anything that deviates more than two standard deviations from that average. This catches genuine anomalies — a $200 electricity bill when your average is $85 — without getting triggered by normal month-to-month variation. The formula I use is straightforward. For any given category, take the last nine entries (three months of roughly three entries per month), calculate the mean and standard deviation, then color-code anything outside mean plus or minus two standard deviations. Yellow for one to two standard deviations, red for more than two. This took me about ten minutes to set up with basic spreadsheet functions and has saved me from surprise budget shortfalls multiple times. Here's a counter-intuitive insight: your irregular expenses are actually more predictable than you think if you track them long enough. I had a $1,200 annual insurance payment that felt like a random blowout every time it hit. After tracking it for two years, I realized it always came due between March 15 and April 5. I started setting aside $100 in March and $200 in April automatically, which turned a shocking annual expense into a planned quarterly one. The money wasn't gone faster, I just stopped being surprised by it.
When a Finance Planner Isn't the Right Tool
I need to be honest about the limitations. A spreadsheet-based Finance Planner does not work well if your income is highly variable — gig work, commission sales, seasonal employment. The whole framework assumes a relatively stable income baseline against which expenses can be measured. If your monthly income swings between $2,000 and $6,000, traditional budgeting categories become almost meaningless because your baseline keeps shifting. In that scenario, a percentage-based approach works better. Instead of setting fixed dollar limits for categories, I recommend allocating percentages of whatever your income is that month. Seventy percent to essentials, twenty percent to savings and debt, ten percent to discretionary. When income drops, everything scales down proportionally instead of you feeling like you're failing your budget. Another scenario where this breaks down: people with multiple income streams and complex investment accounts. If you're managing rental properties, a side business, and a diversified portfolio simultaneously, a simple expense tracker becomes a fraction of the picture. You'd be better served by a full accounting system or working with a CPA who can tie your financial planning to your actual tax situation. A Finance Planner won't handle depreciation schedules or cost basis tracking.
The tool also doesn't address behavioral spending issues. If you have a compulsive spending problem, tracking your expenses in a spreadsheet isn't going to fix it. It's like keeping a log of how many cigarettes you smoke without actually trying to quit. It provides data, but the data alone doesn't change the behavior. Professional support or structured programs are the appropriate intervention there, not a better spreadsheet.
Getting Started in Practice
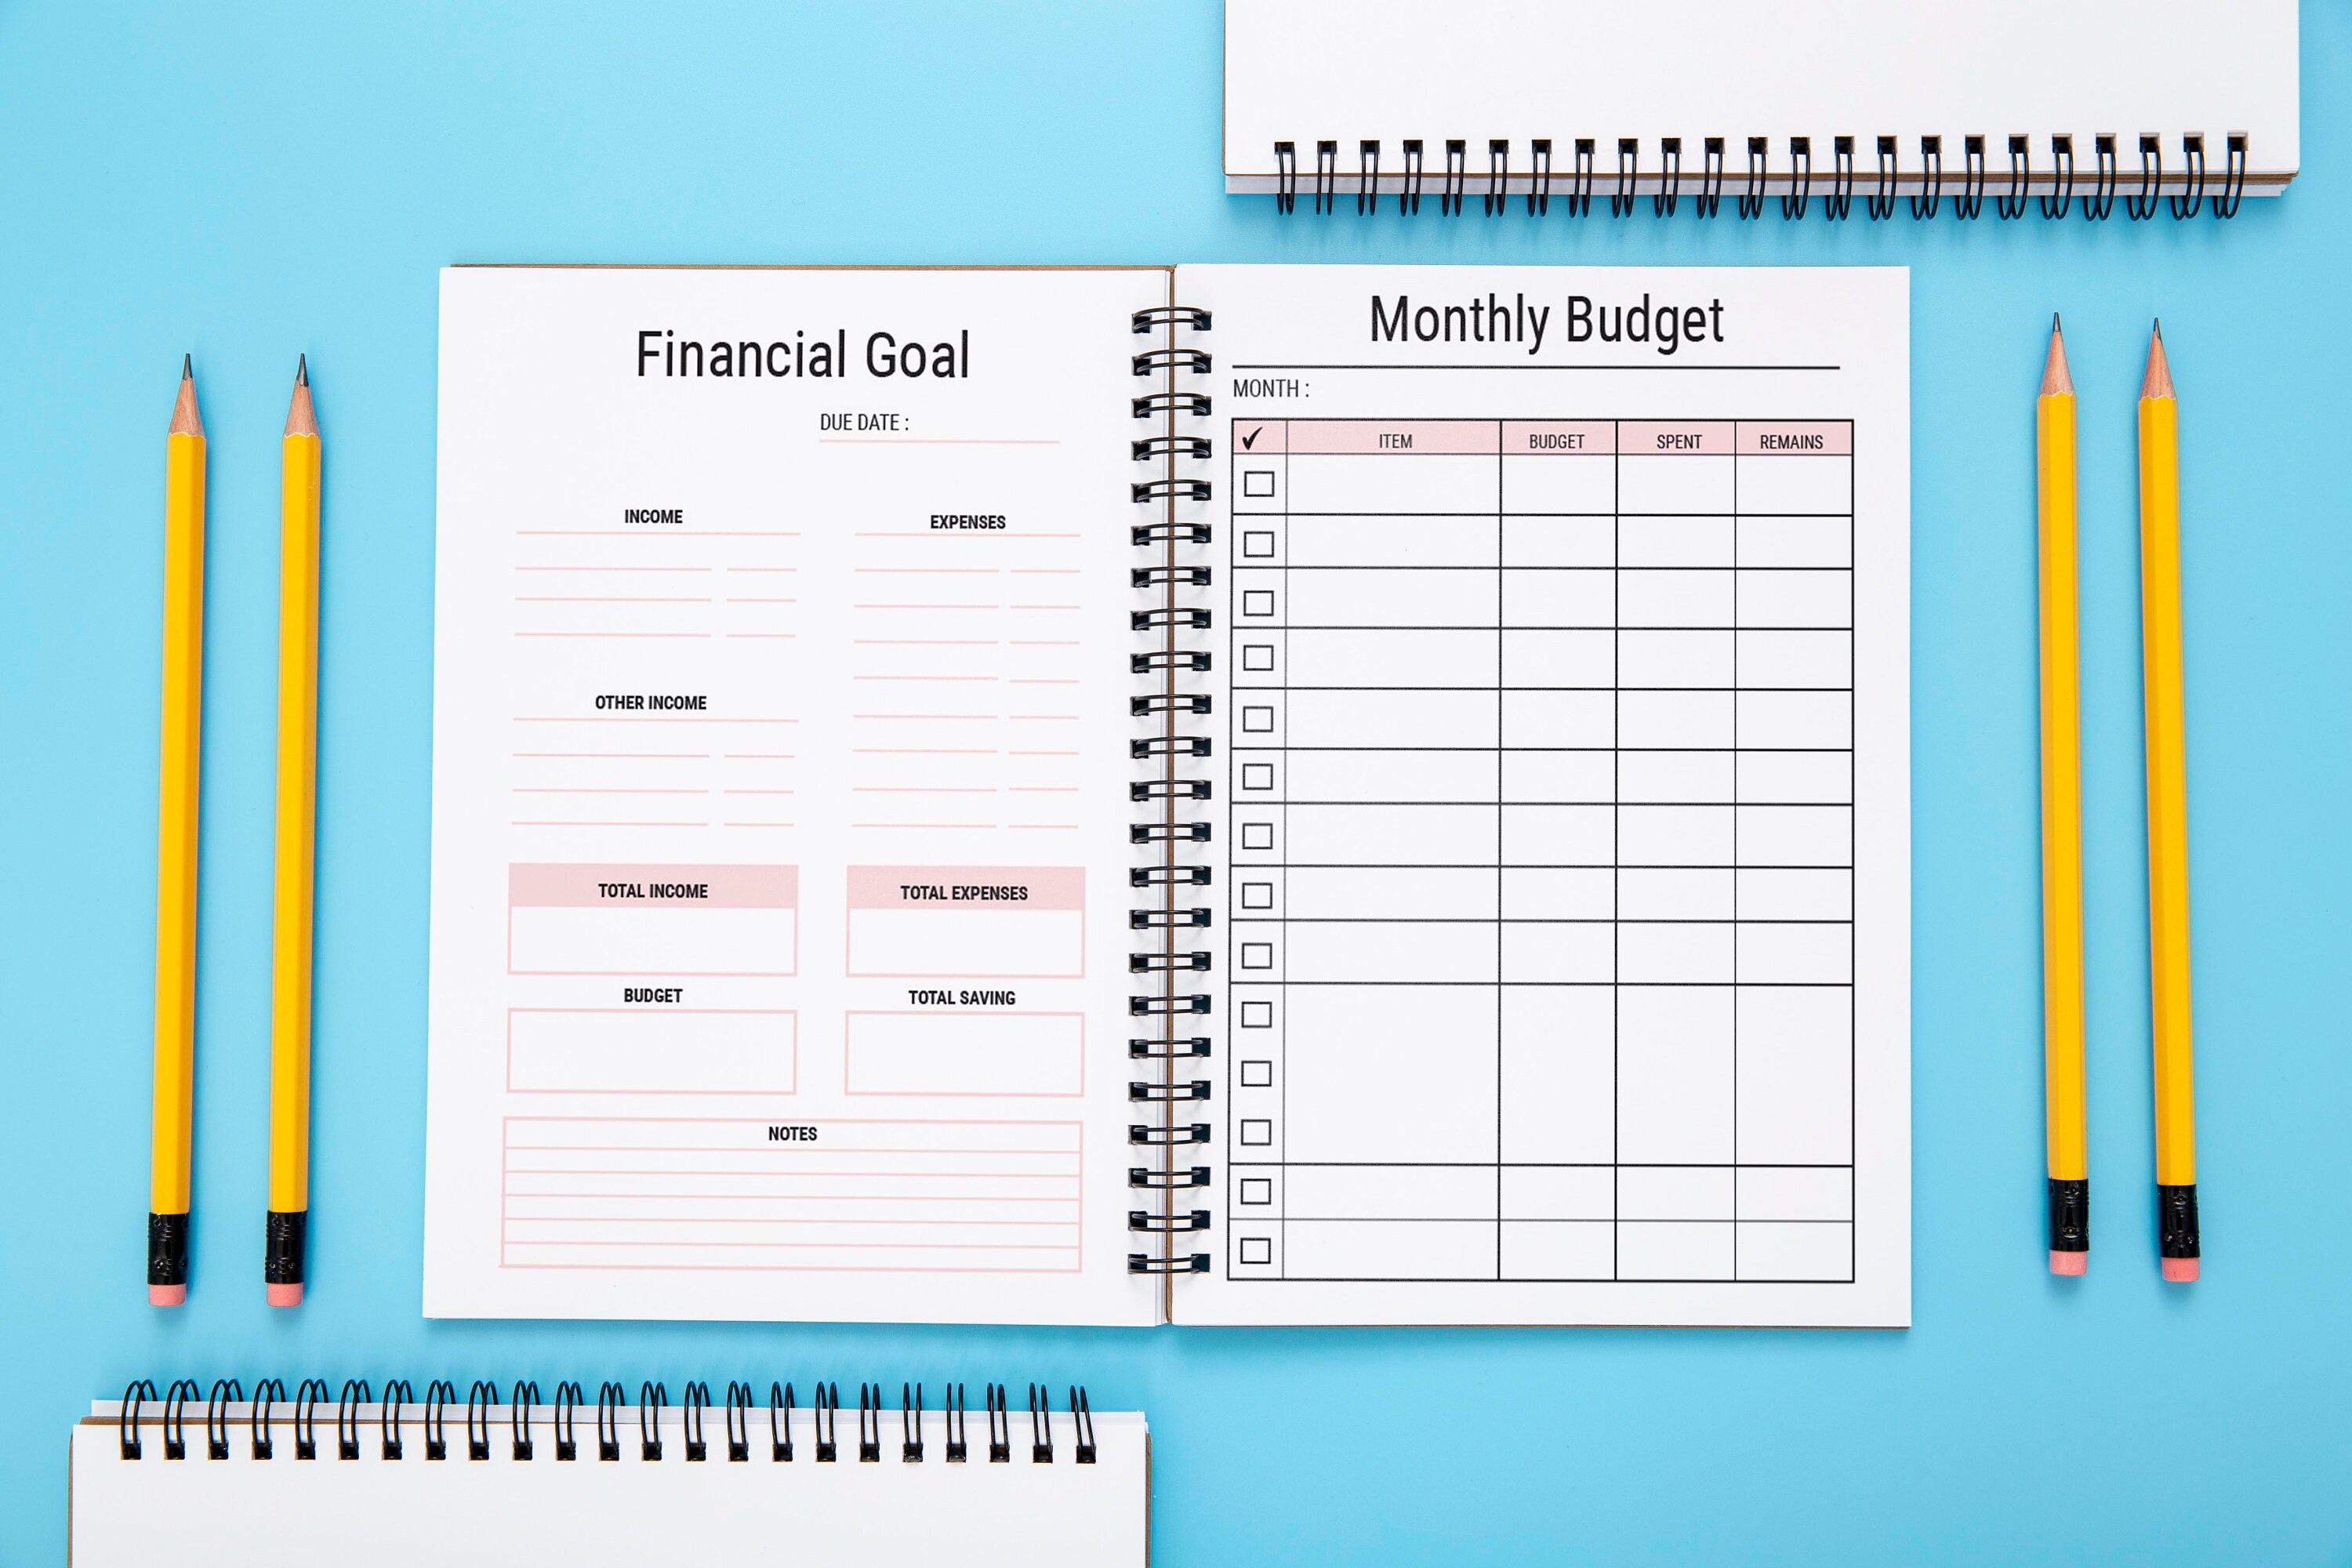
If you want to build this yourself, open a new spreadsheet. Create five columns: Date, Description, Amount, Category, Running Balance. Set the Running Balance formula as the previous row's balance minus today's expense, or equivalently, the starting balance plus all income minus all expenses up to that row. Format the Amount column as currency. That's your entire Finance Planner for the first month. Add a second sheet for monthly summaries. Group your transactions by category, sum them up, and compare against your targets if you've set any. Do this once a week, not once a day. The weekly review takes about eight minutes and gives you enough visibility without becoming a chore. I've been using this approach for about four years now. It's not glamorous, it doesn't have automation or AI integrations, and it won't make you rich on its own. But it consistently catches spending drift before it becomes a crisis, and it gives me enough visibility into my financial patterns that I can make informed decisions about where to allocate resources. That's the actual value proposition. Not perfection, just enough clarity to stop flying blind.