What Actually Happens When You Try to Apply Finance Step By Step
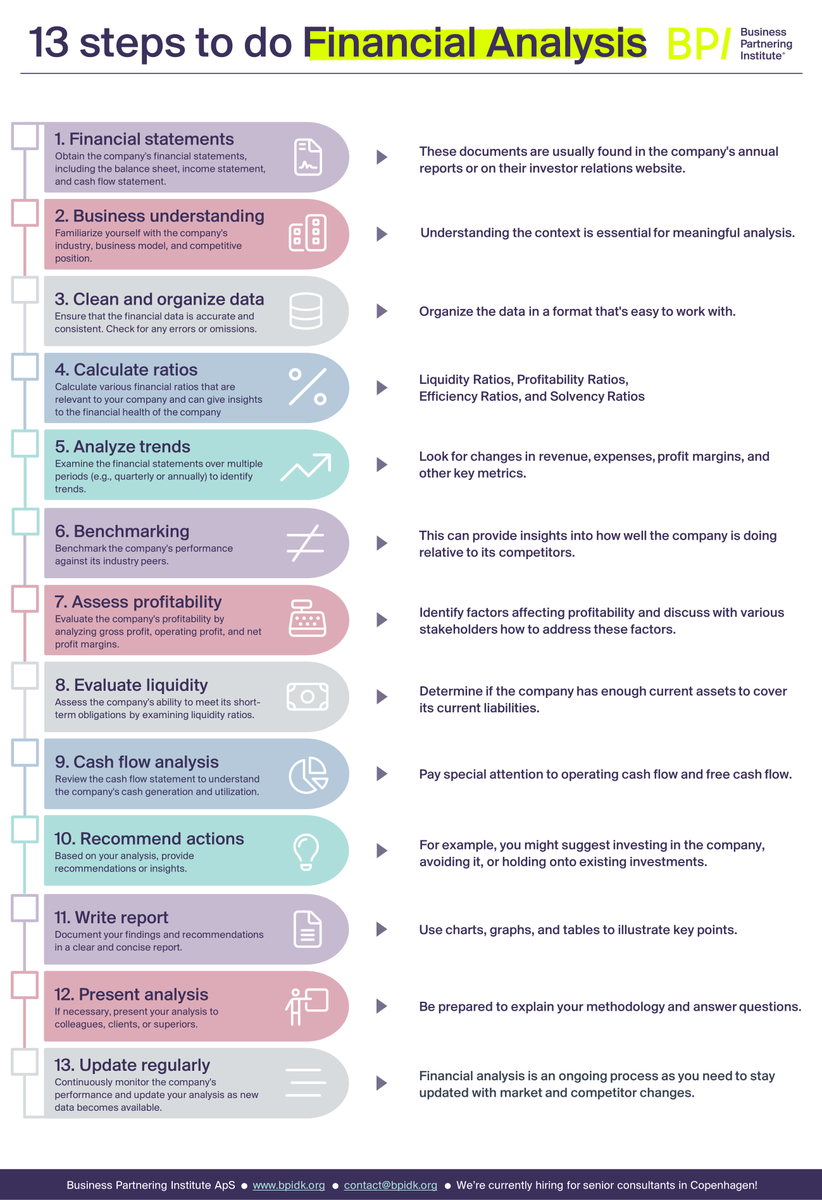
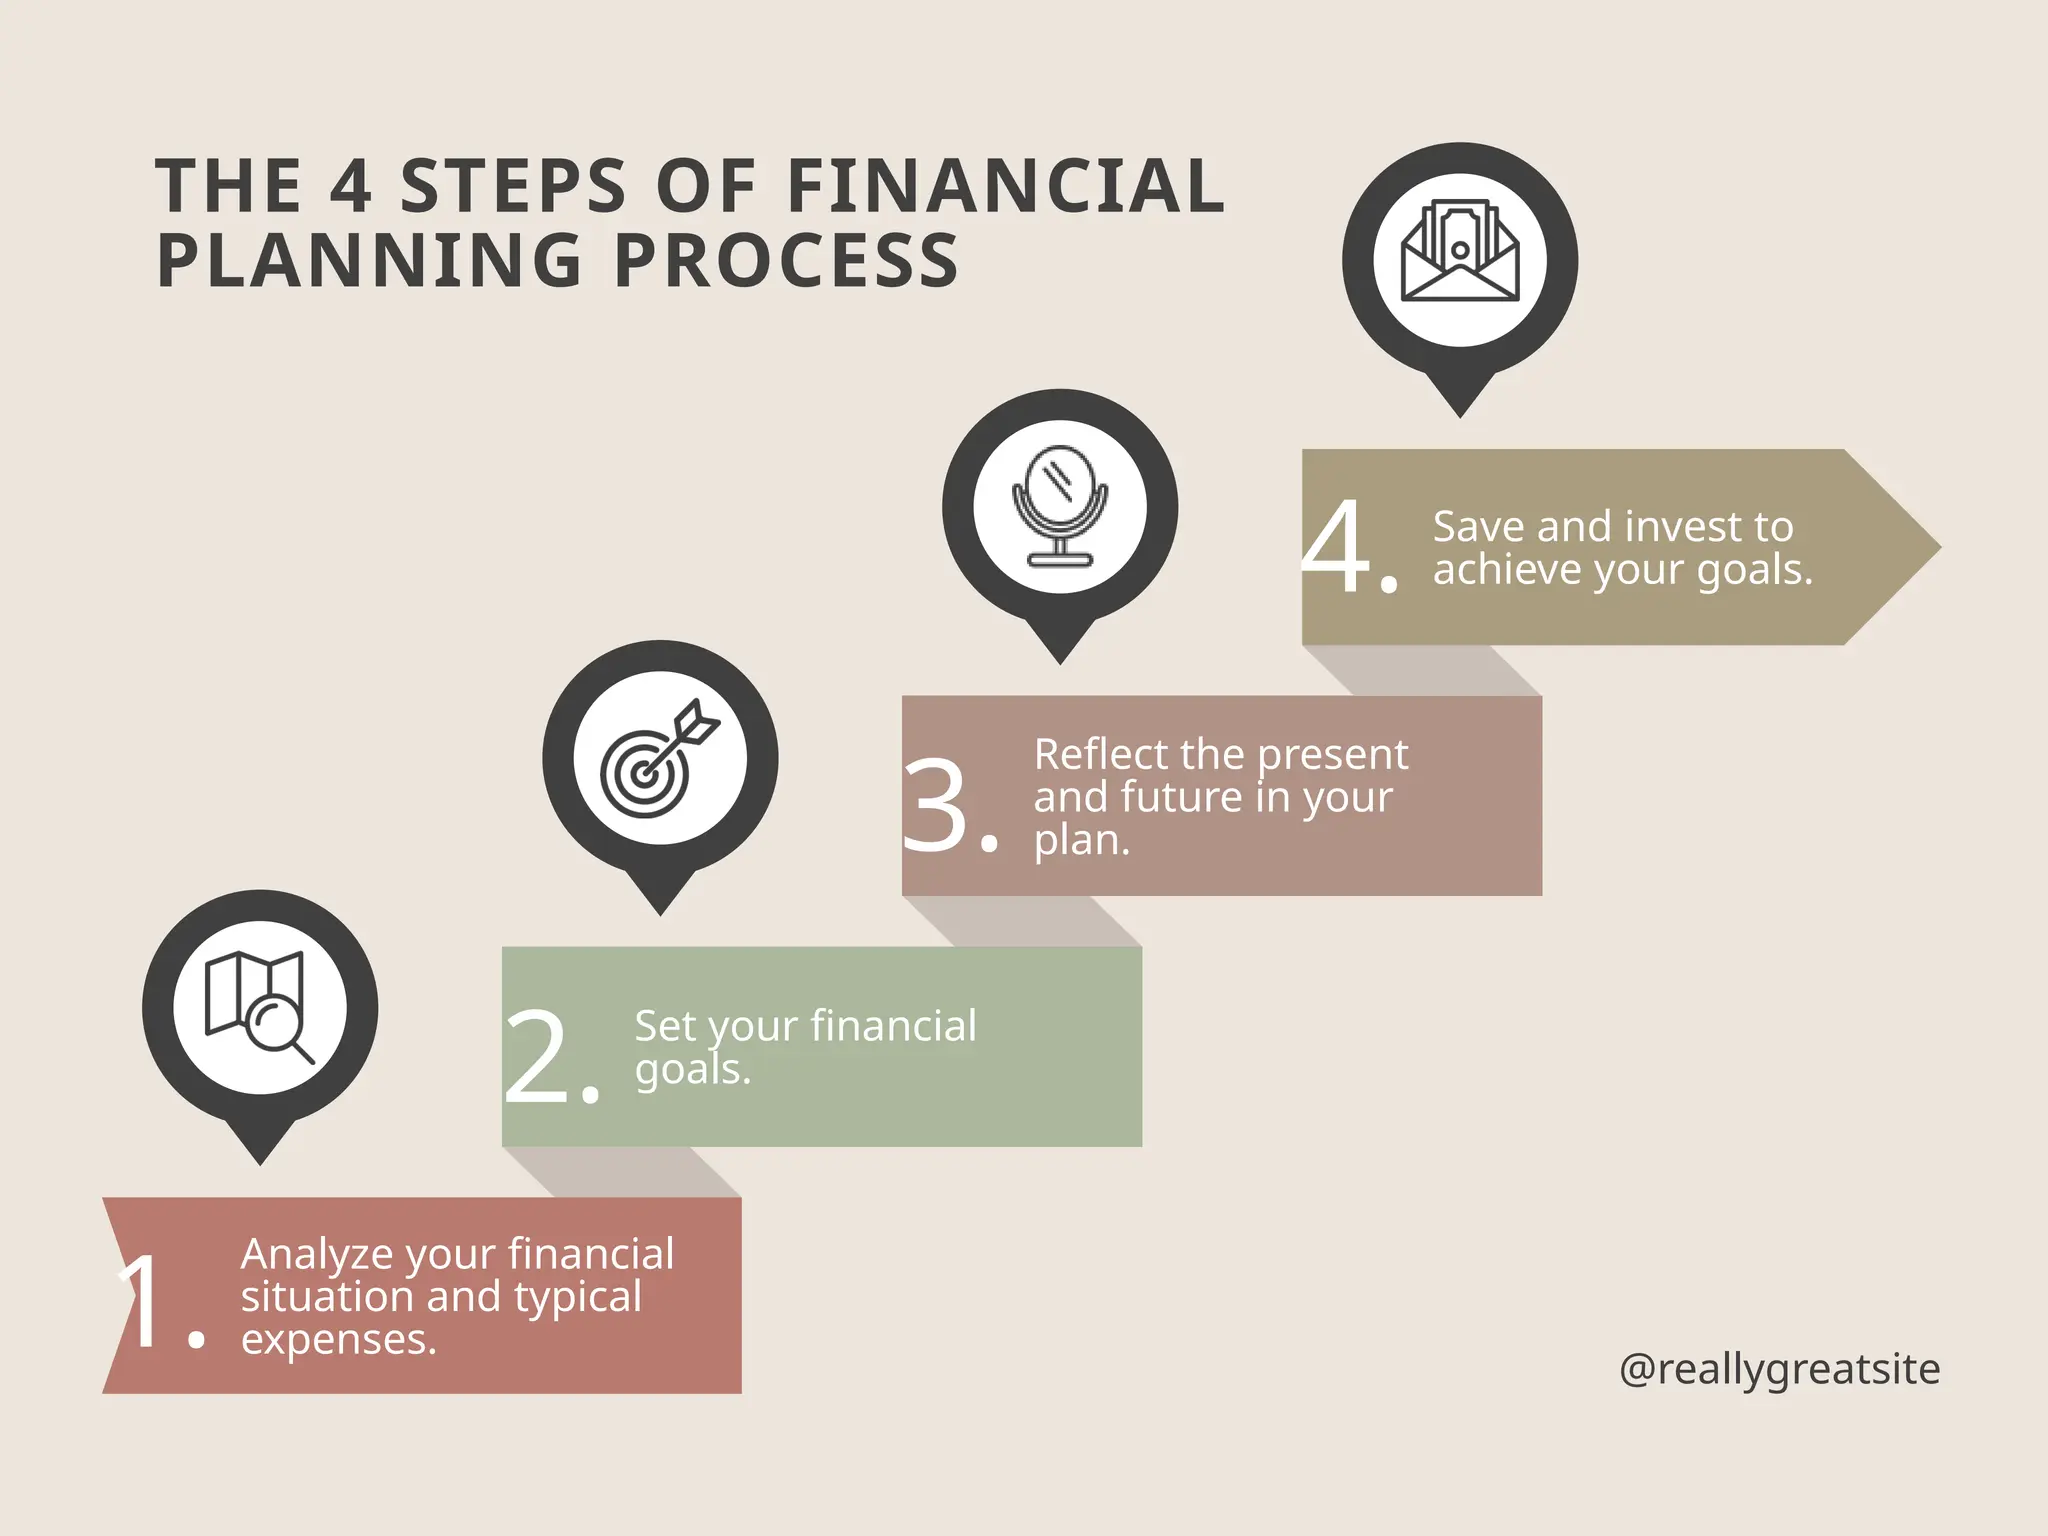
Most people approach personal finance like they are following a recipe, measuring ingredients and hoping the result comes out right. The reality is messier. The Finance Step By Step method works because it forces you to confront the actual numbers in your life instead of pretending they will fix themselves. I have watched people try to automate their way out of bad habits, and it rarely ends well. Here is how it actually works when you stop treating it like a motivational video and start treating it like something closer to mechanical work.
Starting With Finance Step By Step Without Losing Your Mind
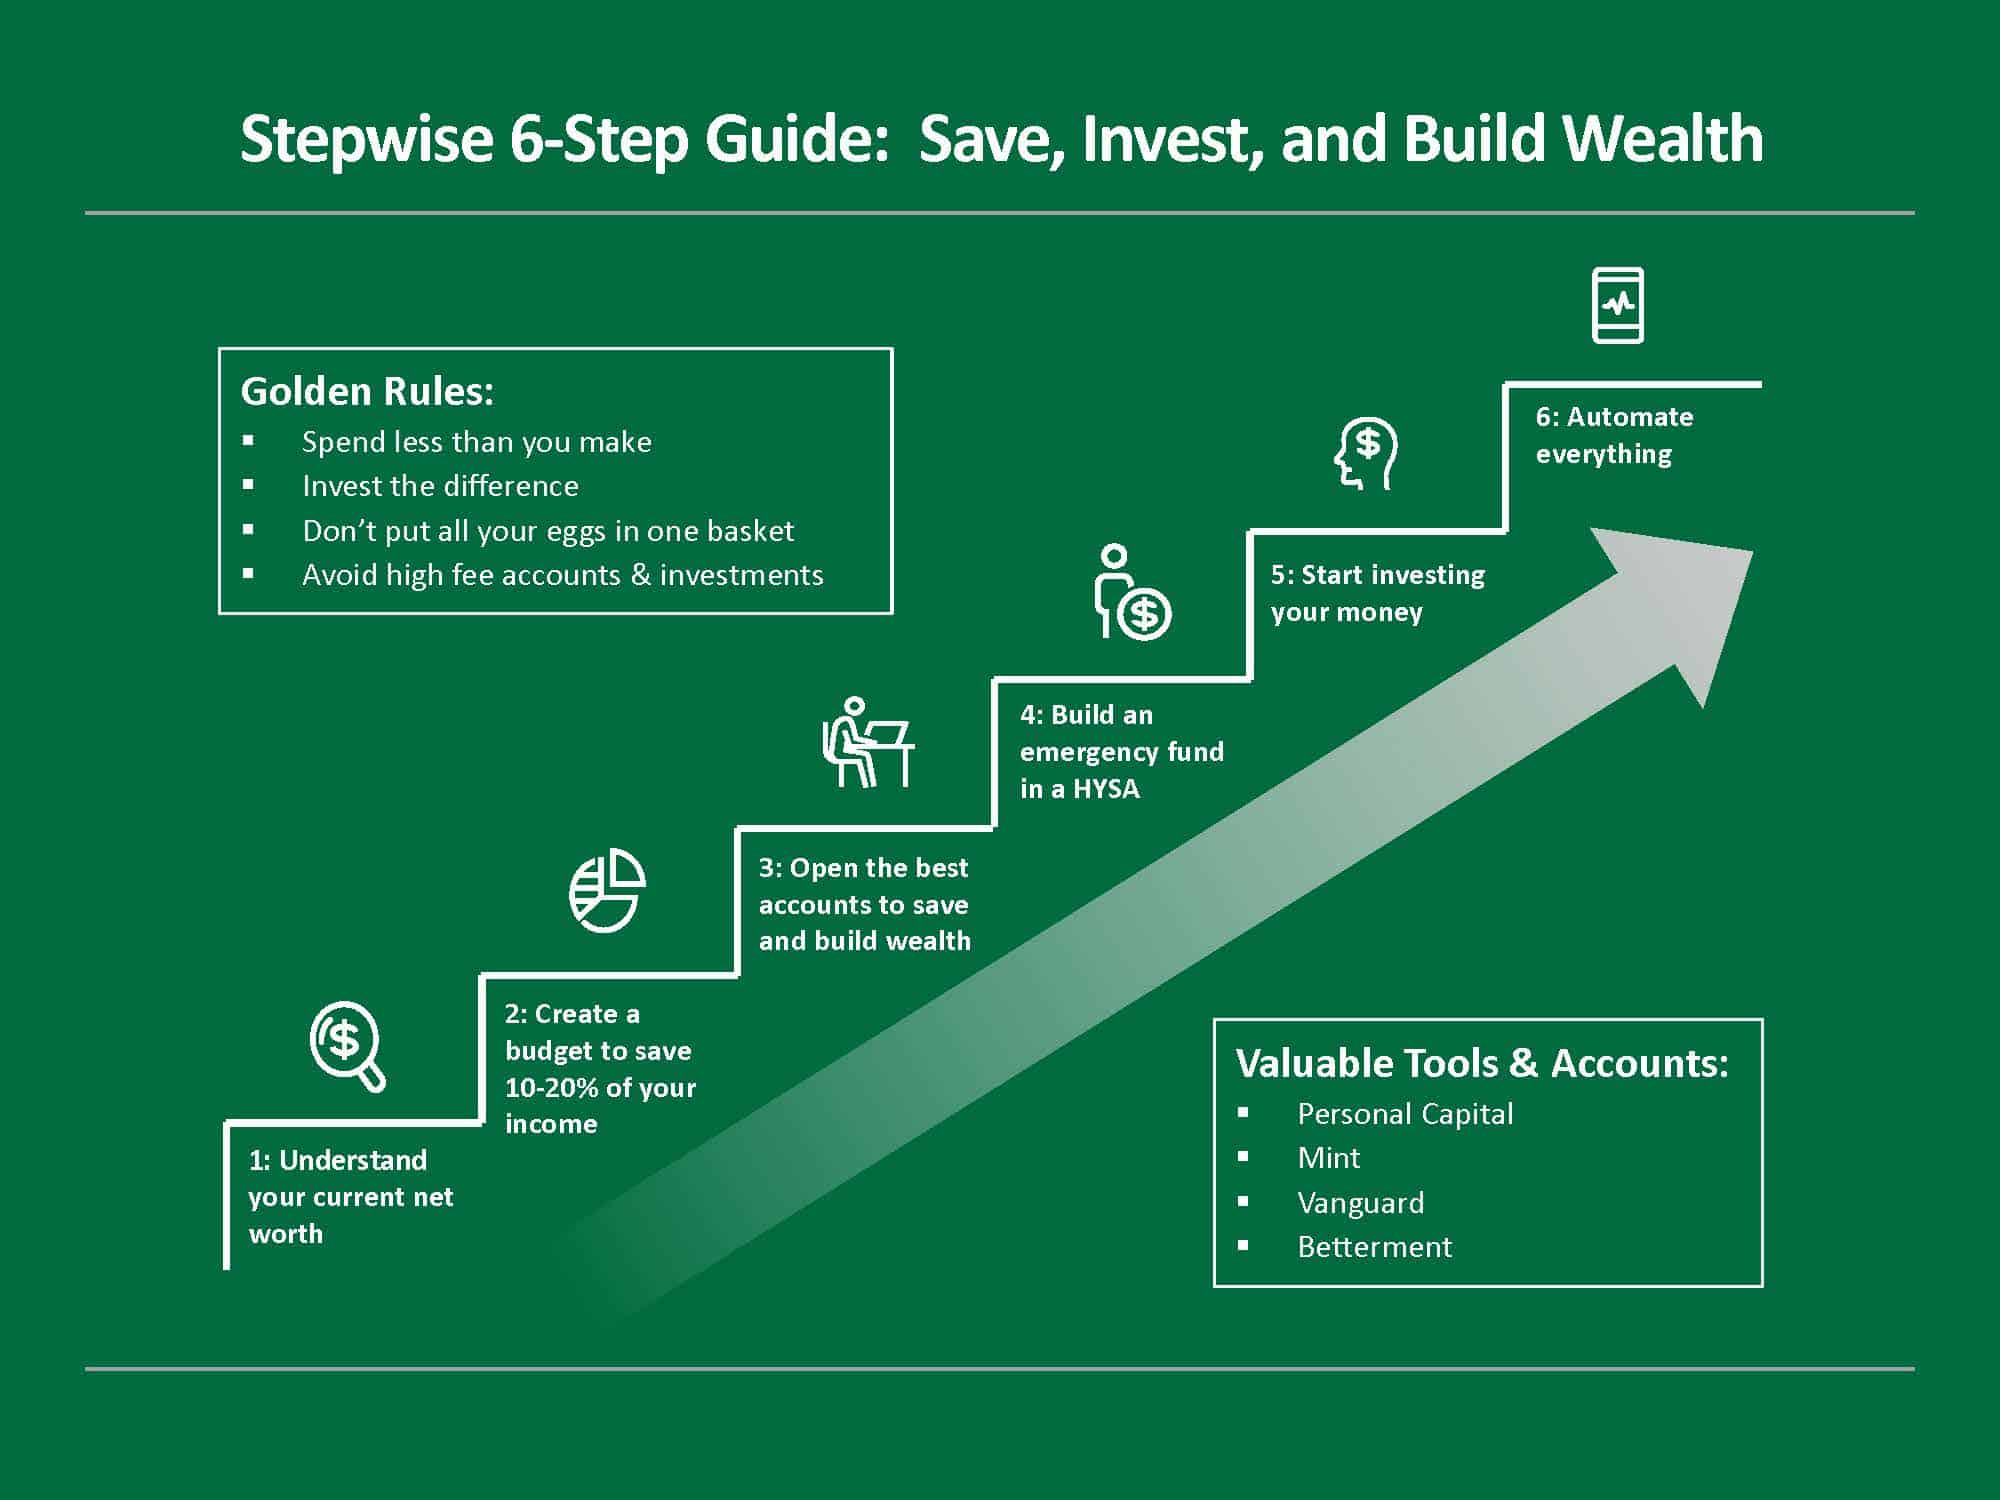
The first step is always gathering every financial account into one view. This sounds obvious, but most people skip it or do it halfway. I had a client once who used four different banks, two credit cards, and a retirement account he had not logged into since 2019. He thought his total debt was about eighteen thousand dollars. It was thirty-two. Not a dramatic difference, but enough to change the entire strategy. I spent two hours on the phone with customer service because the accounts were registered under different names after a marriage. You would not believe how many institutions refuse to help you without the exact same name on file. I ended up using a combination of PDF statements and manual entry in a spreadsheet because the aggregation tools all failed on his accounts. The workaround was simply batching the login sessions and noting which accounts refused to sync, then doing those manually until the data was complete. Once you actually know the numbers, the second step is categorizing every expense from the last ninety days. Not the last month. Not what your app says it categorized for you. Your actual bank statements. Apps misclassify things constantly. They put a grocery store purchase into "entertainment" if you bought snacks while browsing. They call a pharmacy trip "healthcare" when it was mostly over-the-counter medicine that was not even prescribed. I track my own expenses this way every quarter and reset my categorization rules. It takes about forty-five minutes and prevents at least three hundred dollars a month in miscategorization errors that silently erode your budget accuracy.
The Budgeting Phase Most People Do Wrong
After you have the data, you build a zero-based budget. Every dollar has a job. If your income is four thousand dollars, you assign every single dollar to a category until you reach zero. The leftover is not "spare." It either goes somewhere or you admit you overestimated your income. This is where most people quit because the math is less forgiving than they expected. Here is a thing that almost no beginner guide mentions. Your budget needs a category called "shock absorber." This is a line item for unexpected expenses that you pre-fund monthly. Most people call this an emergency fund, but an emergency fund is for actual disasters. A shock absorber covers things like your car needing new tires, a medical co-pay you did not expect, or a gift you owe for a wedding. I suggest five hundred dollars per month into a separate high-yield account. When it reaches two thousand, you reduce it to three hundred. When it drops below one thousand, you pump it back to five hundred. This smooths out the volatility that breaks most zero-based budgets. Another nuance: use a two-account system, not a spreadsheet. Spreadsheets are for analysis. Checking and savings accounts are for behavior. Money physically moving between accounts creates friction that stops impulsive spending. When I was younger, I could type a transfer into a spreadsheet and pretend the money existed. Moving it through an actual bank interface took enough effort that I stopped making purchases on impulse. The friction itself was the tool.
Get the Full Details
Debt Strategy: The Counter-Intuitive Part
Everyone knows the avalanche method and the snowball method. They are not opposites. They are different tools for different psychological profiles. The avalanche method pays minimums on everything and throws extra money at the highest interest rate. It saves the most money mathematically. The snowball method targets the smallest balance first and builds momentum. It saves the most sanity. I recommend something neither method does well. If you have a debt under five thousand dollars with an interest rate below seven percent, I sometimes suggest paying it off aggressively even if it is not the smallest or the highest rate. Here is why. A debt under five thousand is small enough to eliminate quickly. An interest rate below seven percent means you are not bleeding terribly fast. Getting rid of a whole obligation reduces cognitive load. That mental space lets you focus on bigger problems. Most people never consider this middle ground because the textbooks only teach the two extremes. The problem with the avalanche method is that it ignores behavioral psychology entirely. A person making minimum payments on a fifty-thousand-dollar mortgage while also having a two-thousand-dollar credit card at twenty-four percent interest will likely feel more stress than the reverse scenario. Paying off the small high-interest debt first can free up mental bandwidth even if it costs an extra three hundred dollars in interest over the life of the loans. Three hundred dollars is a lot. It is also cheaper than a therapist for some people.
Investing: Where The Finance Step By Step Method Gets Messy
Once your high-interest debt is gone and your shock absorber is funded, the next step is investing. This is where most people abandon the method because investing is complicated and nobody teaches it in a simple way. Start with the order of operations that actually matters. I am going to list this in a different order than most guides because the sequence is more important than the individual steps. First, contribute to your employer match. This is free money and skipping it is mathematically stupid. Second, max out a Roth IRA if your income qualifies. Third, go back to your employer plan and increase contributions until you hit the annual limit. Fourth, consider a taxable brokerage account if you still have cash to invest. The reason I put the Roth IRA before additional employer plan contributions is that Roth withdrawals are tax-free. In a taxable account, you pay capital gains. In a traditional employer plan, you pay ordinary income tax on withdrawal. The Roth is the only account where both growth and withdrawals are tax-free. That advantage compounds significantly over decades. I have seen people ignore this because they think the employer match is enough. It is not. It is the minimum viable action, not the optimal one.
Here is a specific problem I ran into. A client had a backdoor Roth IRA strategy that his accountant did not understand. The accountant tried to file the contribution as a regular Roth and flagged it for audit. The Backdoor Roth is perfectly legal for high earners who exceed the income limits, but it requires two steps: contributing to a traditional IRA and then converting it to a Roth. If you have other pre-tax IRA money, the pro-rata rule applies and your conversion becomes partially taxable. My client had a small old 401k rollover IRA that he had forgotten about from a previous job. That twenty thousand dollars sat there invisible for eight years. The pro-rata calculation meant only a tiny fraction of his backdoor contribution was tax-free. The fix was rolling that old 401k into his current employer's plan, which cleared the pro-rata issue. It took three phone calls and a lot of embarrassment. But it saved him roughly four thousand dollars in unexpected taxes that year.

The Problem With Automation
Automation is powerful but dangerous. I have watched people set up automatic transfers and then forget about their accounts for six months. They missed a fee, a dropped subscription, or a direct deposit error because they were too trusting of the system. I recommend reviewing every automated transaction once per month. Just thirty seconds per transaction. It takes maybe five minutes total. This habit catches problems before they compound. Another automation pitfall is duplicate withdrawals. I found this myself once. A subscription service changed its billing date and my automatic payment triggered twice in the same month. The bank charged an overdraft fee because the first payment was still processing when the second hit. I caught it during my monthly review, which is why I do the review. The fee was twelve dollars. The lesson was to set up payment alerts from my bank instead of relying purely on memory or automation.
When The Finance Step By Step Method Fails Completely
This approach does not work for everyone. It breaks down in several specific scenarios. If you earn less than fifteen hundred dollars per month after taxes, budgeting becomes abstract because the numbers do not support meaningful savings. In that case, the priority is income generation, not financial optimization. No budget method increases your paycheck. A Finance Step By Step framework assumes there is enough money to allocate. When there is not, it becomes a source of anxiety rather than a solution. It also fails for people with serious financial trauma. Watching someone panic over every expense is not helpful. If financial management triggers genuine anxiety or shame, therapy or working with a certified financial planner who specializes in behavioral finance is more useful than another spreadsheet. I am not qualified to treat that. I can only handle the mechanical side.
When To Stop Doing This Yourself
If you have more than five different investment accounts, complex tax situations involving rental properties or business income, or estate planning needs, hire someone. The cost of a fee-only fiduciary advisor paying you back within the first year through tax optimization is almost guaranteed if your situation is above a certain complexity threshold. The threshold is roughly one million dollars in investable assets or an annual income above two hundred thousand dollars with multiple income streams. Beyond that, the Finance Step By Step method becomes a maintenance tool rather than a creation tool. You still run the numbers. You still check the accounts. But the strategic decisions become too risky to make solo.
The Long Game
The method works because it is boring. It removes emotion from decisions by forcing you to write them down first. It creates friction where friction is useful and removes it where you want automatic progress. It does not promise wealth. It promises clarity. Clarity lets you make better decisions over time. Time does the rest. I have been doing this for long enough to see most people fail at the second step, not the first. They skip the ninety-day expense review and build budgets on estimates. Estimates are lies you tell yourself. The actual numbers are not as exciting, but they are honest. Being honest is what makes the system work.