Managing money every day is the part nobody prepares you for.
Most people learn about personal finance through quarterly reviews, budgeting templates, or yearly tax planning. Nobody tells you what happens between those checkpoints. That gap is where the entire system falls apart. I spent years watching accounts drift because small daily transactions were never captured before they became background noise. The process I settled on after about two years of broken spreadsheets and forgotten receipts is straightforward enough that I keep it simple.Finance Step By Step Daily
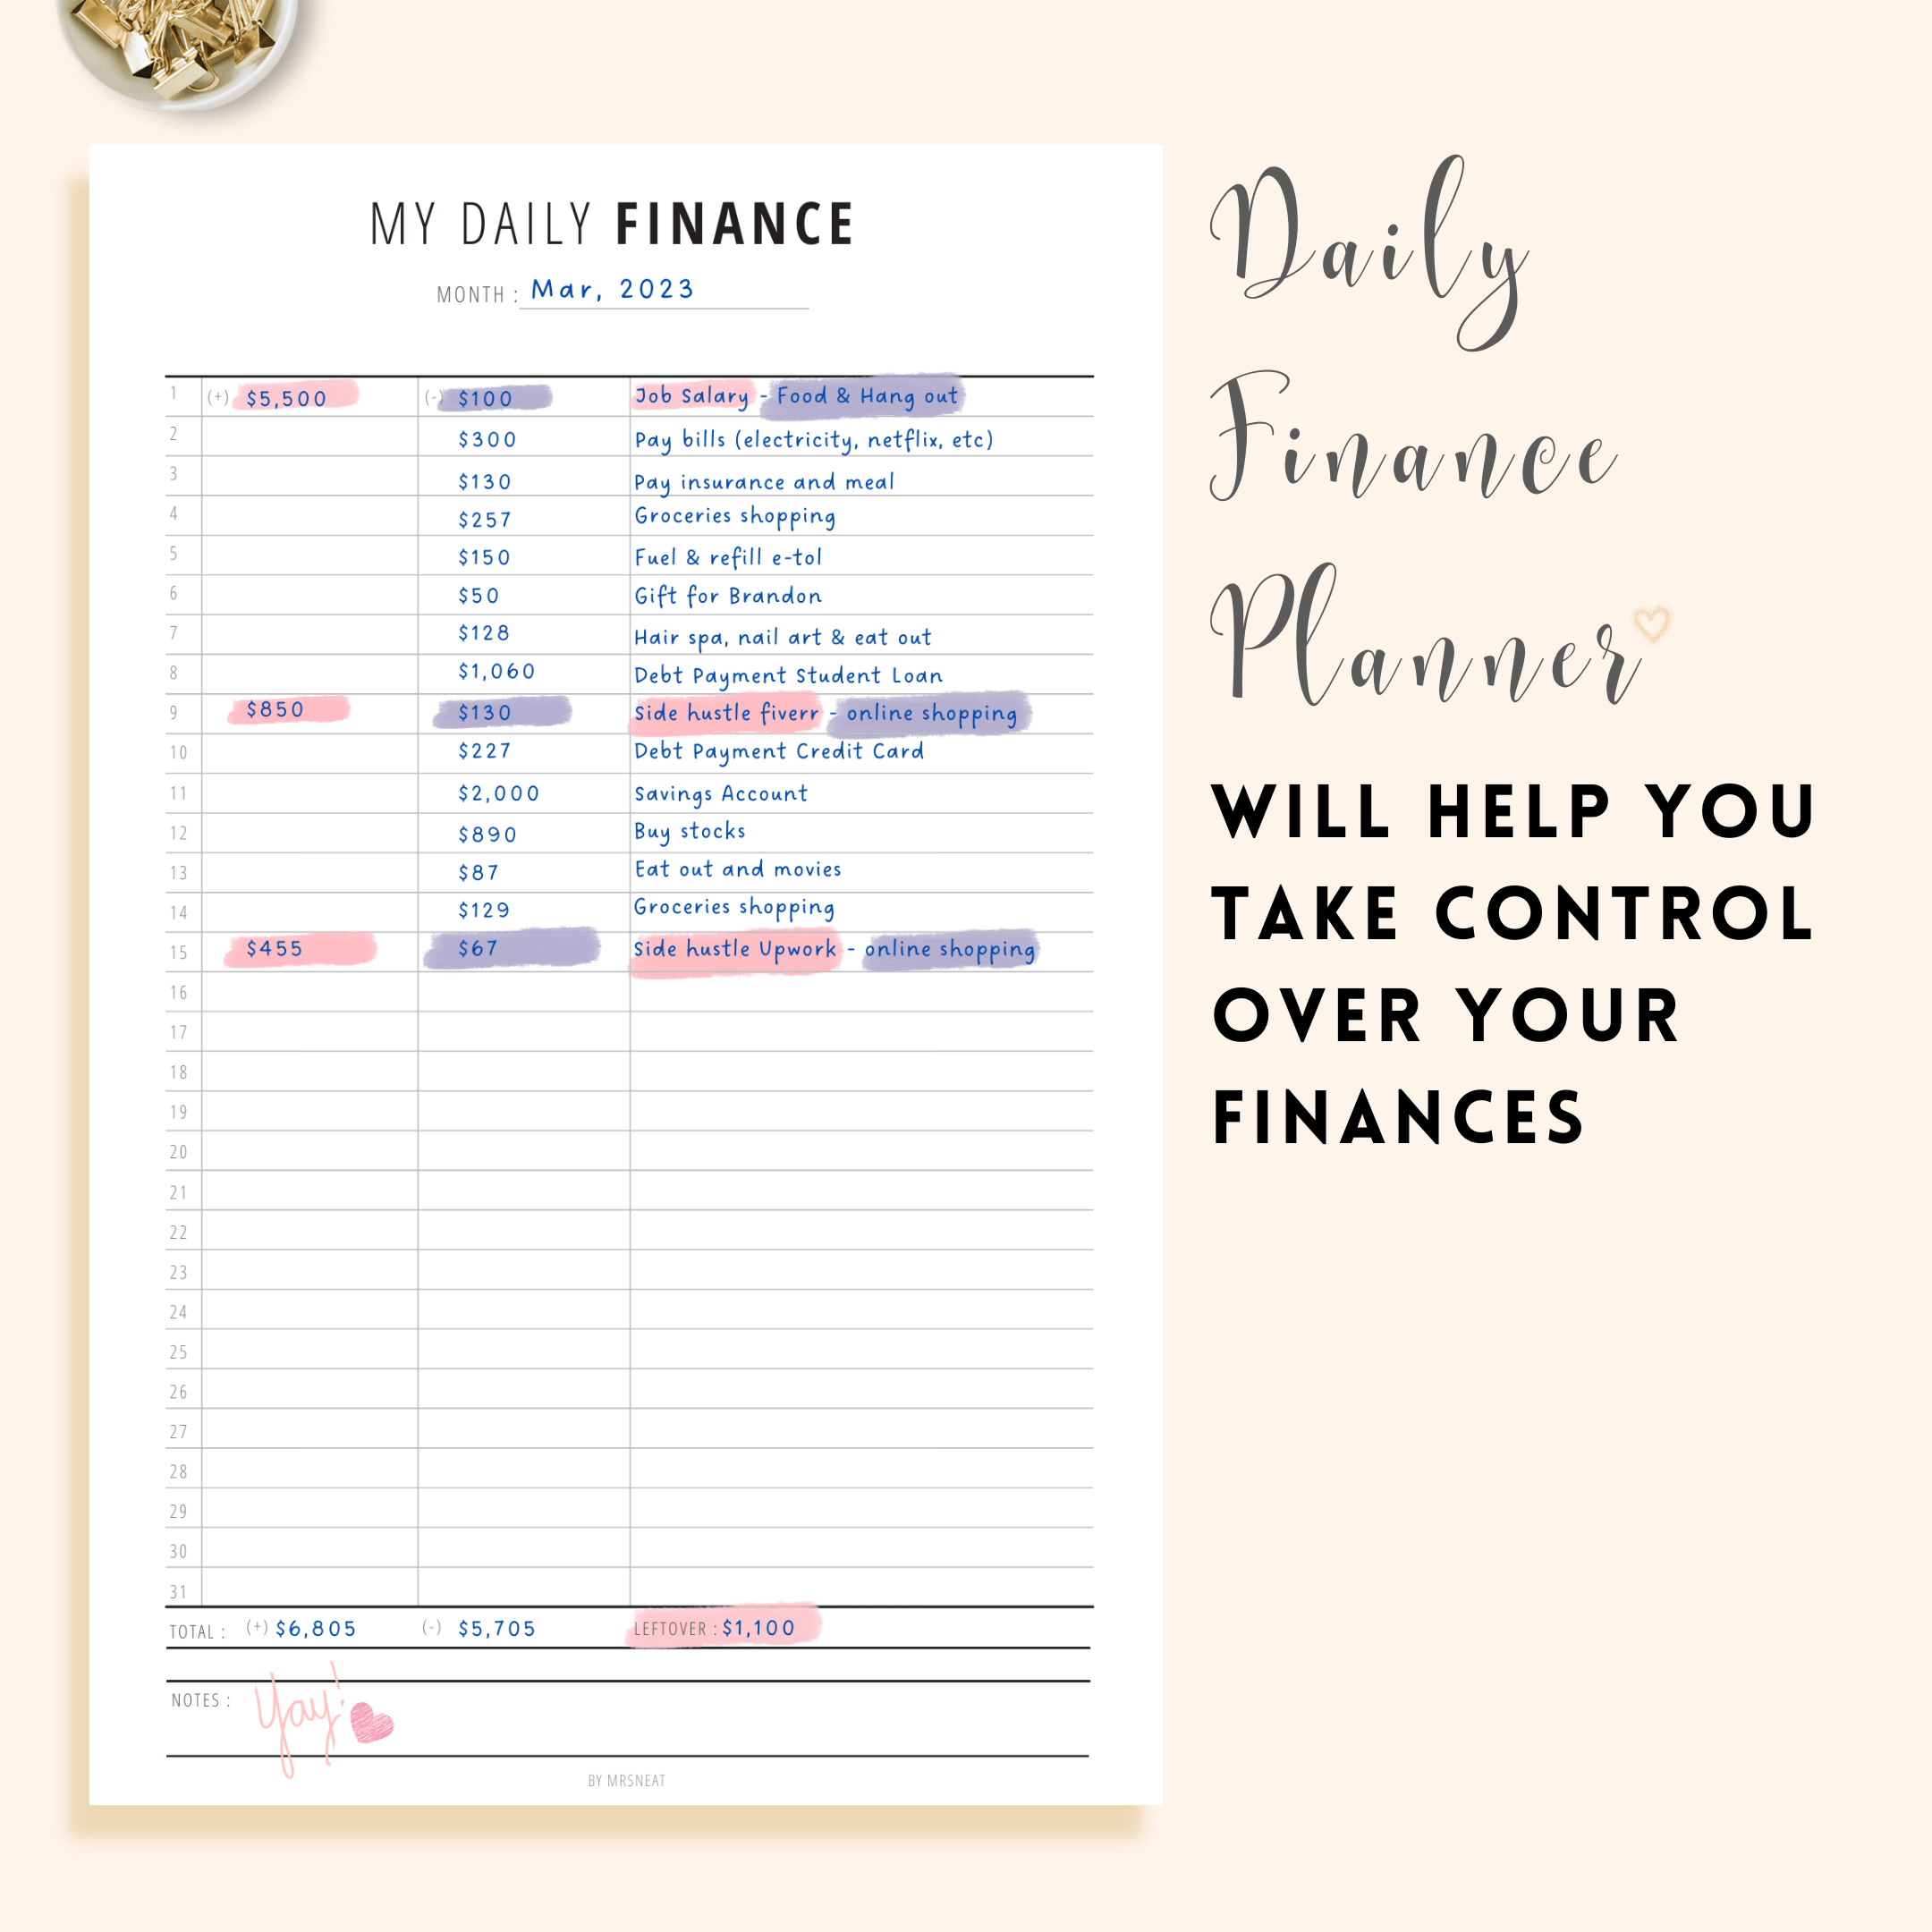
Step 1 is checking your primary checking account balance first thing in the morning. Not the total across all accounts. Just the one you use for spending. You open your banking app, look at the available balance, and compare it to yesterday's number. If the difference is exactly equal to a known recurring payment, nothing happened. If it's not, you dig in. This took me three weeks to build into habit. I kept skipping it because I thought "I'll catch it at lunch" and then I wouldn't. Step 2 involves recording every transaction before you move to the next one. You don't batch them. You don't wait until evening. You see a $4.50 coffee charge and you log it immediately in whatever tracker you're using. The reason this matters is that memory is unreliable for small amounts. I lost track of roughly $200 in a single month across twelve separate purchases under $25 each. They weren't memorable individually. They added up to something that showed up as a mystery shortfall. Step 3 is matching your recorded transactions against your bank feed once a day. Most banking apps have some form of transaction history you can export or view. You go through your logged items line by line and confirm each one appears in the bank record. Any discrepancies get flagged immediately. This step usually takes between 10 and 20 minutes depending on how many transactions your account processes in a typical day. My average is about 14 transactions. On days with more, like paydays or rent days, it stretches to about 30 minutes.
Step 4 is reviewing your budget categories for any that are close to their limit. Not all of them. Just the ones that are within 20 percent of their allocated amount. If you've allocated $400 for groceries and you're already at $350 by the 18th of the month, you stop assigning new grocery expenses to that category and move them elsewhere temporarily. This prevents the silent overspend that ruins monthly plans. Step 5 is writing down any pending or recurring charges you expect within the next 48 hours. Bills, subscriptions, automatic payments. You need to know what's coming so your available balance doesn't surprise you. I learned this the hard way when an unexpected $89 software renewal hit my account on the same day as my rent payment. I had enough to cover rent but not both. I missed the renewal, got charged a late fee, and then had to scramble for cash. Now I check pending transactions twice a week at minimum. Step 6 is noting one thing you could do differently with your spending today. This isn't about guilt. It's about noticing patterns. Maybe you spent $12 on parking when you normally drive to work. Maybe you ordered takeout when you usually pack lunch. You record the observation. The goal is awareness, not punishment. Over six months of doing this, I caught a pattern of weekend spending that was consistently 40 percent higher than weekday spending. That pattern didn't show up in weekly summaries.
The biggest problem people run into with daily financial tracking is inconsistency. You'll do it perfectly for eleven days and then miss three because something came up. That's normal. The system doesn't break if you miss a day. What breaks it is missing three days in a row and then giving up entirely. I've seen that happen repeatedly. The fix is simple: when you miss a day, you just pick up the next day. No catch-up session. No reset. You continue from where you are. Another issue is tool selection. You don't need a sophisticated app. A simple spreadsheet works fine. A notes app on your phone works fine. The tool that works best is the one you actually open every day. I've used Google Sheets, Apple Numbers, and a custom script I wrote that pulled directly from my bank's API. The script was the most accurate but also the most brittle. When my bank changed their data format, the script broke for two weeks. The spreadsheet never broke because I typed the data myself. I switched back. There's a counter-intuitive insight here that most people miss. The act of recording transactions daily changes your behavior more than any budgeting rule ever could. When you know you have to log a $60 dinner the same day you go out, you think twice before going. That psychological effect is worth more than the tracking itself. I've recommended this method to people who explicitly said they didn't care about the numbers. They still cut their spending by about 15 percent within two months just from the friction of daily logging.
Get the Full Details
The main limitation of this approach is that it doesn't handle irregular income well. If you're a contractor or freelancer with uneven monthly deposits, the daily balance checks become less meaningful because your baseline changes constantly. In that case, you switch to weekly reviews instead of daily ones. I handle this by tracking on a rolling 14-day window rather than a calendar month basis. It's less clean but more accurate for variable income. If you want to start this tomorrow, here's what you need. Open a note on your phone or a blank spreadsheet. Create columns for date, description, amount, category, and note. At the end of each day, spend 15 minutes filling in the rows. Don't worry about perfect categories. Rough estimates are fine for the first month. By the second month, you'll have enough data to refine the categories. By the third month, the whole process should feel automatic and take under 10 minutes per day. I don't track my net worth daily. That's a monthly or quarterly exercise. I don't obsess over investment performance on a daily basis either. The daily process is strictly about cash flow awareness. Keeping your spending lane clear so the bigger financial decisions have accurate inputs. Everything else runs on top of this foundation. If the foundation cracks, the rest of the structure develops problems you won't notice until they're expensive to fix.