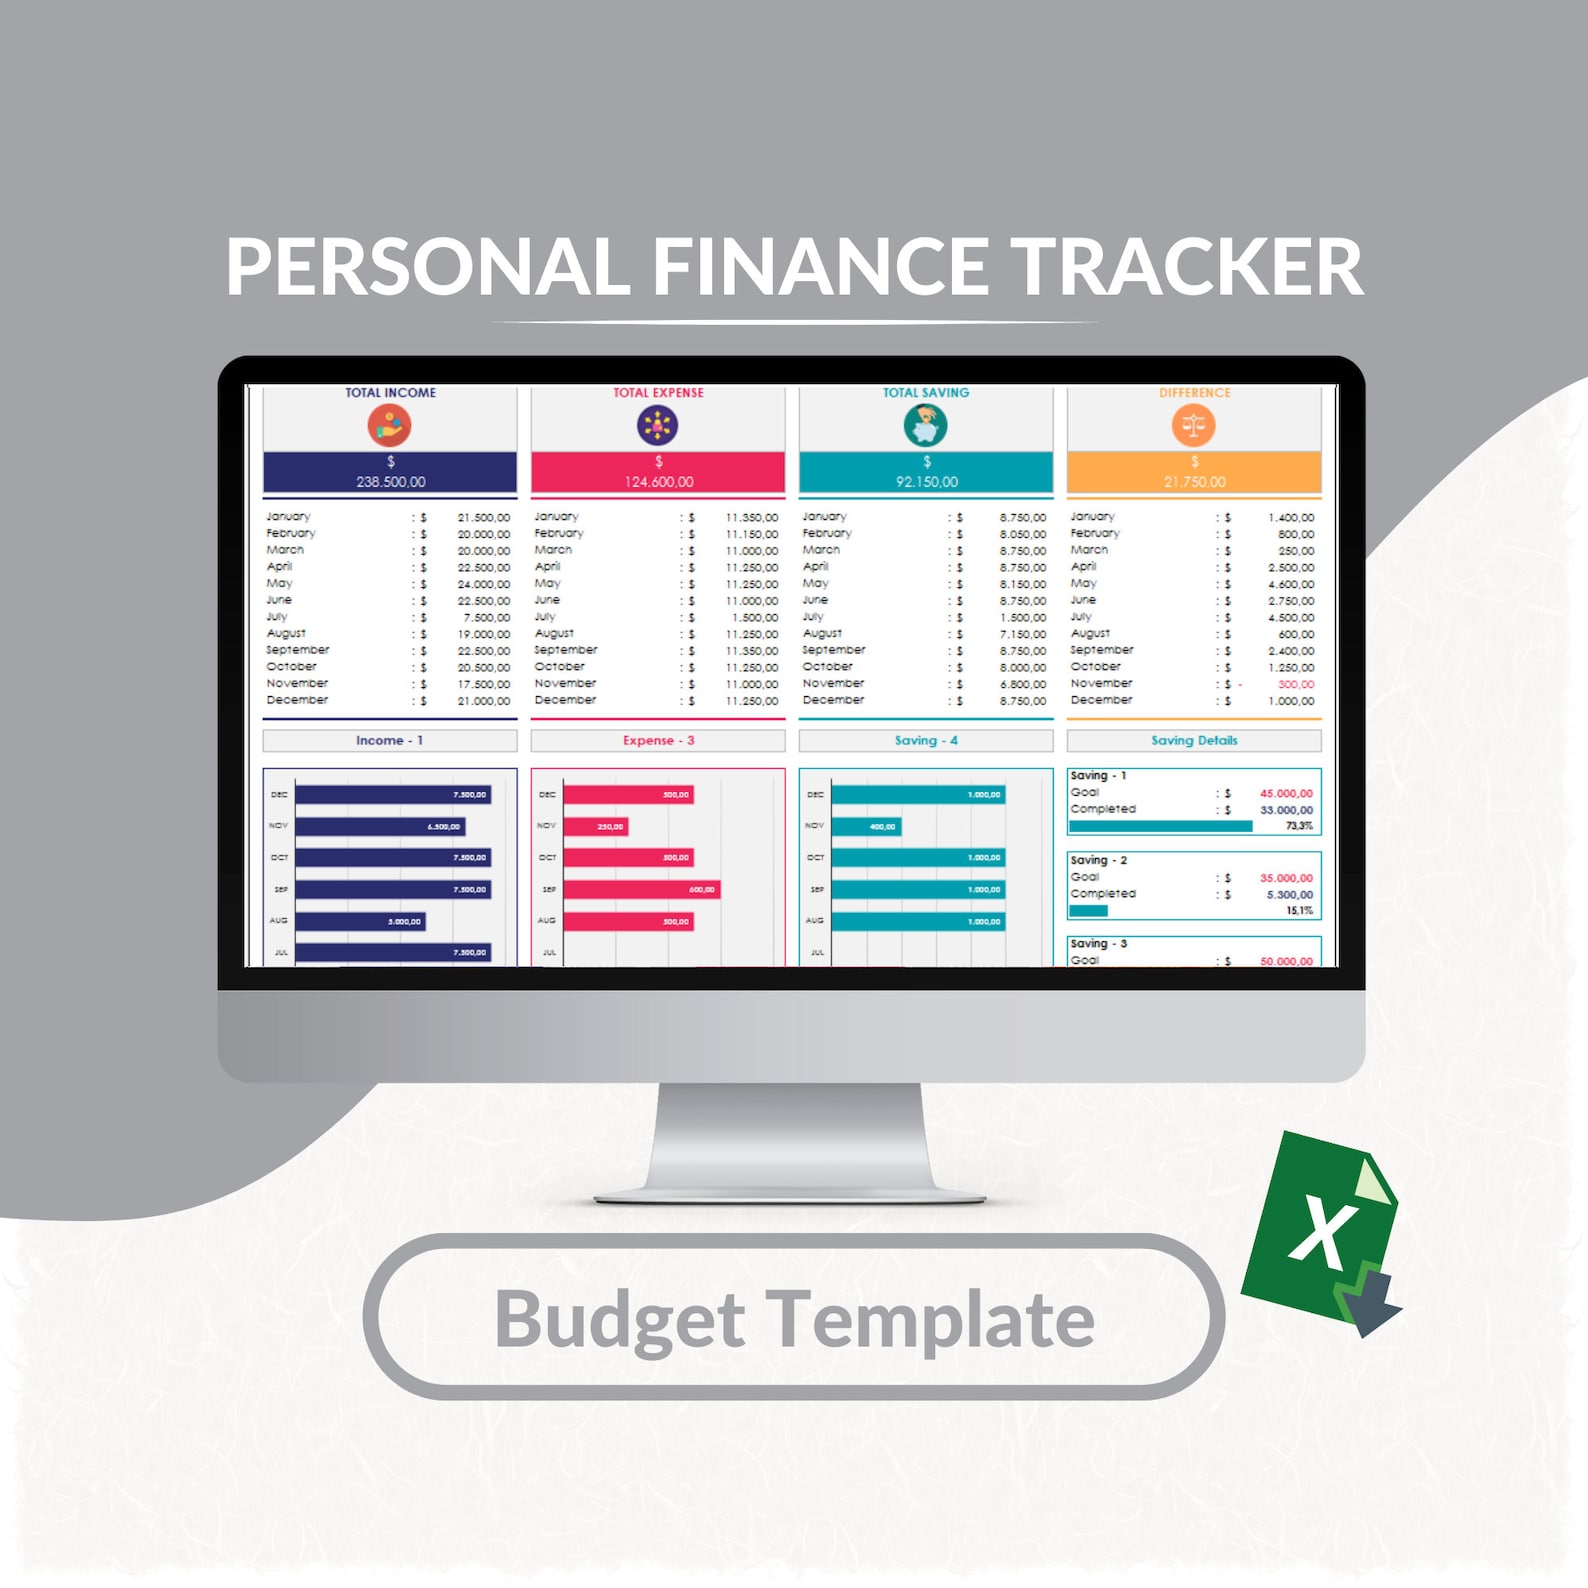
Why your finance tracker keeps lying to you
I built a custom spreadsheet-based Finance Tracker back in 2014 that I still use every single day. It tracks cash flow across three business accounts, two personal accounts, and a handful of recurring subscriptions. The problem nobody tells you about these tools is that they have a fundamental flaw: they are only as honest as the data you feed them, and humans are terrible at feeding them honestly. The average person who says they "track their finances" is actually doing something closer to monthly accounting theater. You remember to log the big stuff. You forget the $4.99 app charge. You miss the duplicate subscription. Six months later you look at your finance tracker and wonder where the money went. It wasn't magic. It was just a thousand tiny gaps in your own record-keeping compounding over time.
What a Finance Tracker Actually Needs to Do
A proper system does three things: captures every outflow within twenty-four hours, categorizes it in a way that doesn't require you to think too hard about it, and produces one report that answers the question "can I afford this" without making you open four different spreadsheets or banking apps. Most commercial tools fail at step one because they push you toward manual entry or connect to your bank through APIs that drop transactions for no explainable reason. Yodlee, which powers a lot of these connections, will miss a transaction from a credit union sometimes and not tell you about it. Your Finance Tracker looks fine until you're three months behind on a payment and you realize half your history was just invisible. The workaround I ended up using is brutally simple. I stopped trusting automated feeds entirely. I export my bank CSV files every Sunday night, import them into a master file, and then do a fifteen-minute visual scan. That scan catches the things the API misses. The cost is roughly fifty minutes per month. The benefit is that when I open my Finance Tracker I actually believe what it's showing me.
How to Build Something That Won't Drift
There are two approaches. The first is to buy something like Monarch Money, YNAB, or even Google Sheets with a pre-built template from someone on Reddit. The second is to build your own. I built my own. Here is what I learned in the process and what I would do differently if I were starting over today. The first thing you need is a categories list that is intentionally small. I started with forty-two categories. I'm down to fourteen now. Every category that isn't immediately useful becomes a place where transactions go to die because you never bother categorizing them. Keep it under fifteen and force yourself to use it. The second thing is a reconciliation step. This is the part beginners skip. You match your finance tracker total against your actual bank balance at the end of every month. If they don't match, you find the difference. I once had a three hundred dollar discrepancy that turned out to be a transaction my bank classified as "pending" for eleven days, during which time my Finance Tracker showed it as spent but my actual available balance didn't reflect it yet. It sounds minor but it completely wrecked my ability to trust the tool for about six weeks.
Get the Full Details
Here's the counter-intuitive part that most people miss: importing your data automatically is often worse than doing it manually for long-term accuracy. Automated imports create a false sense of security. You stop checking because "the system handles it." Manual weekly entry takes twenty minutes and builds actual awareness of where your money goes. A study from the Journal of Behavioral Finance found that people who manually entered their expenses retained twice the retention of spending patterns compared to people who used auto-sync tools. The effort is the point.
Setting Up Your Finance Tracker for Real Use
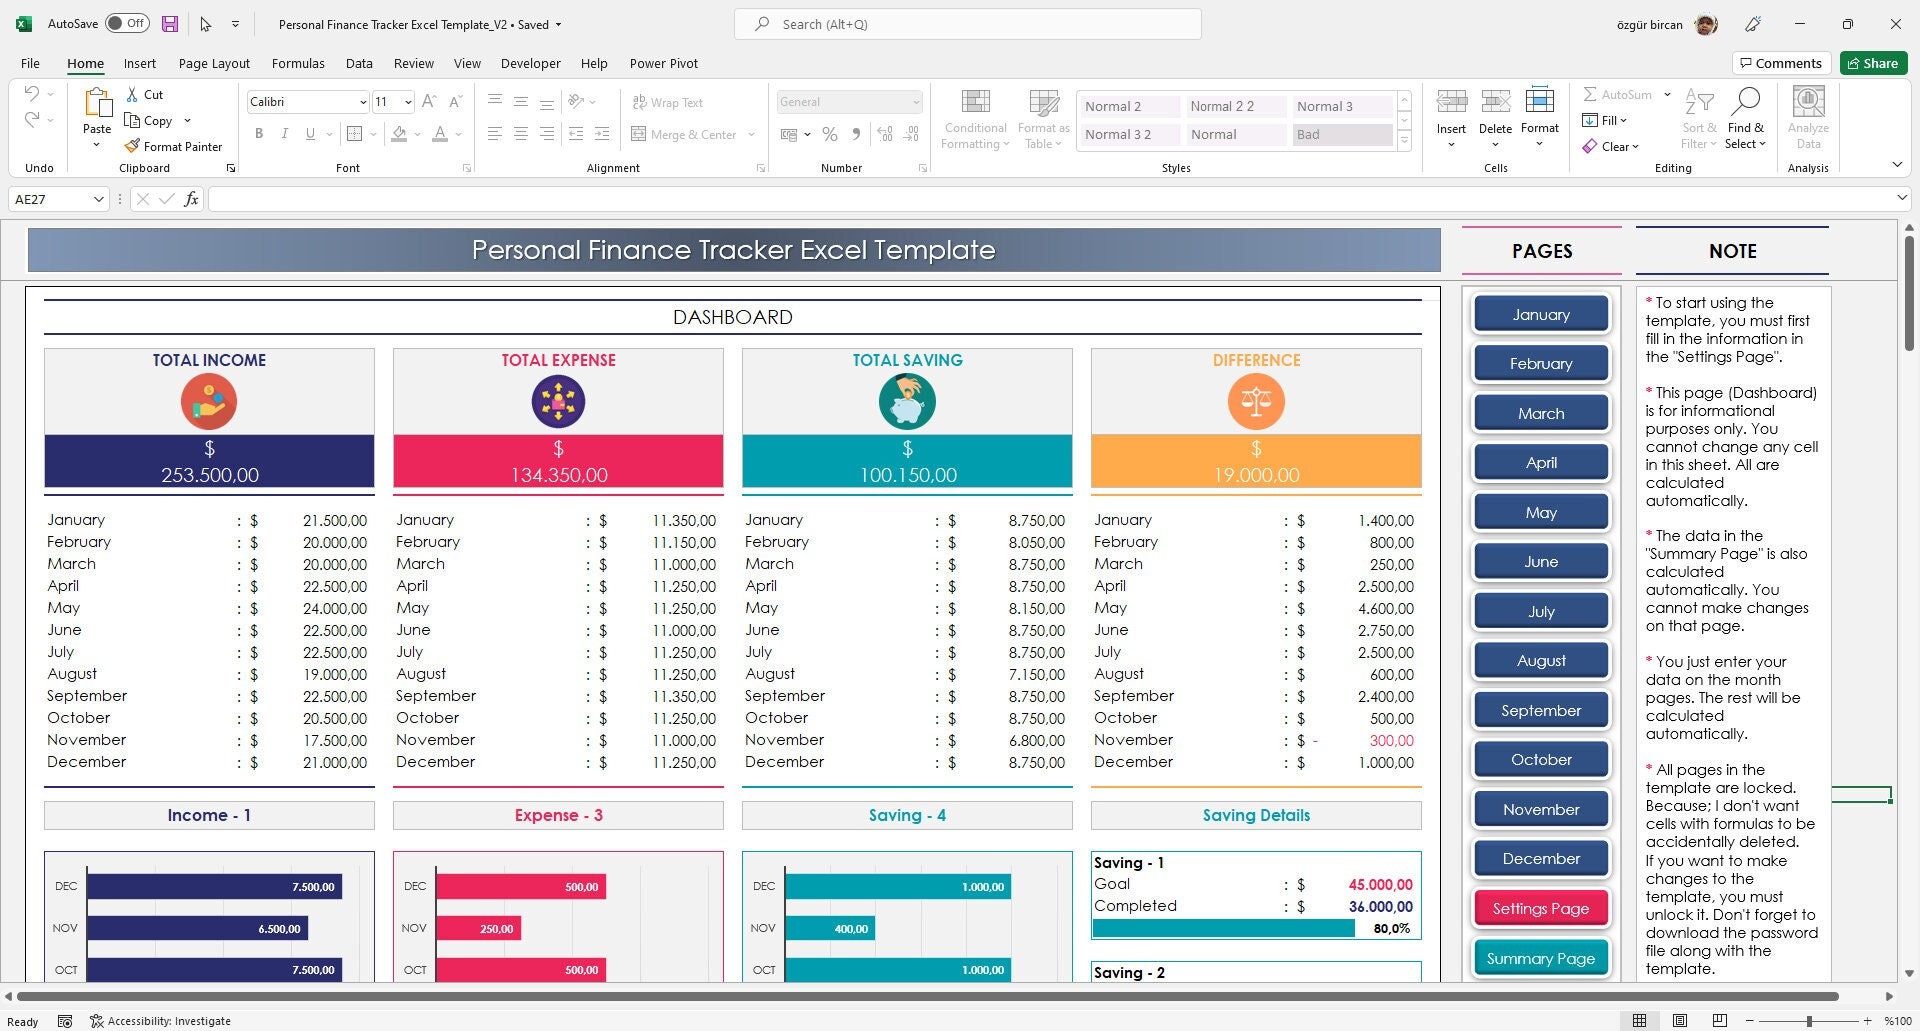
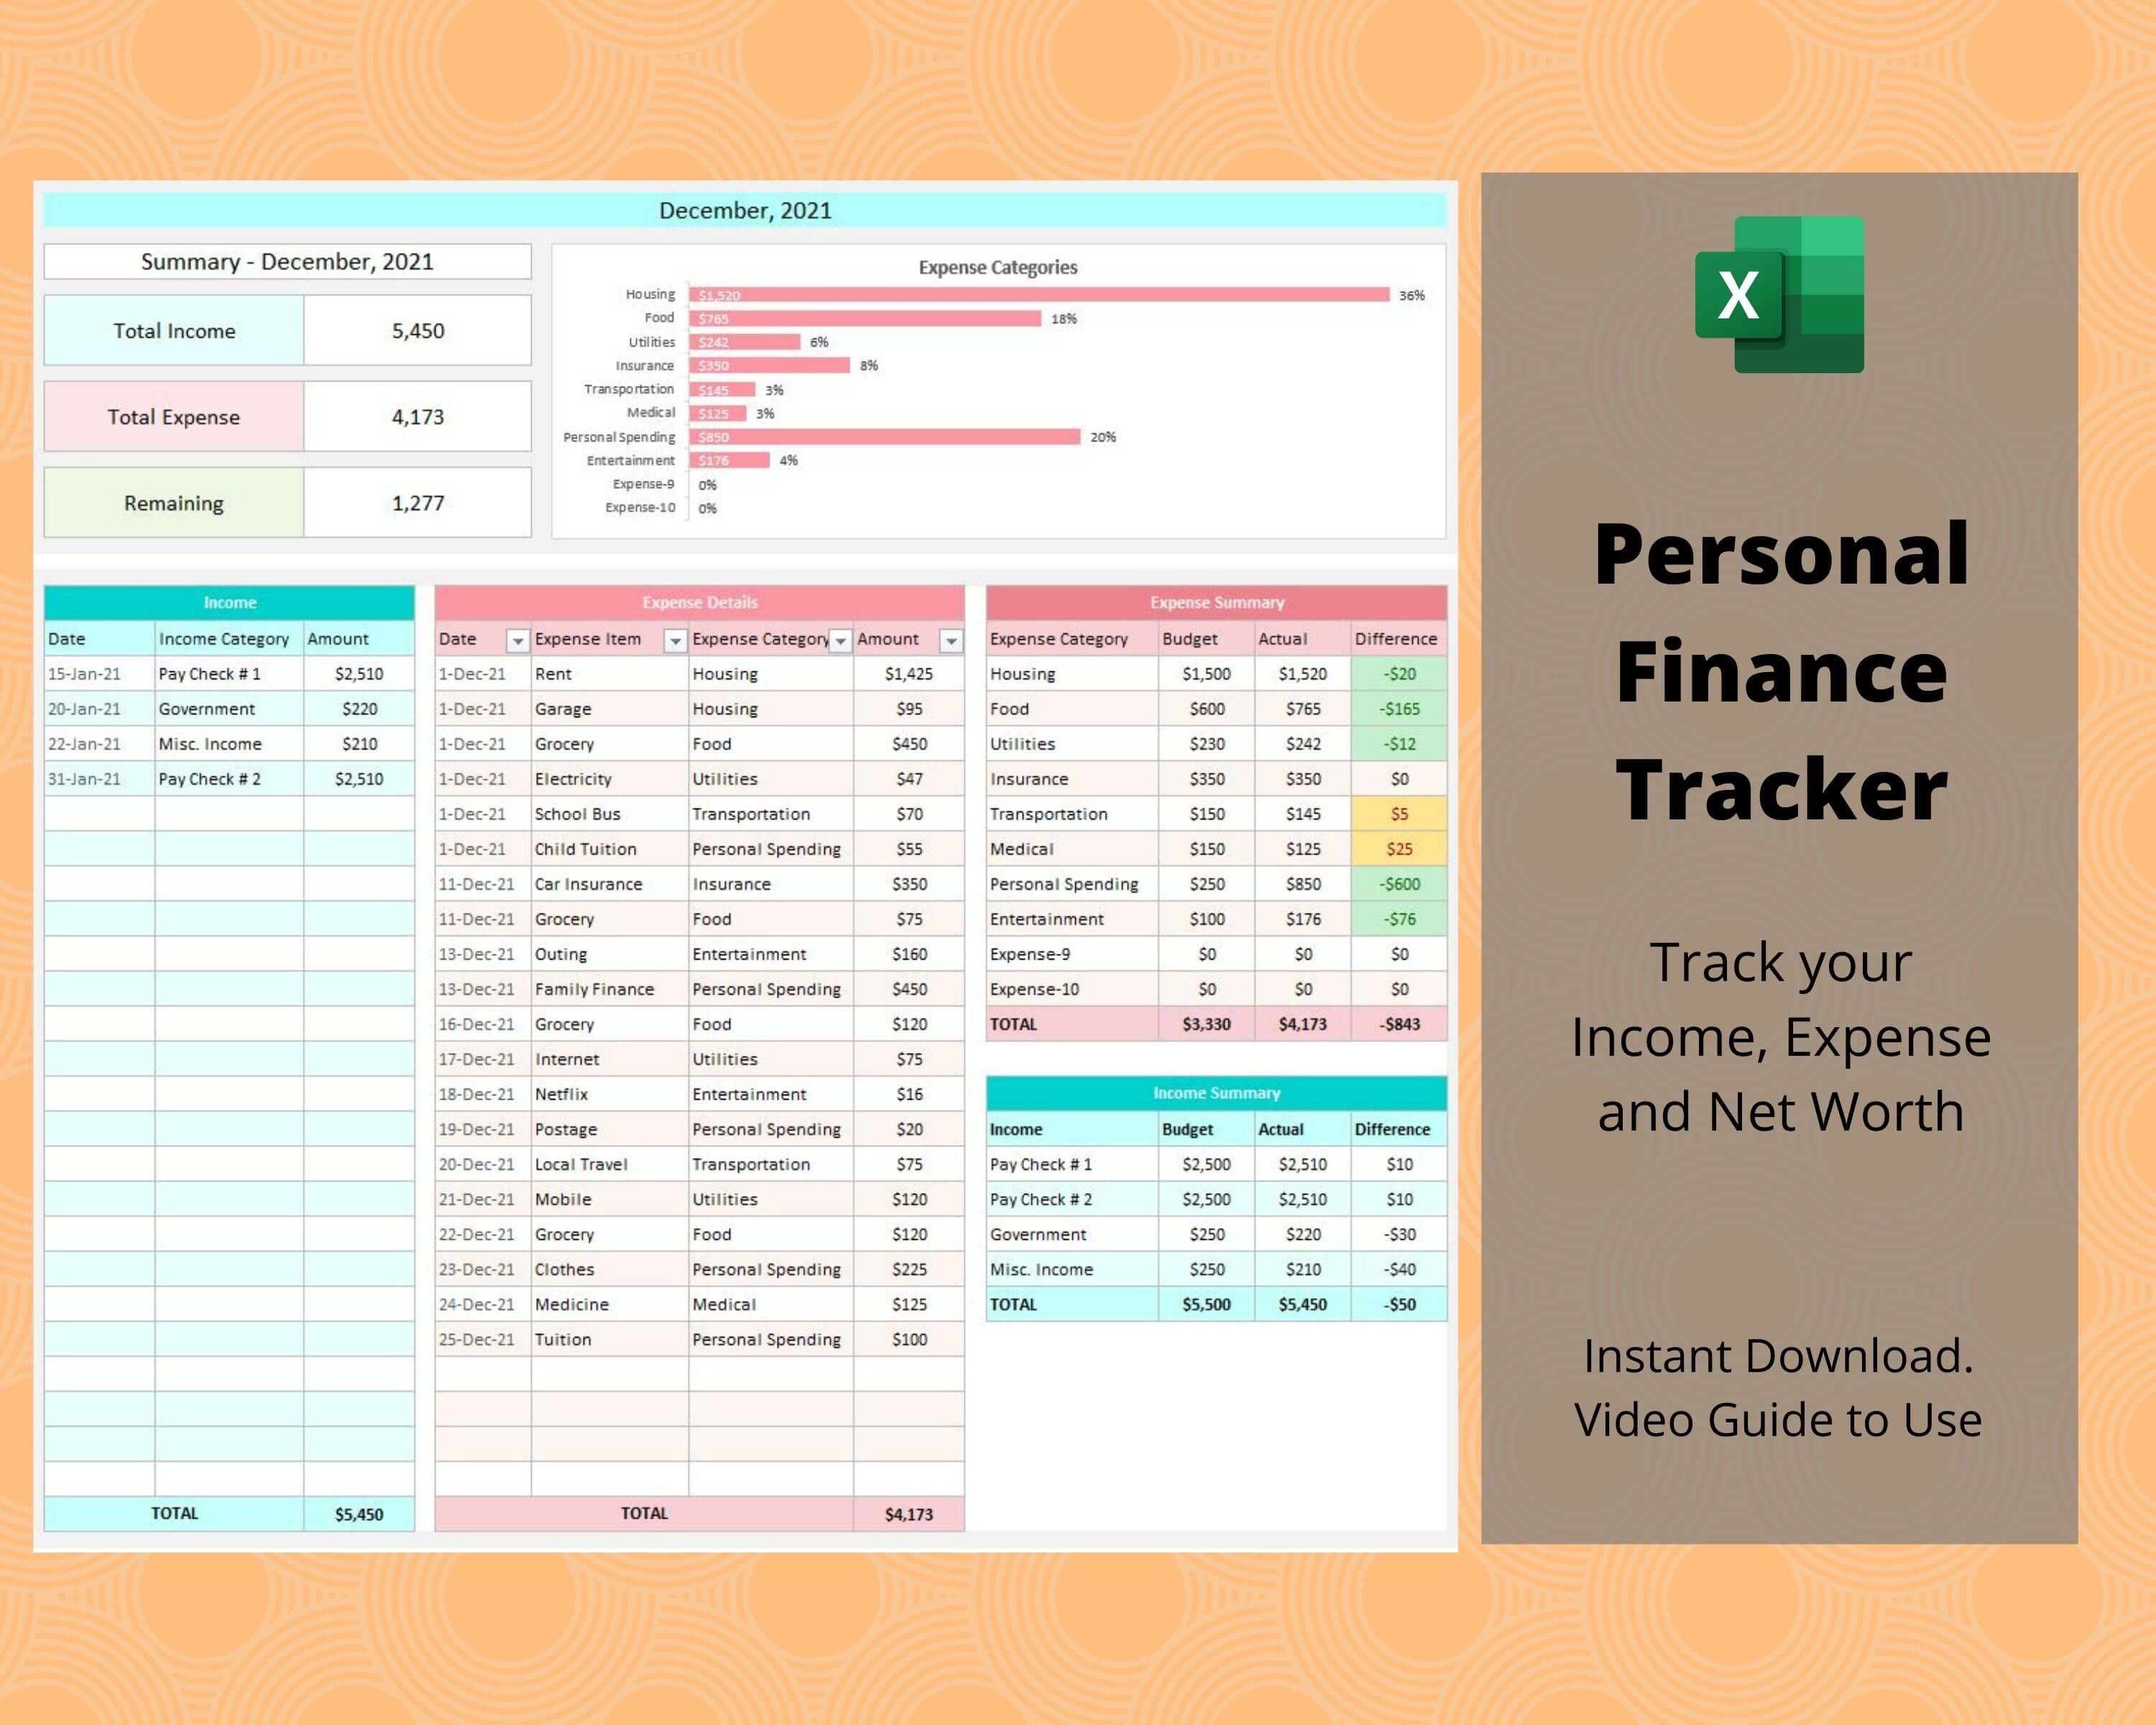
If you want to build this yourself in Google Sheets or Excel, here is the skeleton I use and have been iterating on for over a decade. Create three tabs. Tab one is your transactions log with columns for date, description, amount, account, category, and notes. Tab two is your monthly summary that pulls from the transaction tab using something like SUMIFS. Tab three is your budget comparison that shows planned versus actual by category. That's it. Three tabs is all you need. Anything more than that and you'll never keep it updated because the overhead of maintaining extra sheets will burn you out within ninety days. For the transactions log, use data validation on the category column so you can't accidentally create a new category by misspelling "groceries" three different ways. I learned that lesson the hard way when my category report showed twelve different versions of the same expense and I had no idea which one was the real one.
Use conditional formatting to flag anything that deviates more than twenty percent from your trailing three-month average in that category. This caught a $200 electricity bill that was actually a $470 bill in November. The tracker didn't just show me I spent more. It highlighted that something was wrong before I'd even checked the statement.
The Tools That Are Actually Worth Using
If you don't want to build your own system, here are the options I've tested and what I think of each one honestly. YNAB (You Need A Budget) is the most rigorous option. It uses zero-based budgeting, which means every dollar gets assigned before you spend it. The learning curve is steep and the subscription costs about twelve dollars a month. It works well if you have a tight budget and need external discipline. It falls apart if you have variable income because the method assumes you know what you'll earn each month. Monarch Money replaced Mint after it shut down and is currently the closest mainstream alternative. It connects to most banks, has decent categorization, and the mobile app is actually usable. The annual cost is around forty dollars. It's the one I recommend to people who just want something that works without thinking about it too much.
Google Sheets with a template costs nothing except your own time. The templates available from r/personalfinance and other communities are decent starting points. I've seen templates from u/MarcusTheInvestor that track everything from net worth to debt payoff timelines in a single sheet. The risk is that a template someone built in 2021 might use outdated functions or formulas that break when Google changes something behind the scenes.
When a Finance Tracker Is the Wrong Tool
Let me be clear about this because nobody talks about it enough. If you have less than two thousand dollars in monthly expenses, a full finance tracker is overkill. You need a notebook and a calculator. The setup time alone makes these systems a net negative for low-volume expense situations. Similarly, if you earn purely commission-based income with no predictable pattern, most budgeting frameworks will frustrate you rather than help you. In that case, a simple profit-and-loss approach where you track revenue and expenses monthly and take a fixed draw from whatever surplus remains is more practical than trying to force your income into weekly budget buckets. And if you have a spending disorder or relationship with money that makes tracking feel like punishment, stop. Tracking is a tool, not a moral obligation. I've seen people spiral because they couldn't stick to a spreadsheet for two weeks straight and then abandoned the entire practice. An empty finance tracker is worse than no tracker because it gives you a false baseline of failure.

The single most important habit I've kept for ten years is reconciliation. Every month I open my Finance Tracker, pull up my actual bank statement, and check that the ending balances match. This takes about twenty minutes and catches errors before they compound. Without it, you're just maintaining a fantasy. That's it. Build small. Reconcile monthly. Drop anything that doesn't serve you after thirty days of use. And stop buying tools that promise automation when what you actually need is someone making you look at your spending once a week.