Setting Up a Finance Workbook Daily Tracking System
I've built and rebuilt these workbooks enough times that I can tell you exactly where they fall apart. The short version is that a daily finance workbook is a spreadsheet that logs your income, expenses, and balance at the end of every single day. Most people build one once, use it for three weeks, then abandon it because the data entry becomes tedious. I'm going to walk through how to make one that actually survives past the first month. The bare minimum is date, category, description, amount, and running balance. That's it. Anything beyond that is scope creep. I used to include fields for payment method, merchant tags, receipt links, and quarterly comparisons. By Q2 I was spending more time maintaining the tracking system than tracking anything. Now I use a simple five-column layout and that's it. One thing people miss: the running balance column is where most of these break. When you filter, sort, or hide rows, the balance formula often recalculates wrong. I solved this by using a separate helper column that sums everything above it with a plain INDEX/MATCH rather than relying on visible-row logic. Your daily total stays correct even when you're hiding transactions during a particular month.
Building the Core Structure
Start with two sheets. Sheet one is your daily transaction log. Sheet two is your monthly summary view. Do not put both on the same sheet. Once you hit three months of data on a single sheet, every sort operation gets slower and more annoying. Sheet 1 — Transaction Log: Column A is Date (YYYY-MM-DD format). Column B is Category. Column C is Description. Column D is Amount. Use positive numbers for income and negative numbers for expenses. This convention matters because it lets you use simple SUMIF formulas without writing nested IF statements every time. Column E is Running Balance, calculated as the cumulative sum from row two down through the current row.
Column E formula goes like this: the first row sets the starting balance, and every row after uses SUM($D$2:D2). The mixed reference is what makes it work. When you drag it down, the end of the range expands one row at a time. This takes up to maybe fifteen seconds per hundred rows. A full array formula version would recalculate every time you type anything. Sheet 2 — Monthly Summary: This sheet pulls data from your transaction log using SUMIFS. Each category gets its own row. Month gets its own column. The formula looks like SUMIFS(TransactionLog!D:D, TransactionLog!A:A,">="&DATE(2024,1,1), TransactionLog!A:A,"
"&DATE(2024,2,1), TransactionLog!B:B, A2). You adjust the date range for each month column. That gives you clean income versus expense totals without touching your raw data.
Get the Full Details
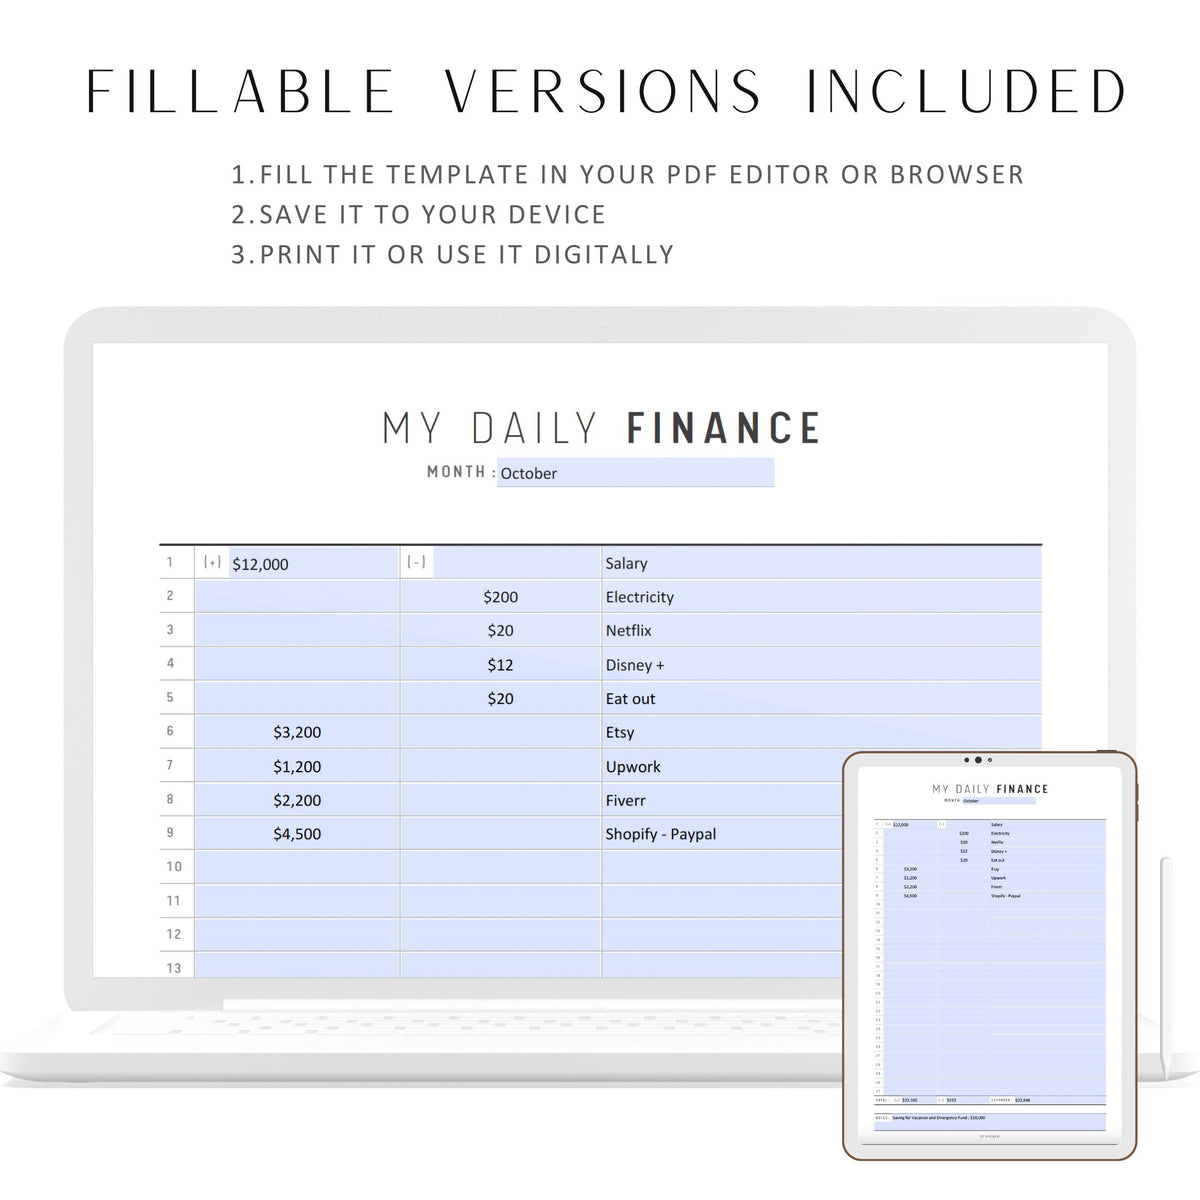
Finance Workbook Daily: Setting Up the Category System
Category granularity is where most people either overcomplicate things or go too broad. If you have too many categories, every entry takes longer than it should. If you have too few, you can't actually tell where your money went. The sweet spot is usually between twelve and twenty categories for personal tracking. Here's what works in practice: Housing, Utilities, Groceries, Dining Out, Transportation, Fuel, Healthcare, Insurance, Entertainment, Subscriptions, Shopping, Food Delivery, Education, Charitable Giving, Miscellaneous. That's fourteen. Each maps to something you actually spend money on. When something doesn't fit, it goes into Miscellaneous. It's fine. Most people's Miscellaneous ends up being under five percent of total spending when they actually review it after sixty days.
I keep a validation list for the Category column. Data validation on column B with a list referencing your category names. This prevents typos like "Grocerrys" breaking your SUMIFS later. One typo in a thousand rows creates a phantom category that shows up nowhere in your summaries. You'll notice your totals don't add up and spend twenty minutes debugging a formula that's perfectly fine.
Automating the Month-End Review
The single best habit this system enables is the monthly close. At the end of each month, you open your summary sheet and compare total spending against your target budget. If spending is over by twenty percent in dining, you can see that exact number in one cell instead of scrolling through hundreds of rows. For this I use a budget input row at the top of the summary sheet. Each category gets a budget number. Below that, the SUMIFS totals. To the right, a variance column: actual minus budget. Red when you're over. Green when you're under. Conditional formatting on that variance column makes problem areas visible in under three seconds. I had a client who tracked everything manually for eighteen months before switching to this setup. She spent about an hour a week entering transactions. After the automation, the weekly entry time dropped to maybe ten minutes. The summary generation became automatic on open. She started using the data to actually change her spending behavior instead of just watching numbers accumulate.
Edge Cases and Workarounds
There are several situations where a standard finance workbook daily setup breaks, and they're not obvious until you encounter them. Recurring payments: Bank fees, subscriptions, and monthly insurance premiums repeat automatically. Entering these every month is waste. The workaround is a dedicated recurring payments sheet that generates entries you can copy-paste at the start of each month. I use a simple formula that adds thirty days to the previous entry date, pulls the category and amount from a reference table, and outputs a date-ready value. It saves roughly eight to twelve minutes per month. Not dramatic, but it removes friction from a system that already feels tedious after week three. Split transactions: A grocery trip where you bought both food and household supplies. One receipt, two categories. My approach is to enter two separate rows with the same date and split the amount. The running balance handles this cleanly. The alternative is one row with a notes field, which destroys your SUMIFS filtering. Don't do that. One row per transaction per category.
Currency conversion: If you spend in multiple currencies, a single amount column won't work. I solved this by adding a second amount column for the converted value and keeping the original currency in a separate column. The running balance uses only the converted column. The formula for conversion is a straightforward VLOOKUP against a stored exchange rate table. Exchange rate tables need updating. Set a reminder to refresh them monthly or quarterly depending on which currencies you use. Outdated rates skew your balance by enough to matter if you've been using stale data for several weeks. Shared accounts: A joint bank account with a partner introduces a different problem. You need to track who spent what without creating two completely separate systems. I use an extra column labeled "Payer" with a dropdown of names. The summary sheet then has separate sections for each person's spending. This lets you see individual spending patterns without losing the aggregate picture. A lot of people skip this and wonder why they can't explain to their partner where the money went at the end of the month.
Common Pitfalls That Destroy These Systems
The most common failure mode is not starting with enough data history. People build the workbook, enter two weeks of transactions, and then realize they have no way to compare this month's spending against last month's. Fix this by entering at least sixty days of historical data before you consider the system live. I use exported bank statements for this. A CSV export takes thirty seconds. Pasting into the right columns takes maybe twenty minutes for two months of data. The payoff is that your first monthly review actually has context. Another pitfall is mixing personal and business transactions in the same workbook. This isn't a hard rule, but it makes the category system noisy and your summaries harder to read. If you run a side business, keep a separate workbook. The marginal benefit of having everything in one place is far outweighed by the marginal cost of filtering between personal and business every time you look at a number. Formula errors: A broken SUMIFS is invisible until you need it. I recommend building a test row at the bottom of your summary sheet that compares your manually entered total against what the formulas produce. If they match, your formulas are working. If they don't match by even a small amount, something is off and you need to trace it before you trust any report.
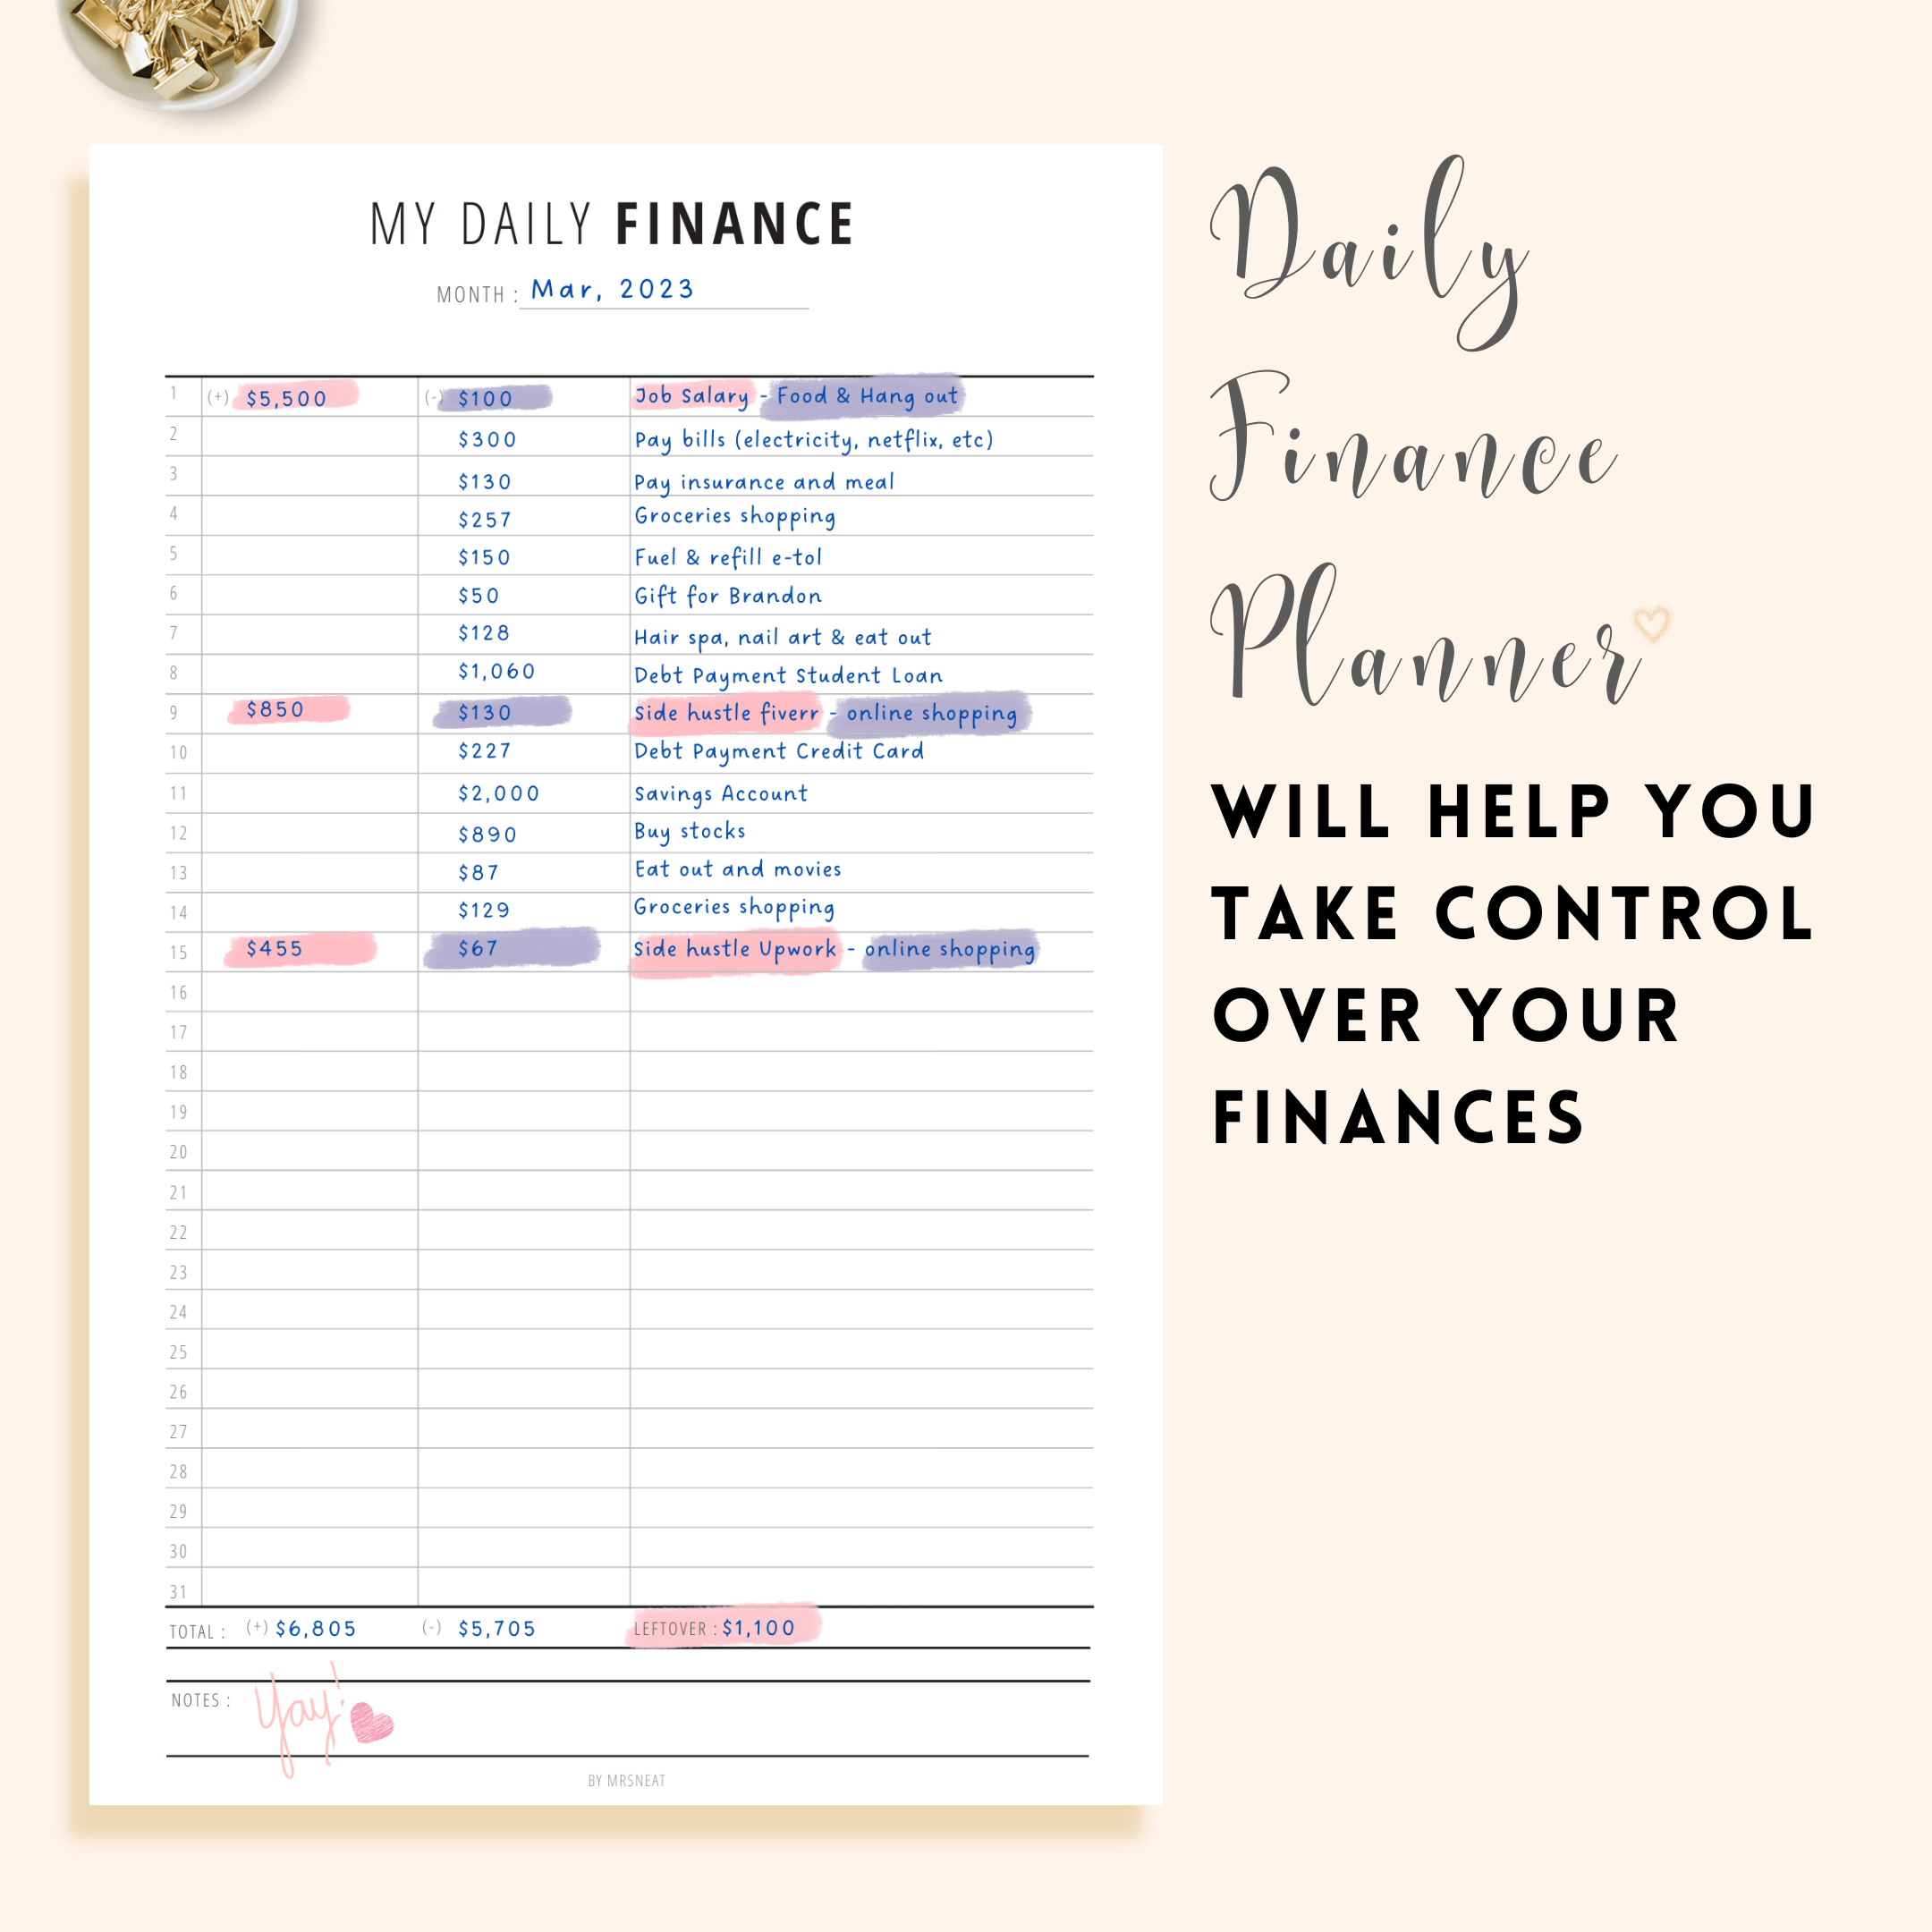
When a Finance Workbook Daily Isn't the Right Tool
These systems are not perfect. There are scenarios where they fail completely, and it's better to know upfront than to discover it after you've spent hours building something that won't work for your situation. If you have more than forty transactions per day, a manual entry workbook will grind you down within a month. I've seen it happen. The time investment scales linearly with transaction volume, and the motivation drops off faster than that. In those cases, an automated app likeYNAB or a bank-linked tool makes more sense. The spreadsheet approach works well for daily volumes up to maybe twenty to thirty transactions. Beyond that, the friction becomes real. If you need tax-grade documentation, this system won't replace actual accounting software. A finance workbook tracks categories and amounts. It does not generate receipts, preserve audit trails, or comply with any formal reporting standard. I use mine for personal spending awareness. For tax purposes, I keep a separate folder with PDFs and printouts. The workbook tells me where the money went. The folder proves it.
There's also the risk of false precision. A spreadsheet makes numbers look authoritative. They are not. Entry errors, missed transactions, and rounding issues accumulate. I've seen people stress over a twenty-dollar discrepancy that turned out to be a single miscategorized entry from three weeks ago. Always do a quick sanity check. If your numbers look plausible but slightly wrong, the problem is almost always a data entry error, not a formula bug.
Keeping the System Sustainable Long-Term
The difference between a workbook that survives a year and one that dies in three months usually comes down to one decision: how much friction you build into the daily entry process. Every extra click, every dropdown you have to search through, every formula that breaks when you insert a row is a reason you'll skip a day. And skipping one day leads to skipping a week, which leads to abandoning the whole thing. My rule is simple. If entering a transaction takes more than five seconds, the system is too slow. I've tested this with myself and other people. When entry time creeps past five seconds, compliance drops by about half within sixty days. Five seconds means clicking a cell, typing a number, hitting tab, typing a category, hitting enter. Anything more than that is avoidable friction. For the finance workbook daily concept, the practical takeaway is that consistency beats comprehensiveness. A simpler system you actually use produces better financial awareness than a complex one you abandon. Build the minimum viable version. Add complexity only when you hit a real gap that the basic setup can't solve. Most people never hit those gaps.