Setting Up a Finance Workbook Quick System That Actually Sticks
Most people build a finance workbook that looks great on day one and falls apart by week three. The problem isn't the template — it's that they treat it like a static document instead of a living process. I spent years building and breaking these systems across a few different companies before I stopped overcomplicating things.
The core idea behind a Finance Workbook Quick setup is simple enough: track every dollar coming in and out, categorize it consistently, and review the numbers weekly. That's it. What people miss is the review cadence. Without a weekly check-in, the whole thing becomes a graveyard of incomplete entries.
I once had a client who spent forty-five minutes every Sunday reclassifying transactions. She was using a basic Google Sheet with manual entry and no automation. By switching to a connected bank feed with pre-set categories and spending ten minutes on a Monday morning review instead, she dropped that time down to roughly eight minutes per week. The data quality improved because she wasn't rushing to clear a weekend backlog.
Getting Started With Finance Workbook Quick
Start with three tabs minimum: one for income, one for expenses, and one for the summary dashboard. Don't add more until you've been using it for thirty days. Extra tabs create decision fatigue and people abandon the ones they use least.
For the income tab, log gross pay, side income, interest, and any irregular entries. Use dates and keep descriptions consistent so filtering works when you need it. A messy description field like "transfer" or "payment" makes month-over-month comparisons painful. I always tell people to use something like "Monthly retainer from Acme Corp" instead of just "Acme."
The expenses tab needs consistent categories. Here's the counter-intuitive part most beginners get wrong: use broader categories at first. "Transportation" instead of splitting into "Gas," "Uber," "Parking," and "Tolls." You'll aggregate those sub-categories anyway when you're reviewing, and splitting them early just creates more friction with no real benefit. The only exception is fixed recurring expenses like rent or insurance — those deserve their own lines because they're predictable and high-impact.
The Dashboard Is Where People Derail
The summary page should answer one question: can I see my financial position in under thirty seconds? If you're clicking between five tabs to figure out how much you spent last month, the dashboard is doing too much work.
Use simple SUMIF formulas. Something like pulling all expense category totals by month. Don't build elaborate pivot tables on day one. A basic monthly total per category with a running annual sum is enough for most people. I've seen finance professionals over-engineer dashboards with conditional formatting, sparklines, and dynamic charts that take longer to build than the actual budgeting work. The dashboard should be boring. Boring is reliable.
Here's a practical workflow that works: every Friday afternoon, open the workbook, enter any cash or miscellaneous transactions from the week, let the formulas recalculate, and glance at the dashboard. Take fifteen minutes. That's the entire habit. If you can't sustain fifteen minutes a week, you'll never sustain an hour.
Common Pitfalls I See Repeatedly
The biggest mistake is building the workbook before deciding what you want to learn from it. You'll end up tracking thirty categories and not know why. Pick two or three metrics you actually care about — monthly discretionary spending, savings rate, debt payoff progress — and design around those. Everything else is noise.
Another issue is mismatched currency or period alignment. If your income comes in monthly but your expenses are logged weekly, the summary numbers won't line up cleanly. Decide on a consistent period upfront and stick with it. I've seen people mix net and gross income in the same workbook and then wonder why their surplus calculations looked wrong.
Automated feeds solve a lot of this but introduce new problems. Bank imports often misclassify transactions. A grocery store purchase showing up under "Entertainment" or a software subscription appearing as "Business Expenses" when it shouldn't. Build in a monthly reconciliation step where you run a quick scan for misclassified items. Ten minutes catches errors that would otherwise creep into your numbers silently.
When Finance Workbook Quick Isn't the Right Tool
If you're managing multiple business entities, complex investments, or properties with depreciation schedules, a simple finance workbook falls apart. The formulas get unwieldy, the file slows down, and you're better off with dedicated software like QuickBooks or a proper financial planning platform. This approach works best for personal finance, small freelance income tracking, or a single household budget.
There's also the question of whether you actually need this level of detail. Some people track every coffee purchase and never gain any meaningful insight from it. If your goal is simply to know whether you're saving money each month, you might need a spreadsheet with three rows instead of thirty categories. Simplicity beats comprehensiveness every time.
Maintaining the System Long Term
Every ninety days, review your categories and delete any you haven't used. Unused categories become visual clutter and make the workbook harder to navigate. I've rebuilt finance workbooks Quick several times for clients just by pruning dead categories and consolidating redundant ones. The cleaned-up versions always perform better than the originals.
Backup the file weekly. Use cloud storage with version history. Losing three months of data because your hard drive failed is a preventable mistake and one I've had to help clients recover from more than once. Google Sheets or OneDrive with automatic save and version tracking handles this without any extra effort on your part.
The workbook itself should live in a clear folder structure with a naming convention that includes the year and month. FinanceWorkbook_QQ_2025_W06.xlsx is easier to find than Budget_Final_v3_real.xlsx. File organization seems trivial until you're searching through twelve versions of the same document and can't tell which one is current.
Gallery Finance Workbook Quick
Personal Finance Workbook for Beginners - Retire By 45
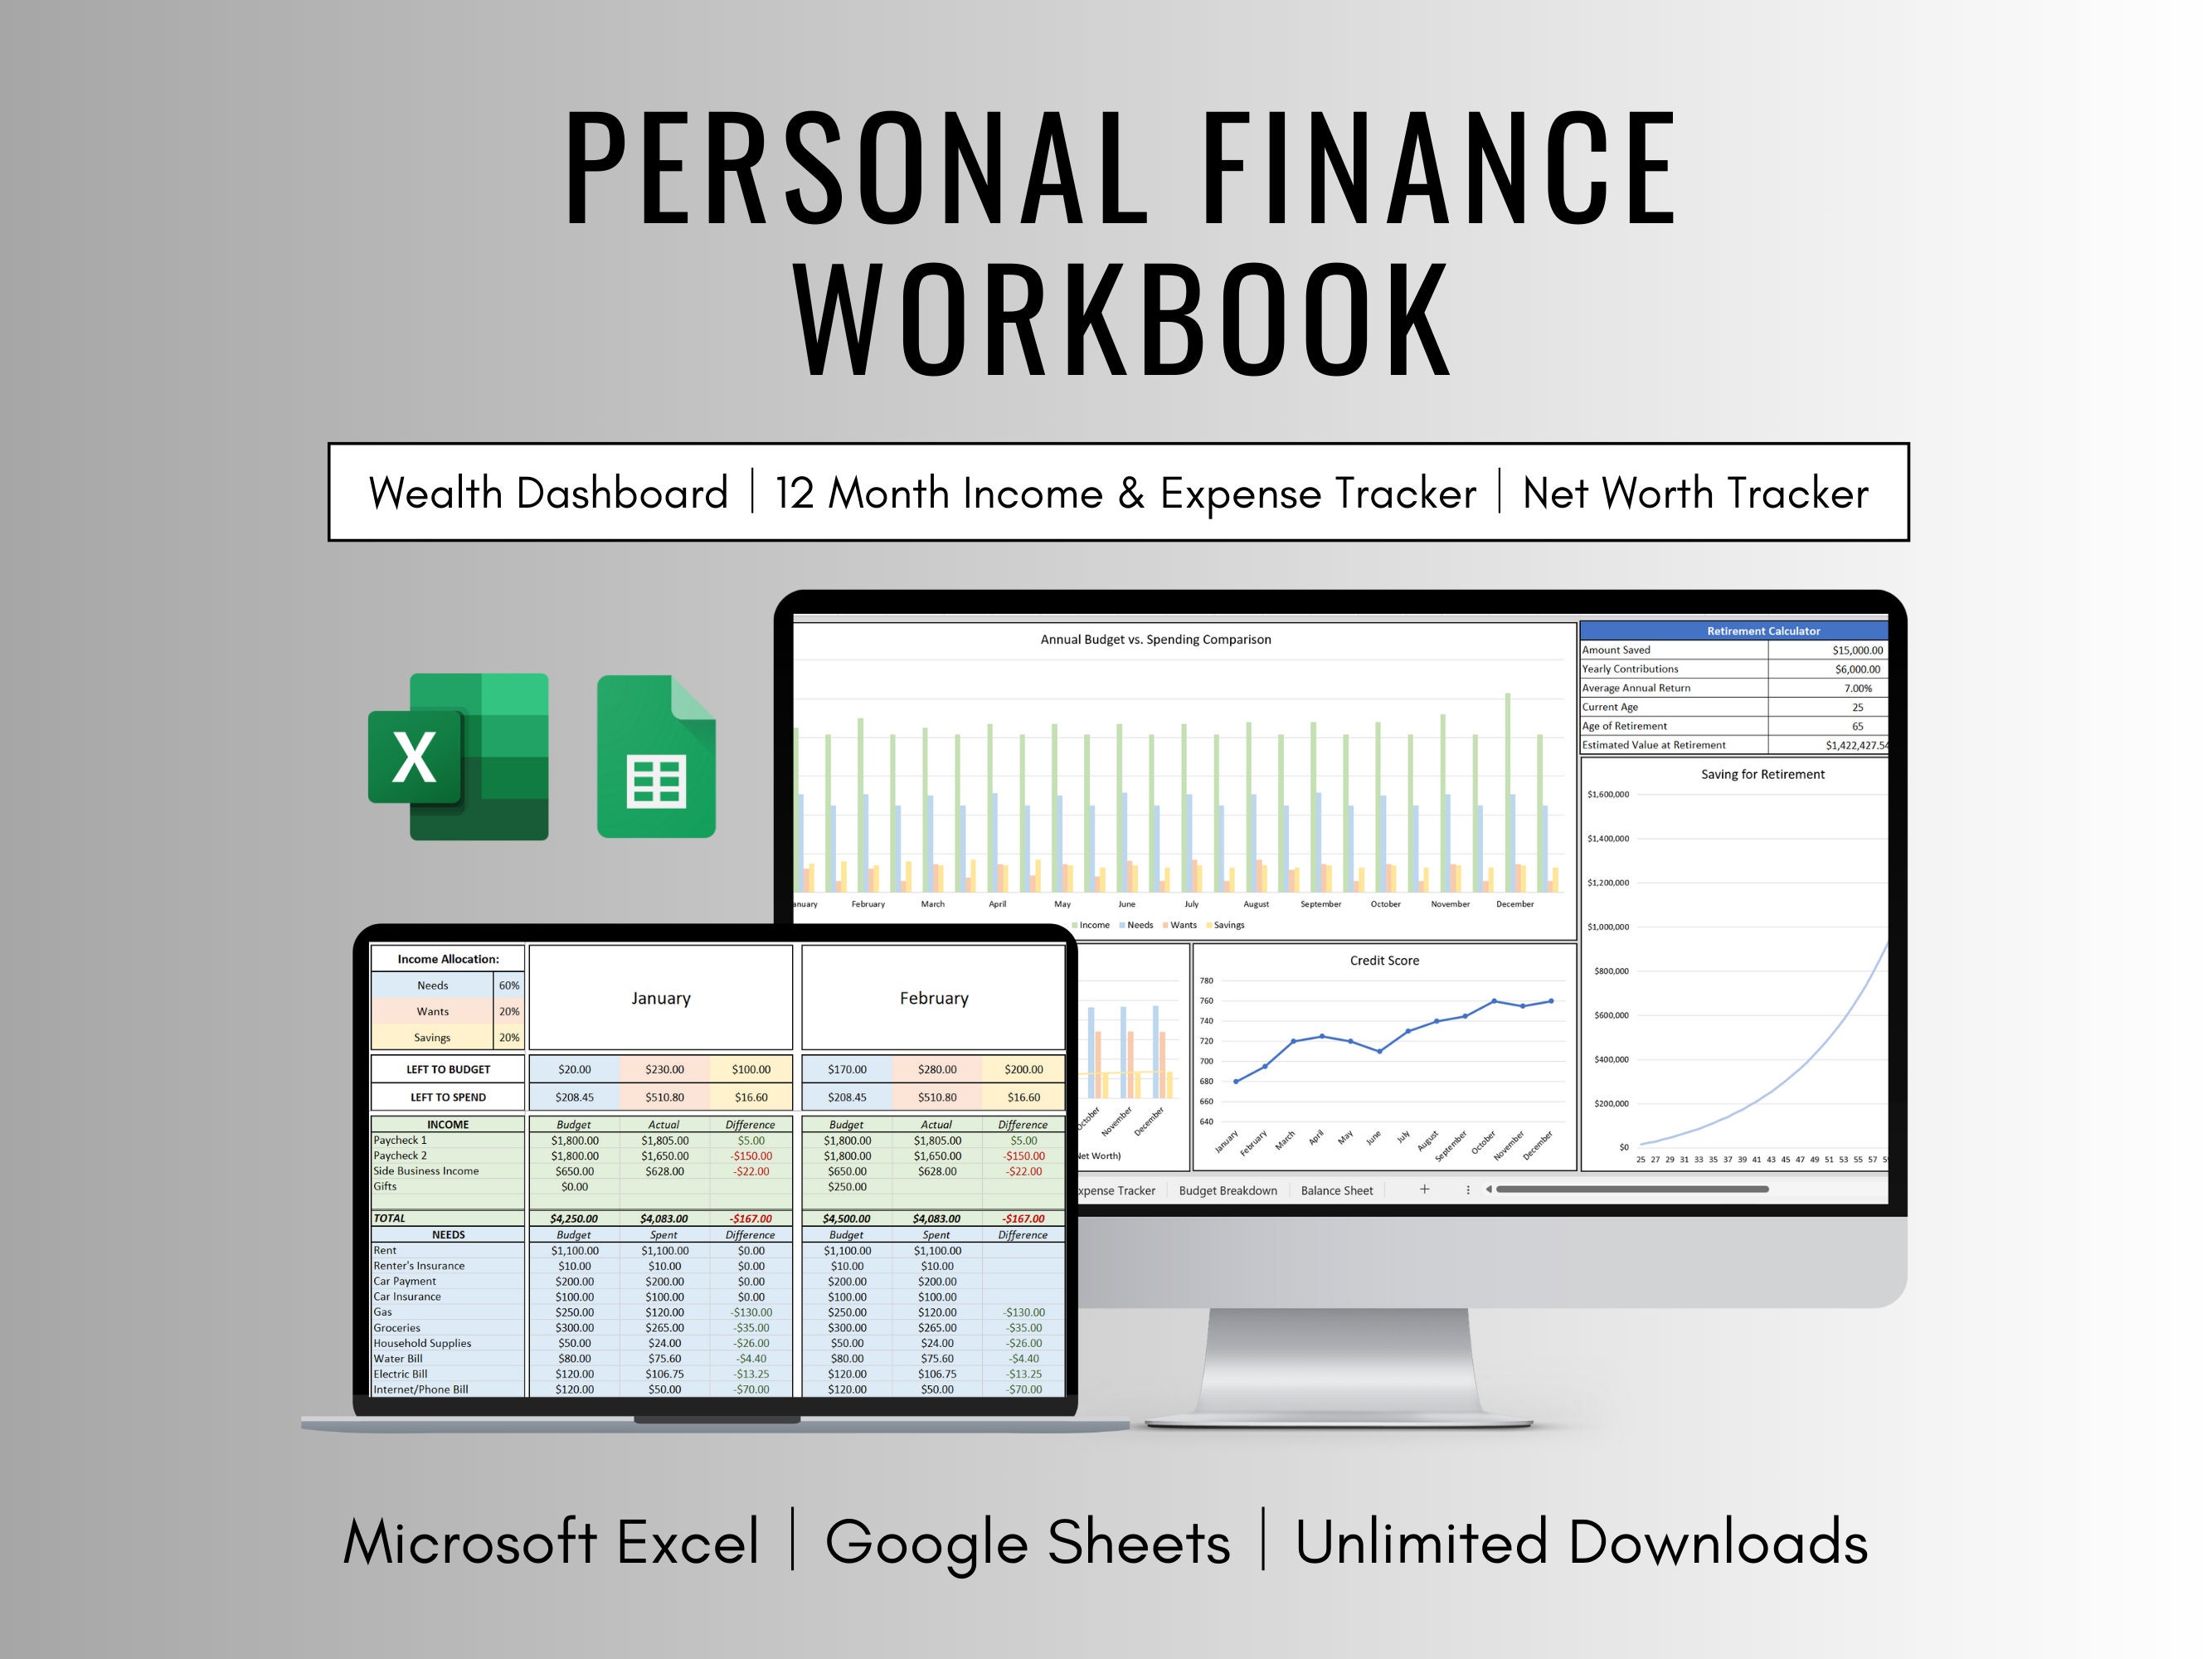
Personal Finance Workbook Spreadsheet for Excel and Google Sheets ...
Finance Workbook
A5 Finance Planner, Money Workbook, Personal Finance - Etsy
Budgeting Workbook Finance Monthly & Weekly Budget Planner: Simple and ...