Working Through Financial Accounting Problems Without Losing Your Mind
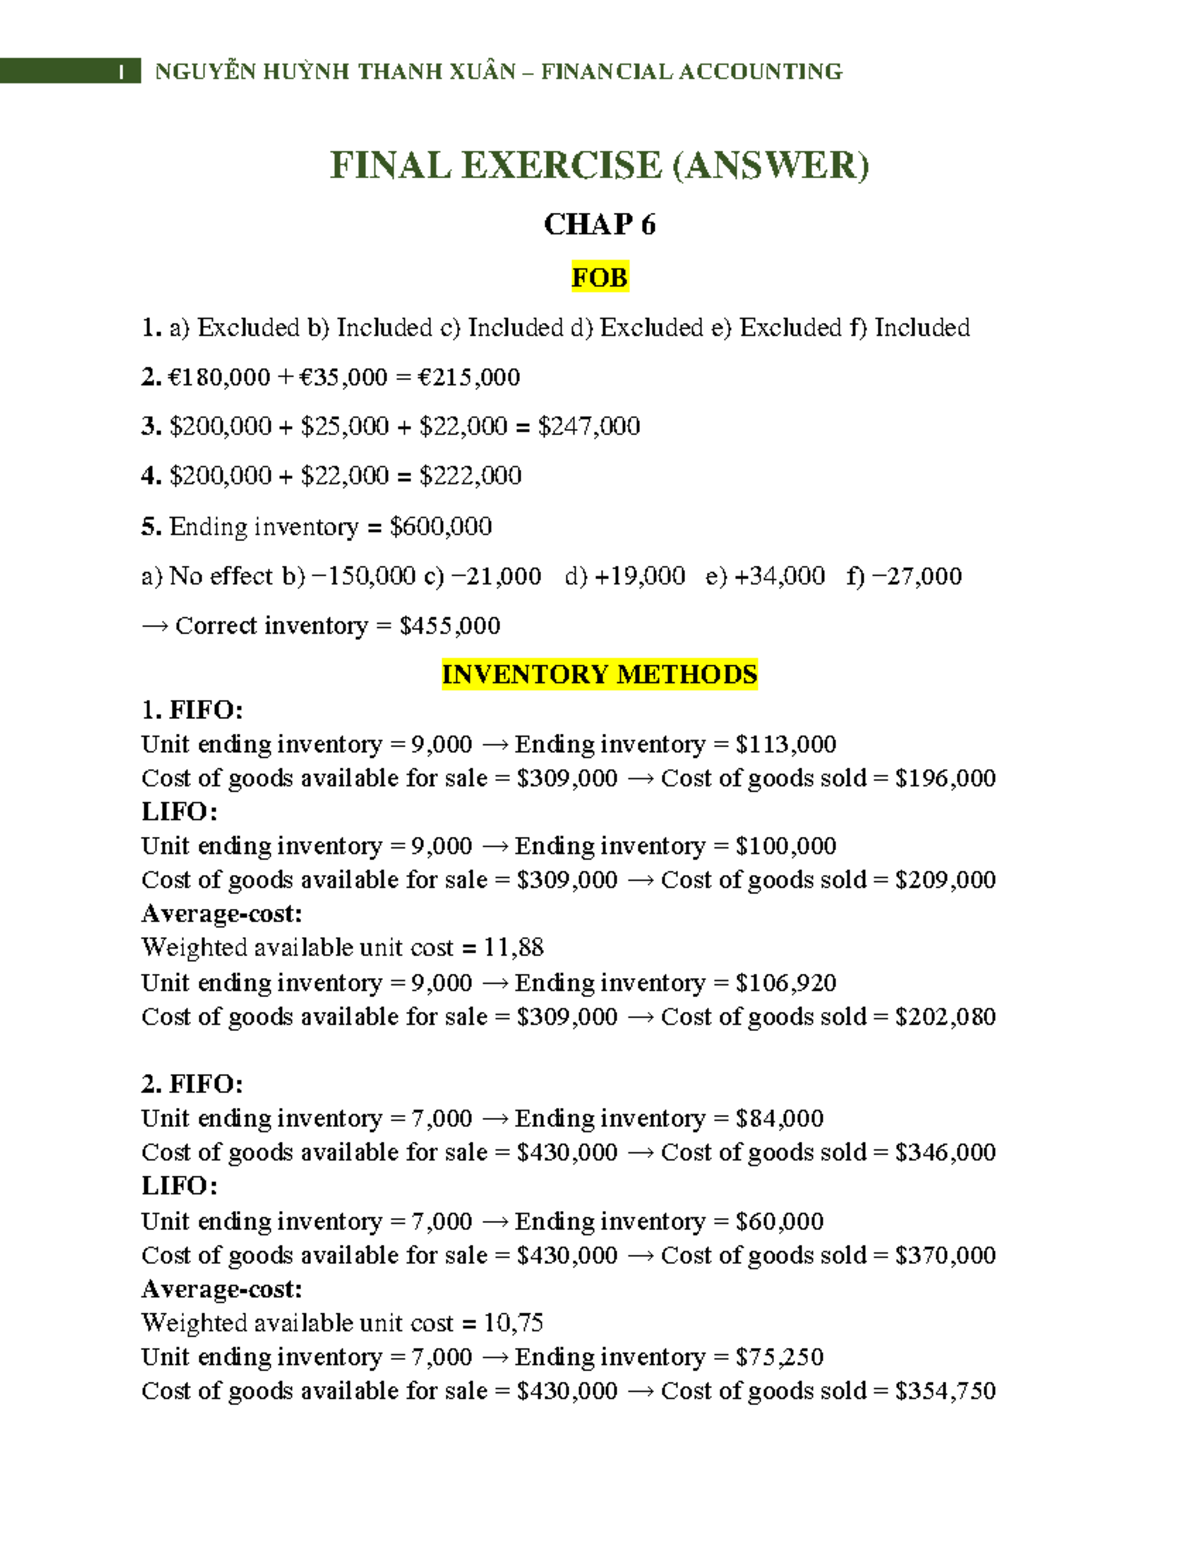
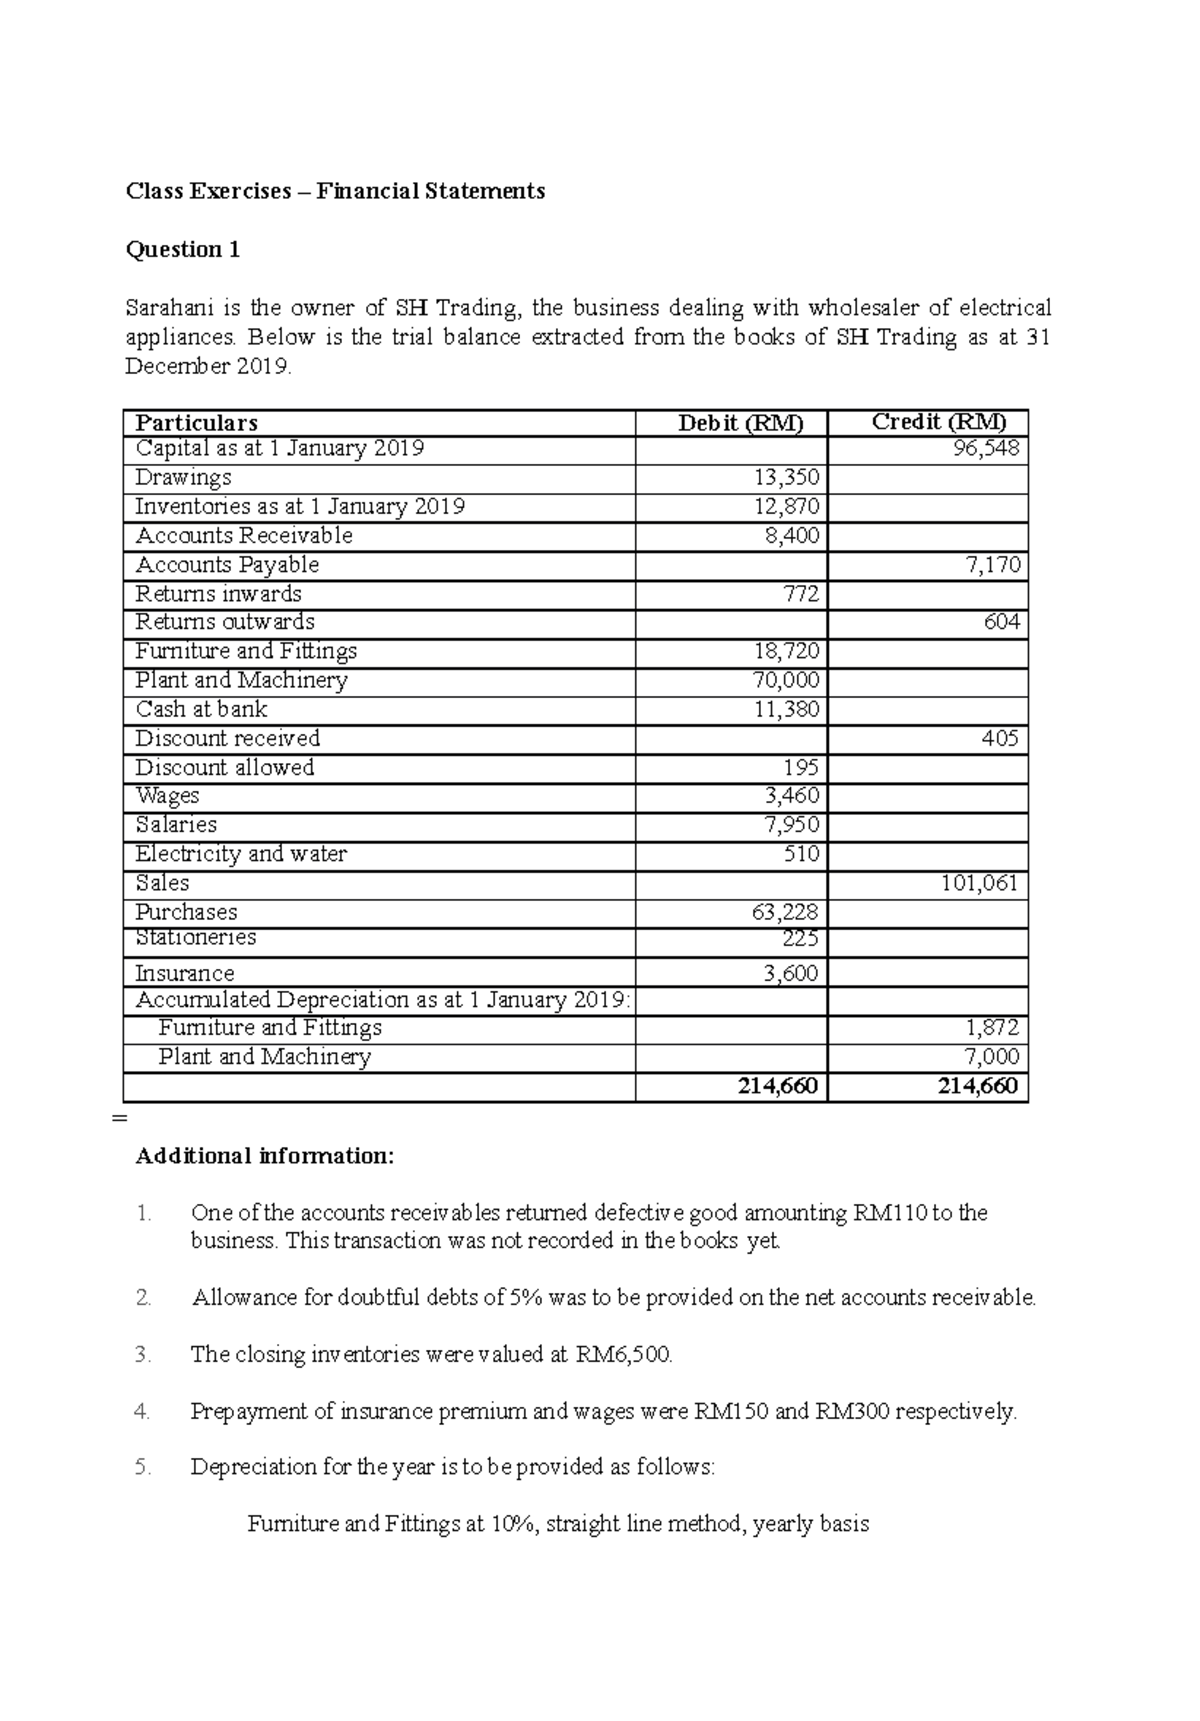
I spent three years as a teaching assistant for introductory accounting courses before I started hating the standard textbook approach. The problem isn't that the exercises are bad. It's that most students treat them like puzzles to solve rather than simulations of real work. Here's what actually helps, and why.Start with the adjusting entries. That's where 80% of the mistakes happen, and it's not because the concept is hard. It's because students rush into closing entries without double-checking whether the adjustment itself was correct. I used to see the same pattern every semester: someone would debit prepaid insurance and credit cash for $3,600, then go straight to the balance sheet without verifying what portion actually expired during the period. The answer key would say $300 in expense and $3,300 remaining asset. They'd put $3,600 expense. Game over. The fix is simple but most people skip it. After writing out an adjusting entry, always pause and ask what the account balances should look like after that entry. Prepaid insurance starts at $3,600. You expensed $300. The balance must be $3,300. Check that before moving on. The best free resources aren't where you'd expect. Most students google the topic and land on generic homework help sites that either show incomplete work or charge for access to what should be free. Here's what I actually recommend. OpenStax has a free principles of accounting textbook with end-of-chapter problems and a separate solution manual. It's not perfect. Some of the scenarios are dated, and the answer explanations can be thin on the tricky ones. But the problems are clean, the formatting is consistent, and there's no paywall. You can download the whole thing as a PDF or use it online. I've used it with students who needed practice on deferred revenue recognition, and the Chapter 5 problems alone are worth an afternoon.
For more advanced exercises, the AICPA's sample questions are genuinely useful. They're not free in the sense that you need to create an account, but they give you a realistic sense of what professional exams actually look like. The multiple-choice format is different from textbook problems, which forces you to think differently about the same material. I noticed students who only practiced with textbook solutions struggled unexpectedly with the AICPA samples, even though they knew the content. The gap is in how the question is framed, not what you need to know. There's also the SEC's EDGAR database if you want real financial statements to work with. Download a 10-K from any public company, try to reconstruct the adjusting entries from the footnotes, then check your work against the actual notes. This is harder than any textbook problem and infinitely more useful. I did this exercise with a student who was struggling with lease accounting. We pulled a recent 10-K from a retailer with operating leases, worked through Note 7, and she finally understood what "right-of-use asset" actually meant in practice. Not because I told her, but because she had to compute it herself from real numbers.
The Wrong Way Most People Practice
Reading the solution before attempting the problem is the fastest way to waste time. I understand the temptation. You get stuck on a depreciation schedule and the clock is ticking. But reading the answer first creates an illusion of competence. You nod along and think you understand, then you close the book and can't start from zero. The correct approach is painful but necessary: attempt the problem fully before looking at anything. Struggle for at least ten minutes. Write out what you know, identify what you're missing, then check your work. The struggle is where the learning happens, not the verification. Another common mistake is practicing only one type of problem at a time. Textbooks encourage this with their chapter structure. You do twenty bad debt problems, then move to inventory. This creates narrow skill development. Real exams and real work mix everything. I started having my students do randomized problem sets after midterm, pulling from multiple chapters. The improvement in their ability to identify which technique to apply was noticeable within two weeks. They stopped automatically reaching for the last method they'd practiced and started actually reading the problem first.
Get the Full Details

Specific Edge Case That Tripped Up Everyone
Here's something I ran into repeatedly that the textbooks handle poorly. Bond amortization when the market rate changes partway through the bond's life due to a refinancing scenario. Most textbooks show a clean issuance at par, premium, or discount and then a straightforward amortization table. They rarely test what happens when you have to account for a bond modification or early extinguishment mid-period. I created a problem where a company issued bonds at a 6% coupon when the market rate was 8%, recorded the discount over two years using the effective interest method, then refinanced at a 5% market rate with a 4% coupon. The question was what gain or loss to recognize and how to adjust the remaining amortization. Half the class couldn't get past the first step. They knew how to amortize a bond discount. They knew the basic formula for gain on extinguishment. But combining them required tracking the carrying value at the exact date of refinancing, computing the difference between that carrying value and the present value of the new bond's remaining cash flows, and then deciding whether the old discount amortization continued or reset. The answer isn't in any single chapter. It's in stitching three concepts together. I found the closest available practice problem in the intermediate accounting sections of several commercial workbooks, but none with complete step-by-step answers. I ended up writing my own solution and sharing it with the class, which became the most saved document in our shared drive by far.
What the Answer Keys Get Wrong
Sometimes the official answers are wrong. Not often, but often enough that you need to learn how to spot it. I caught an error in a widely used textbook's solution manual for a consolidation problem. The answer computed the non-controlling interest share using the subsidiary's book value instead of fair value at acquisition. The problem clearly stated there was a $50,000 equipment undervaluation. The solution ignored it entirely. The correct NCI should have been $185,000, not $135,000. A student emailed me asking why her answer didn't match. I verified the error, showed her the correct calculation, and had her email the professor with a screenshot of the relevant problem text. The correction made it into the next printing. This is why blind trust in answer keys is dangerous. The process matters more than matching a number. If your work is logically sound but your final answer differs from the key, investigate before assuming you're wrong. Recalculate once. Check your assumptions. If they hold, you may have found a genuine error or a different valid interpretation. I've lost count of how many times a student convinced themselves they were wrong when the textbook was.
Building a Practice Routine That Actually Works
Daily practice beats cramming. Ten focused problems a day is better than fifty on Sunday. Your brain needs sleep to consolidate the procedural knowledge involved in journal entries and T-account analysis. I tracked my own practice schedule across two semesters. Days when I did problems within 24 hours of learning the concept, retention was roughly 85% on quizzes two weeks later. Days when I let a topic sit for four or five days before practicing, retention dropped to about 40%. The difference wasn't intelligence or effort. It was purely timing. Mix easy and hard problems. Easy problems build speed and confidence. Hard problems build depth. If you only do easy problems, you'll breeze through homework and fall apart on exams. If you only do hard problems, you'll burn out and miss the foundational skills. The ratio I found most effective was about 60% medium difficulty, 25% easy, and 15% hard. The easy problems keep you moving. The hard ones force you to adapt. When you get a problem wrong, don't just read the correction and move on. Rewrite the entire problem from scratch without looking at anything, then solve it again. This takes twice as long but the retention advantage is massive. I made a rule with my students: three wrong answers on the same concept triggers a full rewrite session. Most of them hated it at first. Every single one of them reported it was the reason they finally passed the midterm.
Limitations and When This Approach Fails
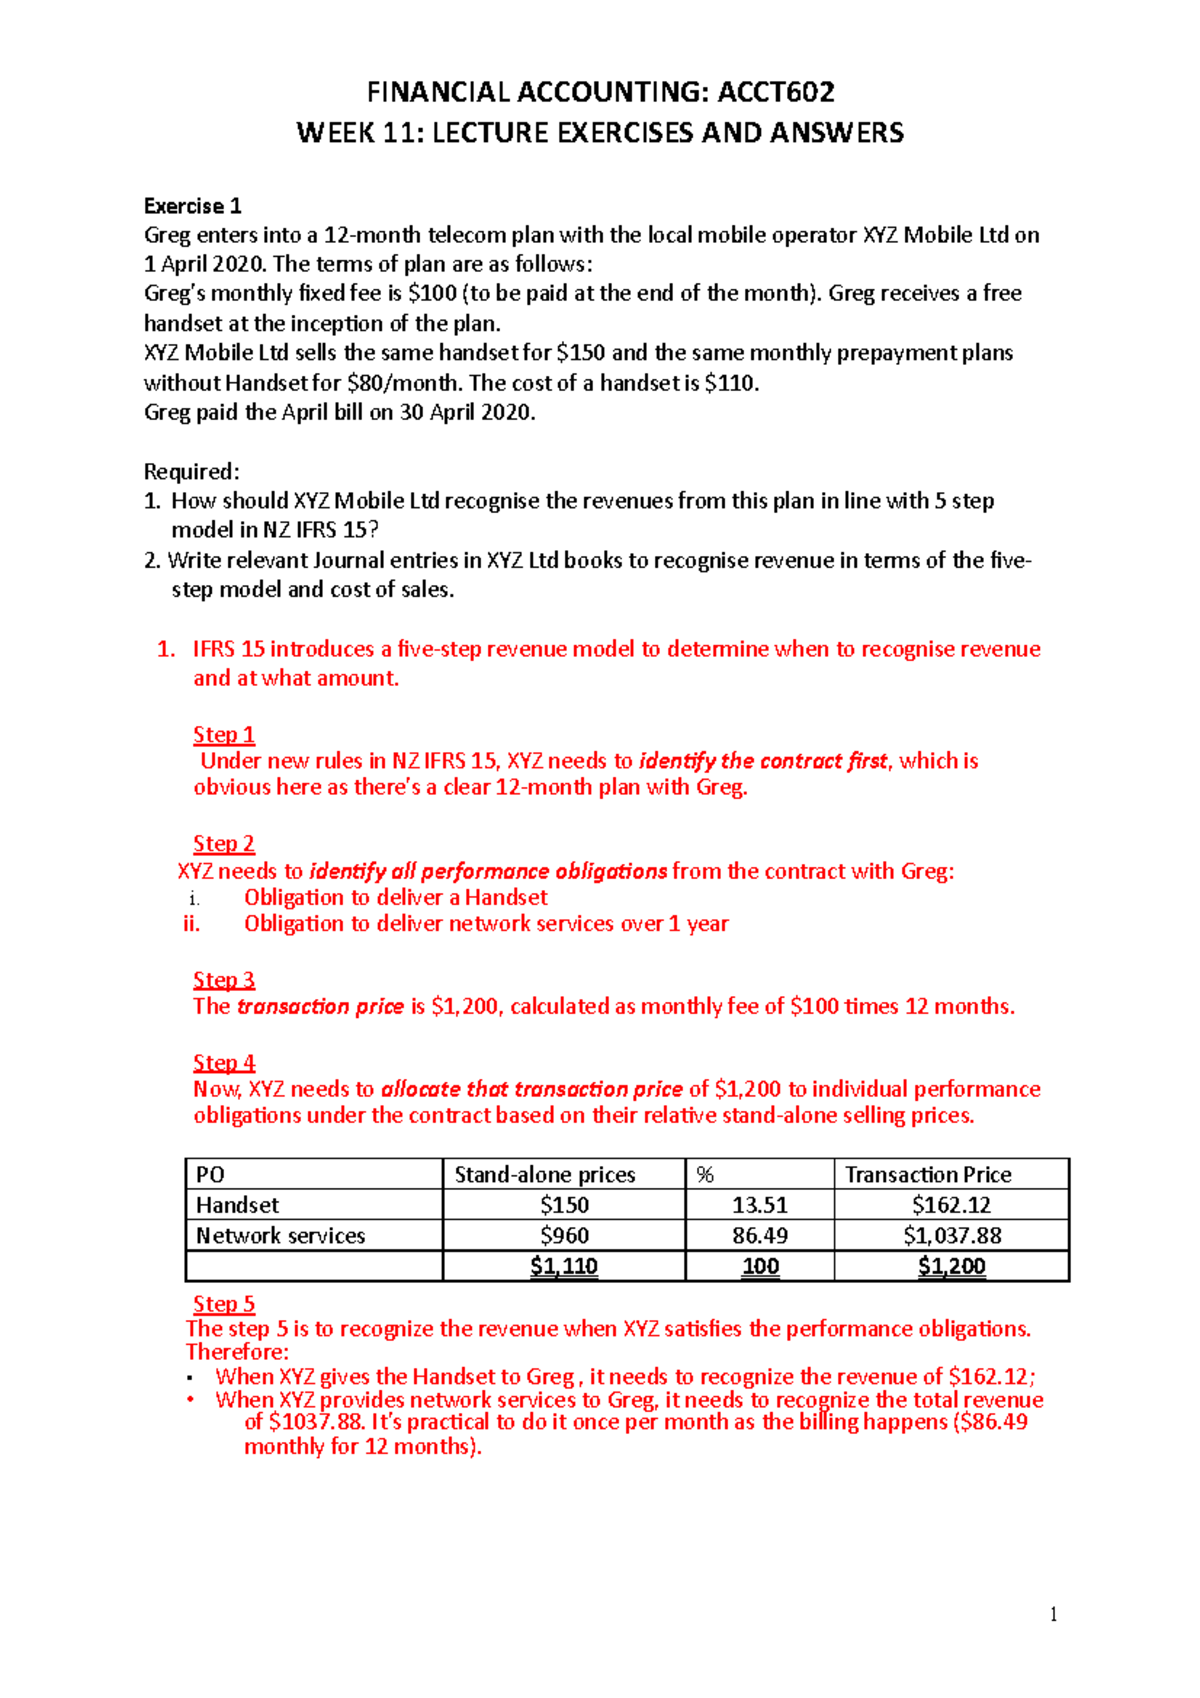
Self-study through exercises has real limits. You can practice journal entries until you're fast, but you won't develop the professional judgment needed for situations where the textbook doesn't specify the right answer. Revenue recognition under ASC 606, for example, involves estimating variable consideration, constraining estimates, and allocating transaction prices across performance obligations. The exercises give you clean scenarios with clear milestones. Real companies deal with ambiguity, incomplete information, and competing interpretations. No amount of standard exercises prepares you for that. Also, answering at the expense of understanding. This is a real risk with online answer databases. Some students use them as lookup tools rather than verification tools. They solve half the problem, check the answer, fill in the rest. This produces correct-looking homework and zero actual learning. The workaround is strict self-enforcement: no checking until the entire problem is done, even if you suspect you're wrong. The discomfort of uncertainty is temporary. The consequence of fake competence lasts through the exam. Finally, exercises can't replace understanding the underlying economic event. A depreciation exercise teaches you to allocate cost over time. It doesn't teach you why an asset loses value, when replacement is more appropriate than repair, or how tax law interacts with book treatment. Those questions matter in practice and they're almost never tested in standard exercises. If you're studying purely for an exam, this gap may not hurt you. If you're studying to actually do accounting work, you'll hit it eventually.