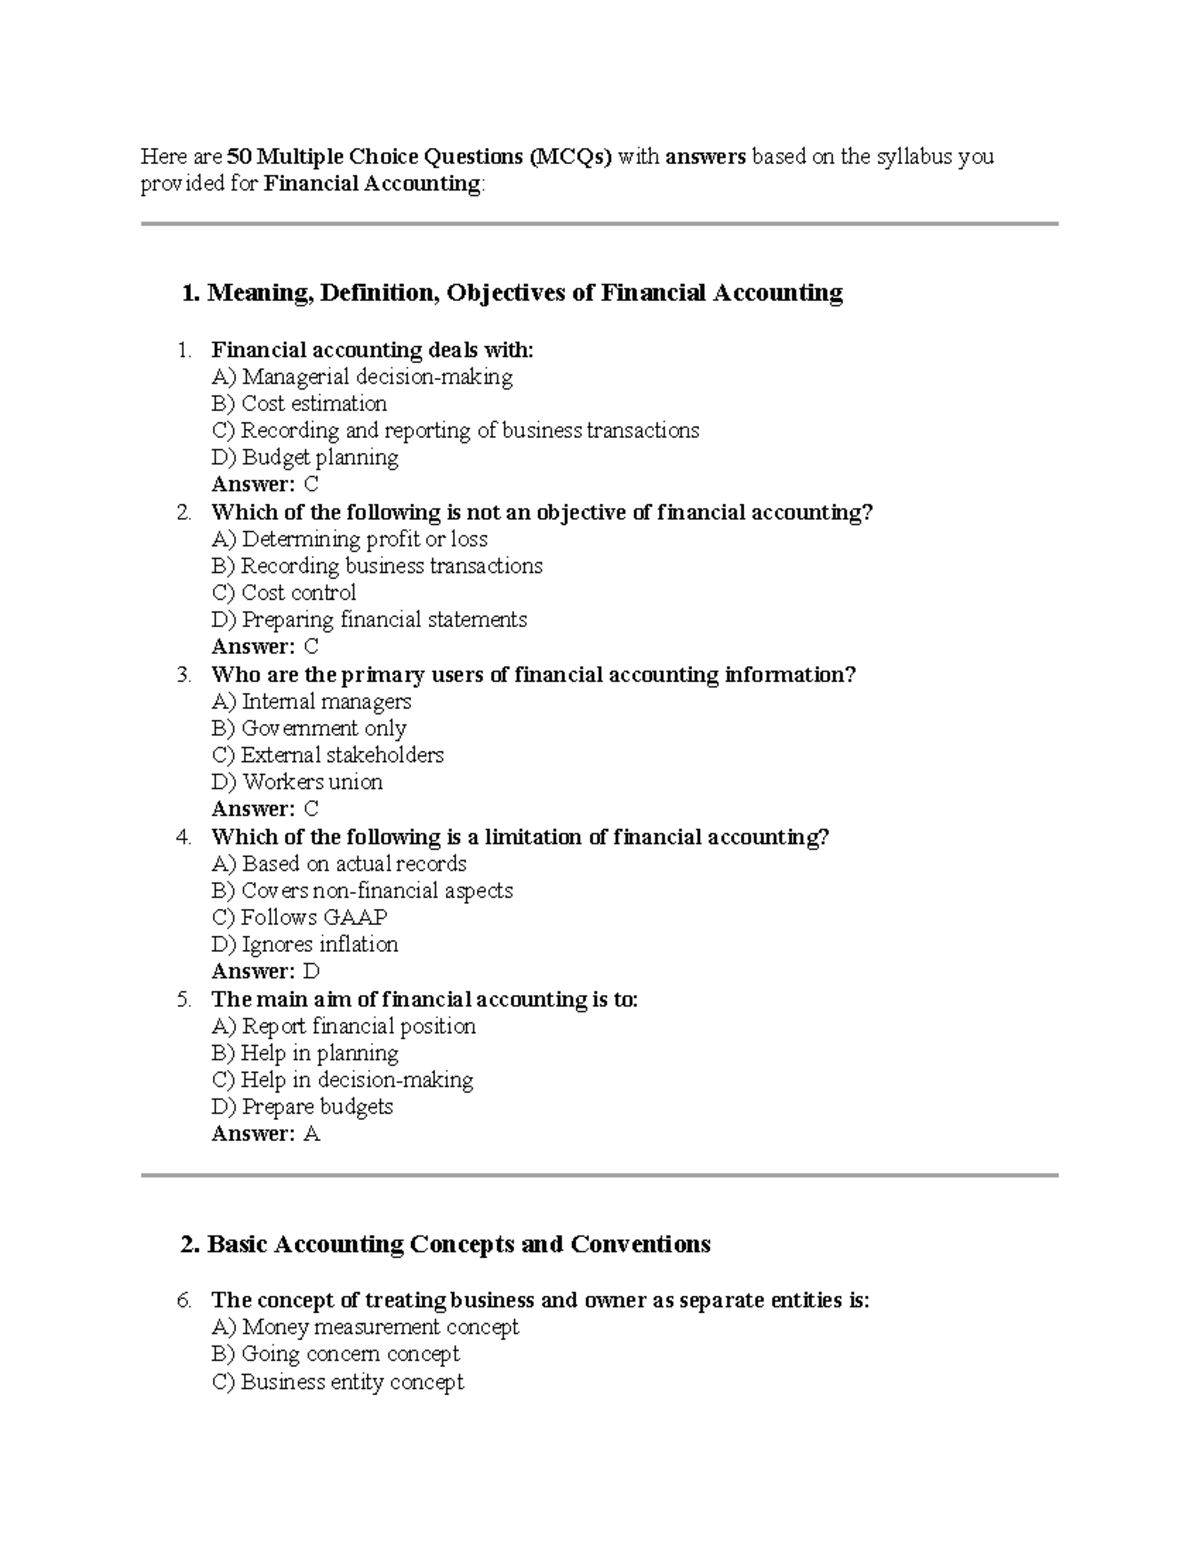
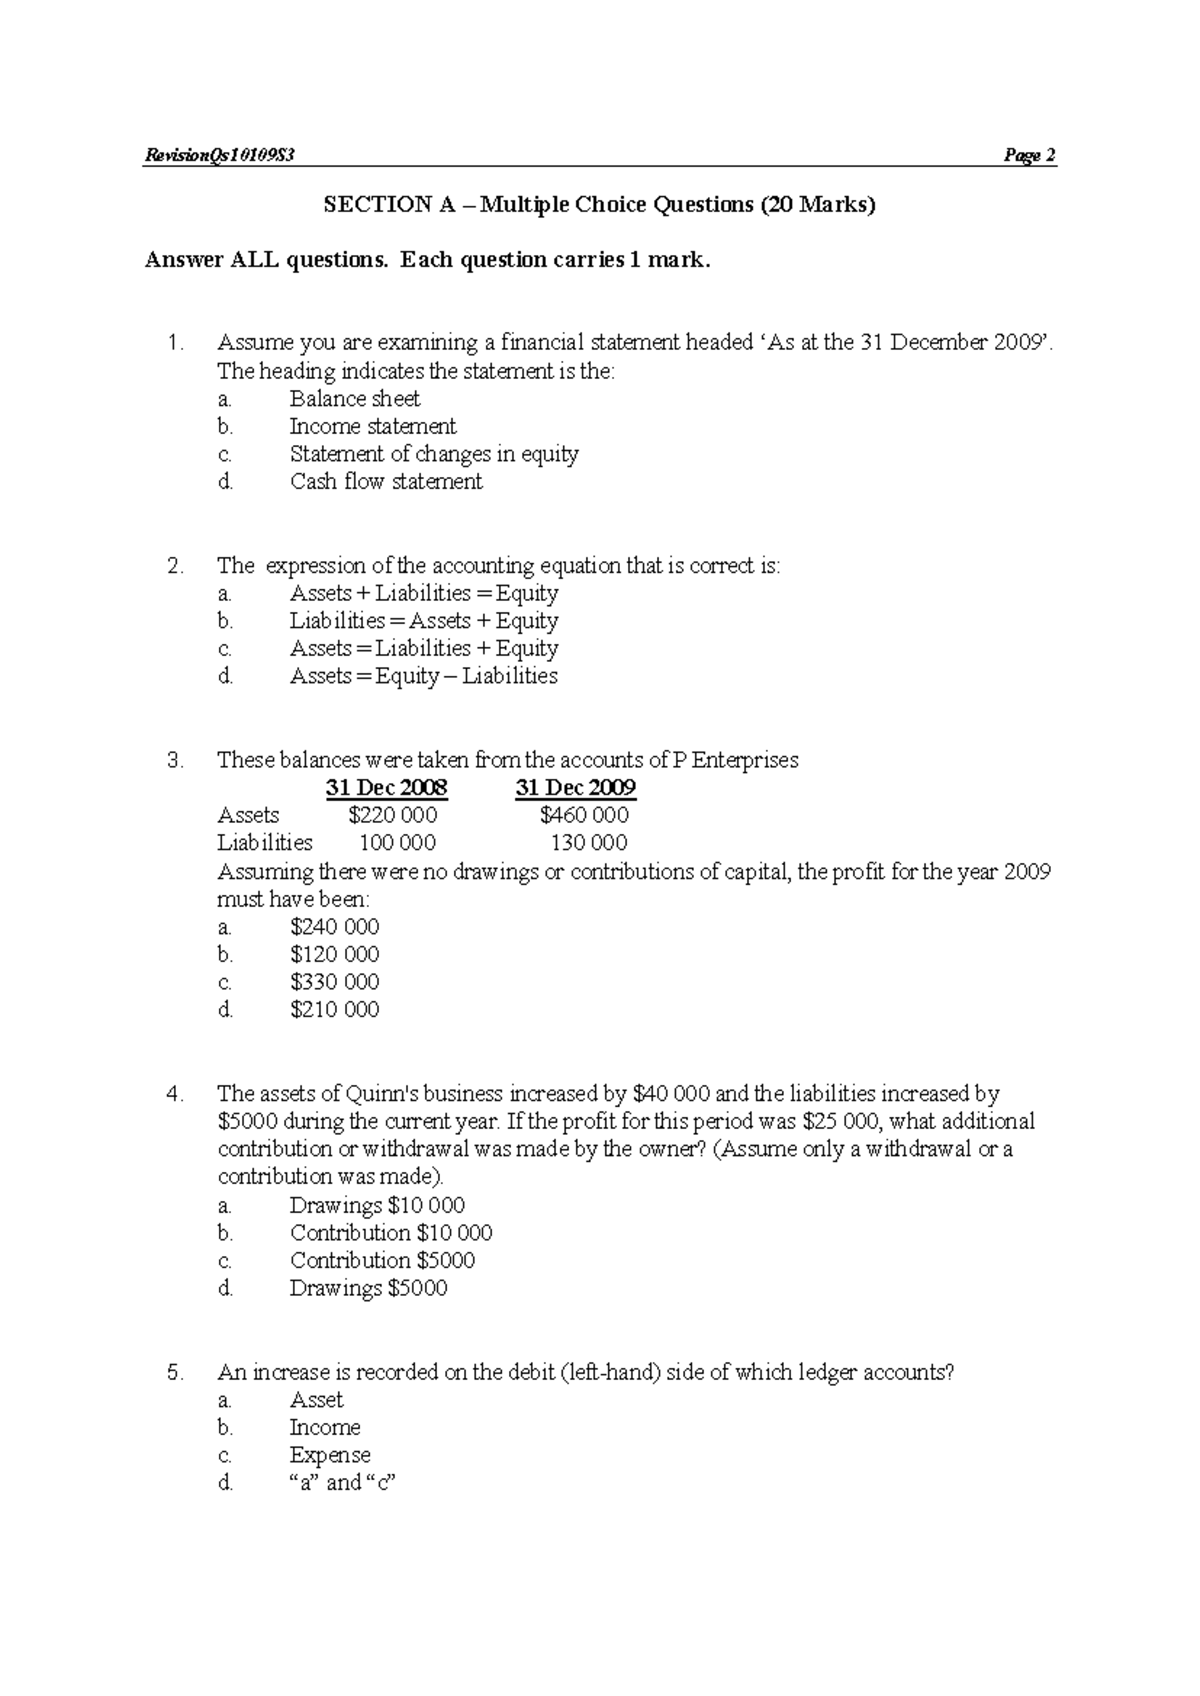
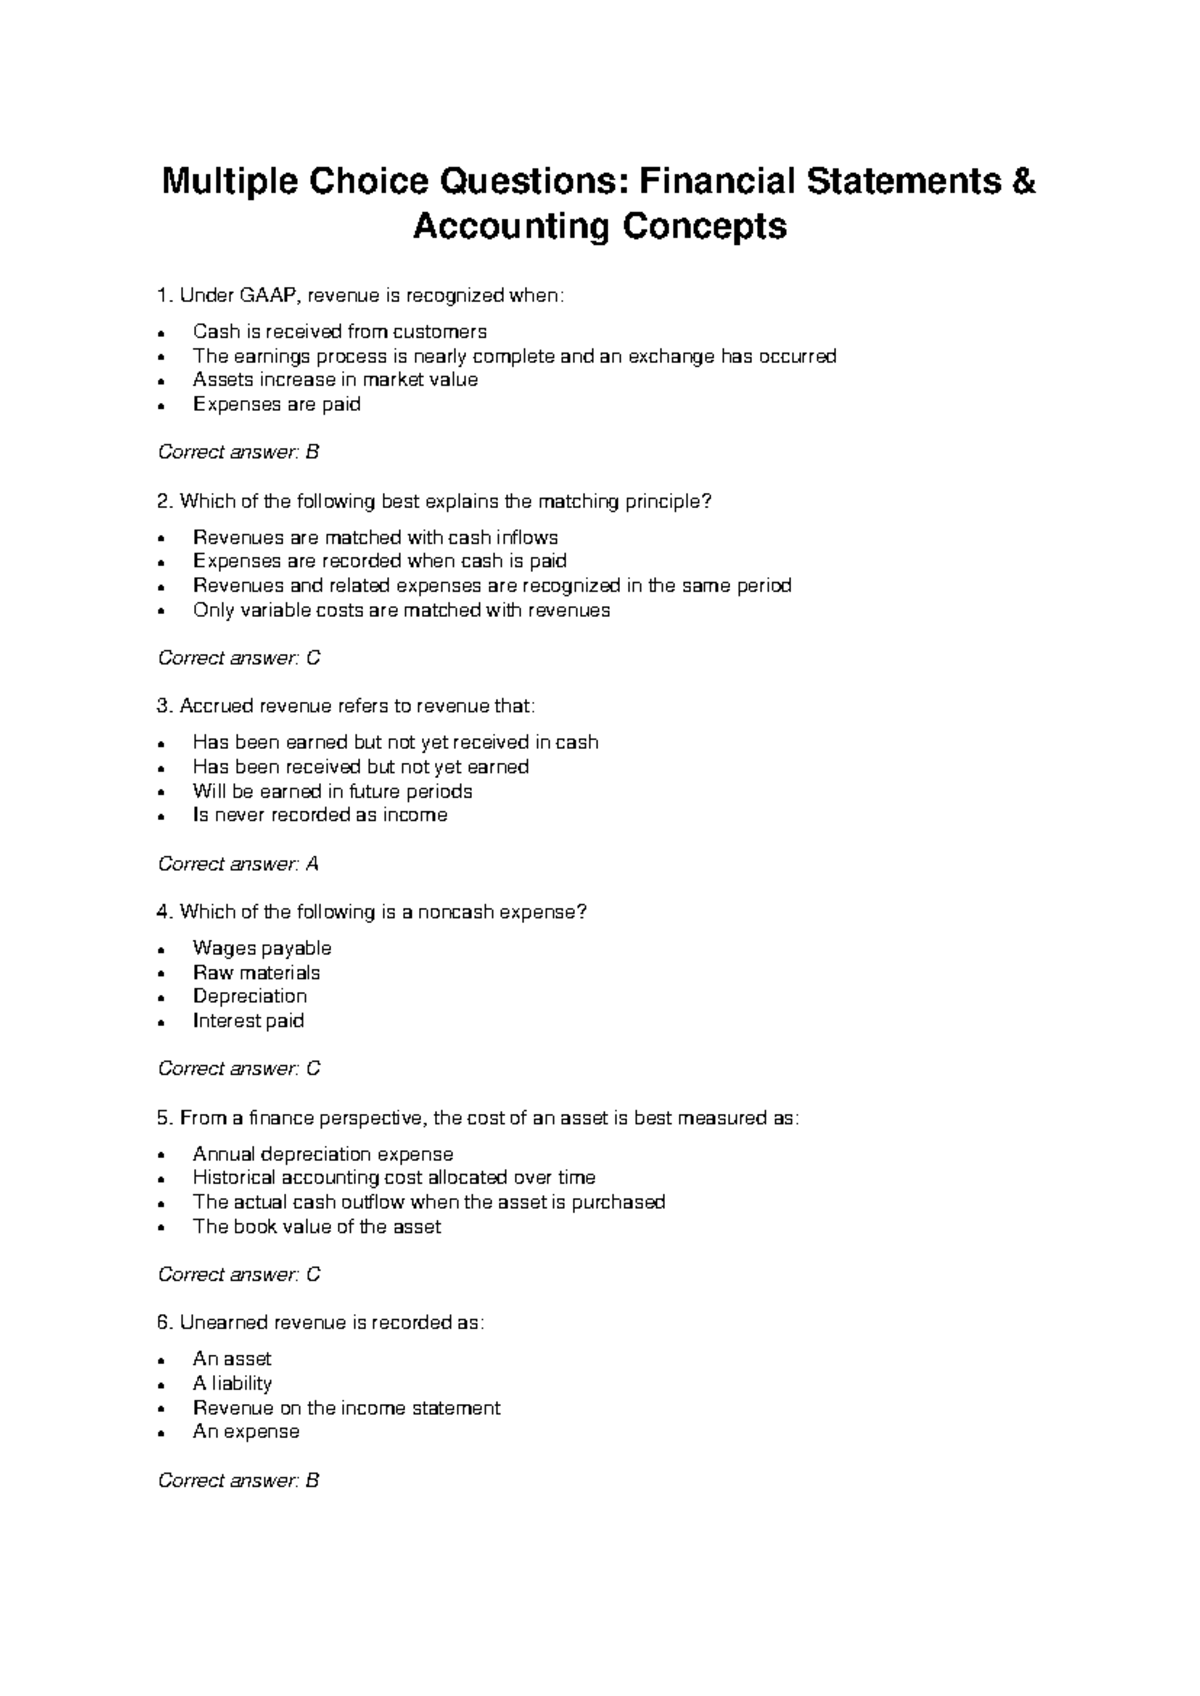
Working with Financial Accounting Multiple Choice Questions
I keep coming back to these because they're the most practical way to check your understanding without the fluff that textbooks tend to pile on. The format is blunt. You pick an answer, you move on. There's no room for half-explaining your way through. There are plenty of question banks out there. Most of them are recycled from older test prep publishers. A few are solid. The ones I recommend are the ones that cite specific IFRS or US GAAP standards alongside each answer. If a question says something about depreciation methods but doesn't reference ASC 360 or IAS 16, it's probably outdated or written by someone who hasn't done the reading. I spent too many hours in my first year wrestling with question banks that had answers based on 2014 standards. Once I learned to check the standard references, my accuracy went from roughly 62% to about 81% over a few weeks. The best sources I've used are the CPA review materials for financial accounting sections, along with the ACCA and CIMA question repositories. They're paid, but they're also the most current. Free collections tend to have typos in the numbers, mismatched answer keys, and questions that contradict each other on principle.
How to use them effectively
Don't just grind through questions. That's the mistake most people make. You'll finish a hundred questions and still not know why you got half of them wrong. The process should work more like this: pick a topic, take fifteen to twenty questions on it, then go back and understand every single incorrect answer before moving on. When I was going through this myself, I kept running into a specific problem with questions involving intercompany eliminations in consolidated financial statements. The answers would look identical across two different options because the transaction amounts and percentage holdings were subtly different. One question in particular had a 75% ownership figure where the subsidiary had unrealized inventory profits, and the other option changed the ownership to 80% but kept everything else the same. My instinct was to match the numbers to memory instead of recalculating from scratch, and I picked the wrong answer three times in a row. The workaround was straightforward. I started writing out the elimination entry on scrap paper for every consolidation question, even the ones I felt confident about. It added maybe forty seconds per question but eliminated the guesswork entirely. I stopped missing consolidation questions after about a week of doing that. Another thing that helps is tracking your errors by concept, not by test. If you're getting intercompany transactions wrong, you need to close that gap before you touch revenue recognition. The questions are designed to build on each other in the real exams, and the same structure applies when you're self-studying.
Common traps in these questions
The hardest part about financial accounting MCQs is that the distractors are usually plausible. They're not random wrong answers. Each one is built from a real accounting concept applied slightly incorrectly. Here are the patterns I've seen repeatedly: Questions that mix up timing. Revenue recognition under ASC 606 or IFRS 15 will often have an answer that sounds right if you apply the five-step model in the wrong order. You'll see cases where the performance obligation is identified correctly but the transaction price is allocated based on standalone selling price before the contract is even evaluated for enforceability. The wrong answer will still sound technically correct until you trace the sequence. Lease accounting questions have the same issue. Under ASC 842, a lease classification depends on several criteria, and the test writers love to change one variable while keeping everything else identical. A question might say the lease term is nine years with a ten-year useful life and no transfer of ownership. That's clearly an operating lease. Then they swap in a bargain purchase option and suddenly it becomes a finance lease. The trap is assuming the lease liability calculation is the same regardless of classification. It isn't. The discount rate and amortization pattern differ.
Get the Full Details

Impairment questions under IAS 36 are another area where the wrong answers are almost always defensible. The recoverable amount is the higher of fair value less costs of disposal and value in use. Most students will calculate one of those two figures and pick it without checking whether the other is higher. I've lost points on that exact mistake more than once, and it's annoying because both calculations are technically correct, just incomplete.
What these questions can't do for you
Here's the honest part. Multiple choice questions will never teach you how to journalize a complex transaction from a word problem if you've never practiced the mechanics. They test recognition, not production. You can score 90% on a question bank and still freeze when asked to prepare a full set of financial statements from a trial balance. They also don't capture the judgment calls that actually come up in practice. Estimating bad debt allowances under CECL involves forward-looking loss rates that no MCQ can replicate accurately. Lease classification sometimes requires interpretation that depends on facts not present in a standardized question. If your goal is exam readiness, the MCQs are useful. If your goal is practical competence, you need to pair them with scenario-based exercises.
A quick note on answering strategy
Read the entire question before looking at the answers. Test writers hide qualifiers at the end. "Which of the following is NOT..." is extremely common, and it's easy to lock onto the first answer that looks correct and skip the word not. I make a habit of circling negation words before I start processing anything else. It's a small step but it prevents a noticeable number of careless errors. When you're down to two choices and you don't know, eliminate the one that relies on the narrowest assumption. The broader answer that fits multiple scenarios is usually the safer bet, unless the question is specifically asking for the most precise application of a rule. I use these questions as a diagnostic tool more than anything else now. I run through a short set at the start of a study session to identify what I'm rusty on, then I focus my time on reading and practice problems for that topic. It's more efficient than treating every question the same way, and it cuts my study time by roughly half compared to the approach I used when I first started.