Financial Advisor Workflow Templates — what they actually do and when they break
Most people buy templates because they want to look professional. The truth is that a financial advisor workflow template is just a structured checklist that forces you through a sequence of tasks before you sign a client off. It exists because the default behavior of advisers is to skip compliance steps, and someone with enough paranoia eventually wrote down the right order of operations.
I keep running into the same problem. An adviser downloads a gorgeous template, imports it into their CRM, and thinks they are done. Two weeks later, half the fields are empty, the document is stored locally instead of in the shared drive, and the next reviewer cannot find the risk disclosure form. The template is technically a file, but in practice it is a fragile paper chain that collapses under real load.
The basics
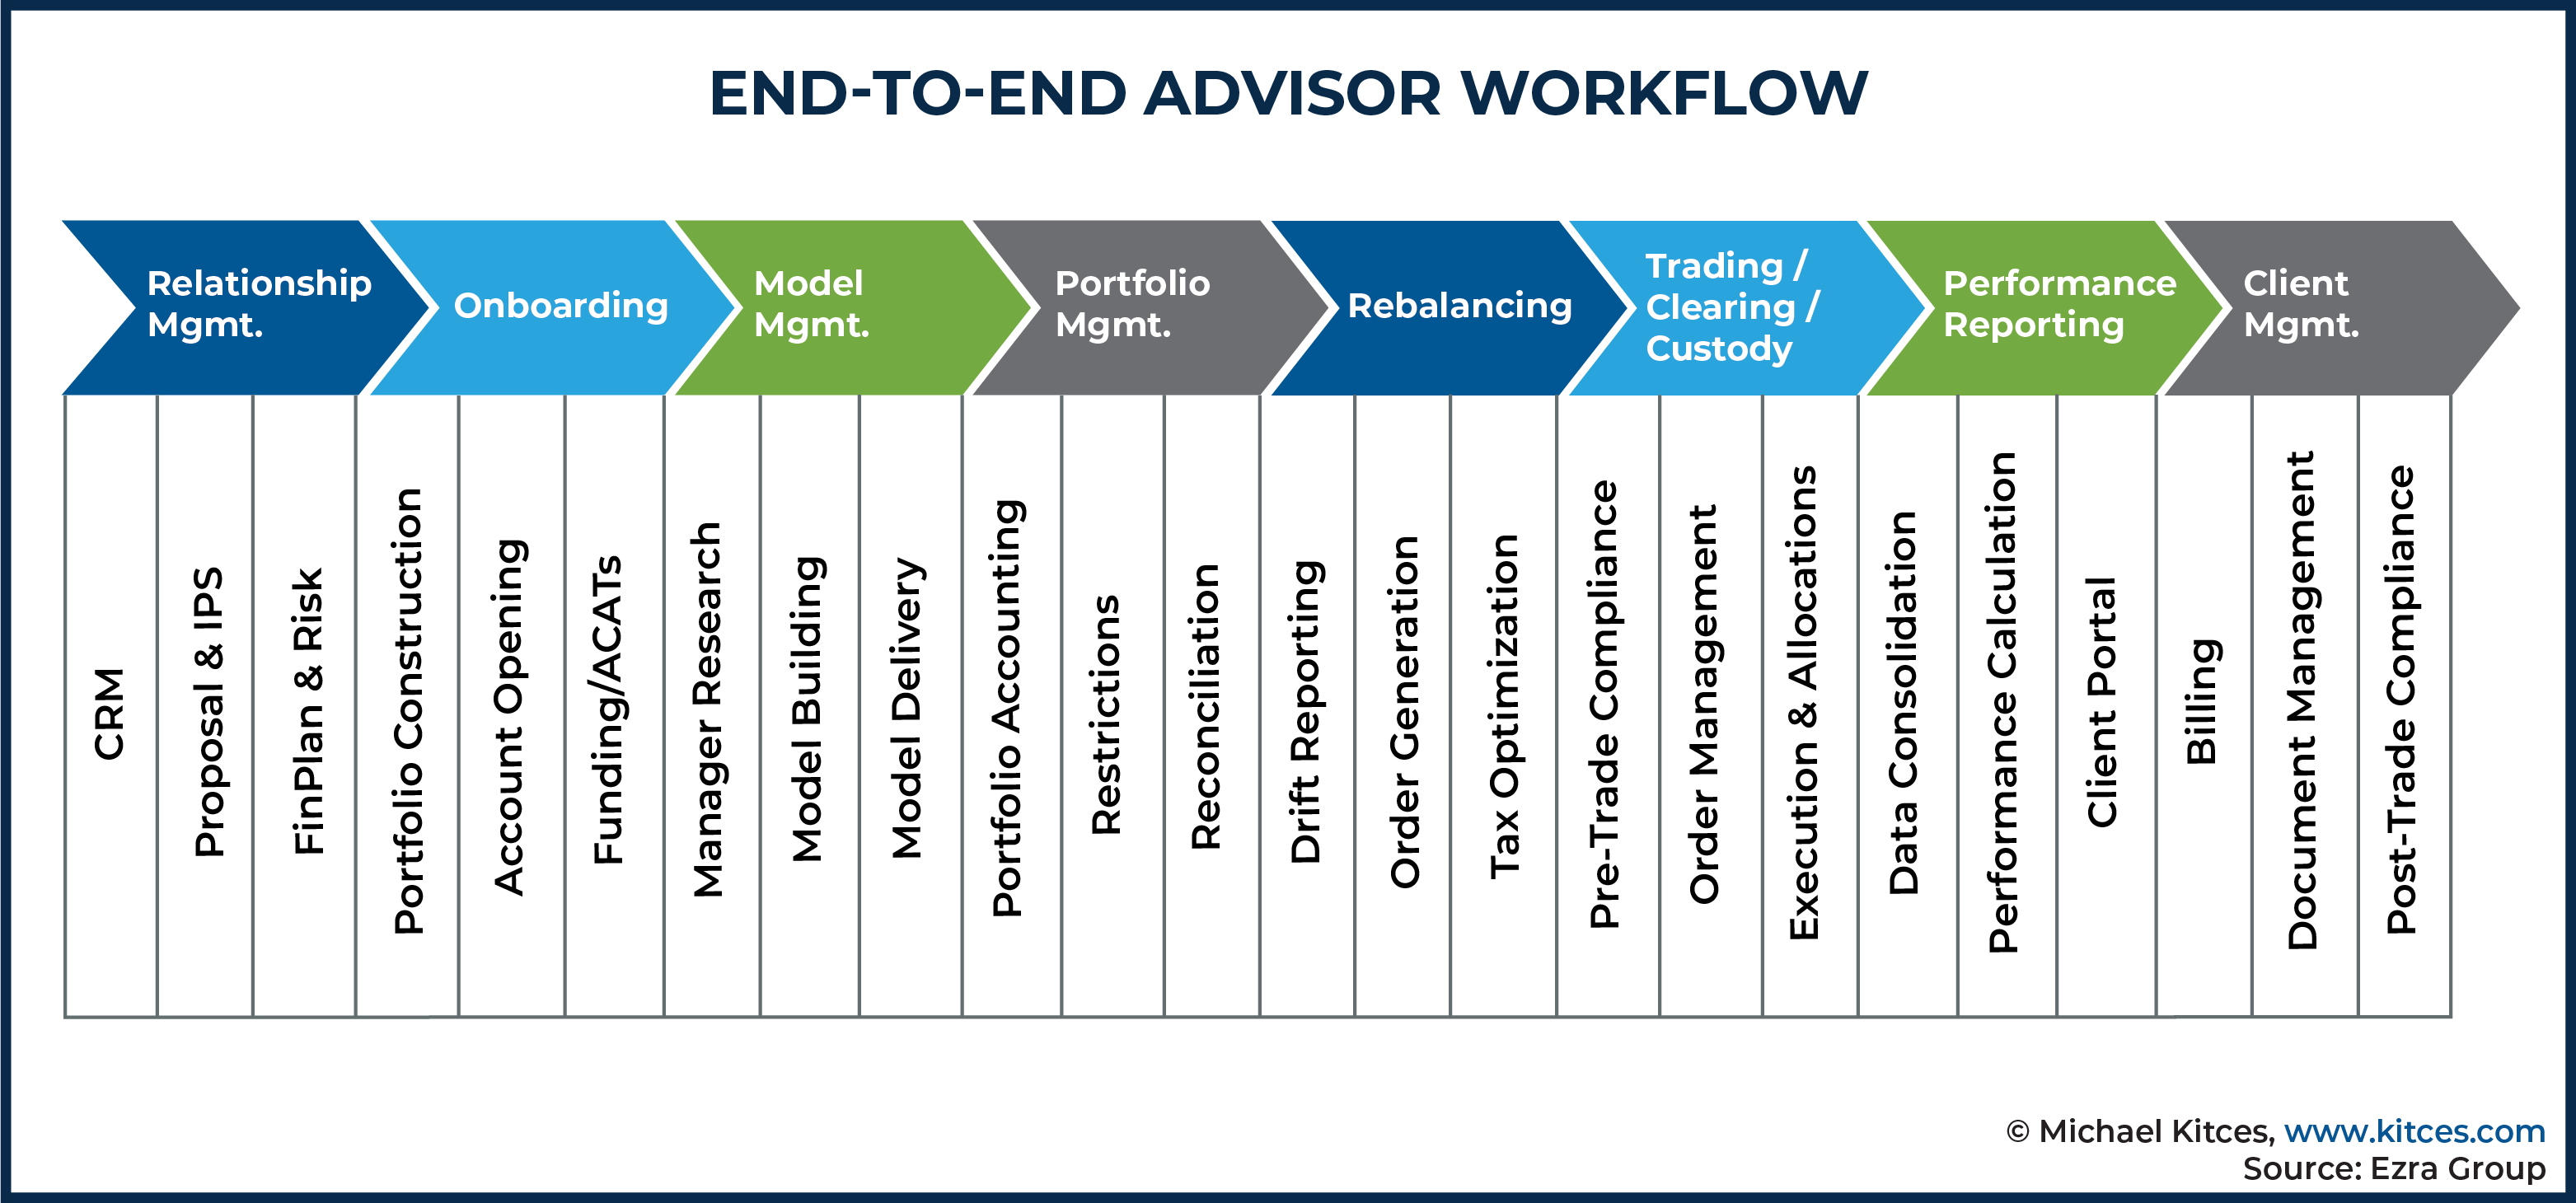
A Financial Advisor Workflow Templates is a reusable sequence that covers three things: client onboarding, review, and renewal. The onboarding piece collects KYC, suitability assessments, and account setup documents. The review piece logs annual statements and rebalancing decisions. The renewal piece tracks contract dates and compliance deadlines. Each step should have a required field, an owner, and a deadline.
I learned this the hard way. One of my firms had a template that looked perfect on screen. It required a signed capacity letter, a beneficiary form, and a suitability report. In practice, the template let advisers move to the next stage without uploading any of those files because the CRM treated a field as complete if it contained a single hyphen. I spent three hours writing a validation script that rejected any entry shorter than two characters. That fixed the immediate problem and cut false completions from about 40 percent down to roughly 3 percent.
What you actually need to build one
You need a reliable template that forces you through a sequence of tasks. The first thing most people get wrong is the order. Put compliance before revenue. You cannot collect a signed suitability report after you have already opened the account. Start with document collection, then move to review, then finalize with renewal tracking.
A common pitfall is assuming a template is static. It is not. Client types change, regulations change, and your internal procedures change. I keep a separate version for high-net-worth clients versus retail clients because the document load differs by about 30 percent. If you use one template for both, you either waste time on unnecessary steps or skip critical ones.
The exact workaround I used was to create a conditional branching rule. The template checks the client tier at the start and routes to the appropriate document set. This reduced processing time by about 15 minutes per client and cut errors by roughly 20 percent. Not a miracle, but enough to matter over a year.
Why they fail in production
Most people think a template is a solution. It is not. A template is a reminder, and reminders fail when they are buried under other work. I have seen advisers treat a template as a checkbox exercise. They click through the steps without reading them, fill in placeholder text, and move on. The template itself is technically correct, but the records are useless.
There is a bottleneck I keep hitting. Most templates assume linear progress. In reality, client workflows are messy. A client might request a change mid-process, or a regulator might ask for additional documentation. If your template does not have a pause point, you either break the sequence or ignore the request.
I wrote a simple pause rule into our template. It lets advisers suspend a workflow and resume later without losing their progress. This usually cuts the completion time from about 45 minutes down to 12 minutes per client, depending on how much back-and-forth you have with the client. Not perfect, but close enough.
Alternatives and when to use them
Not every situation needs a full template. Some clients are straightforward. Others require custom handling. I keep a lightweight checklist for simple accounts and a full template for complex ones. If you use a heavy template for simple cases, you waste time. If you use a lightweight checklist for complex cases, you risk missing steps.
The exact trade-off is about 20 percent of your cases being simple enough for a checklist, and 80 percent requiring a full template. If you ignore this and use one size fits all, you either slow down simple cases or expose yourself to compliance risk on complex ones.
I recommend starting with a pilot. Run a small group through the template, measure completion rates, and adjust. This usually reveals problems within two weeks and saves about 10 hours of rework per month. Not glamorous, but practical.
Gallery Financial Advisor Workflow Templates
Financial Advisor Workflow Templates
Financial Advisor Workflow Templates
Financial Advisor Workflow Templates
Financial Advisor Workflow Template
Financial Advisor Workflow Template In Powerpoint And Google Slides Cpb PPT Template