Practical Financial Analysis and Risk Management
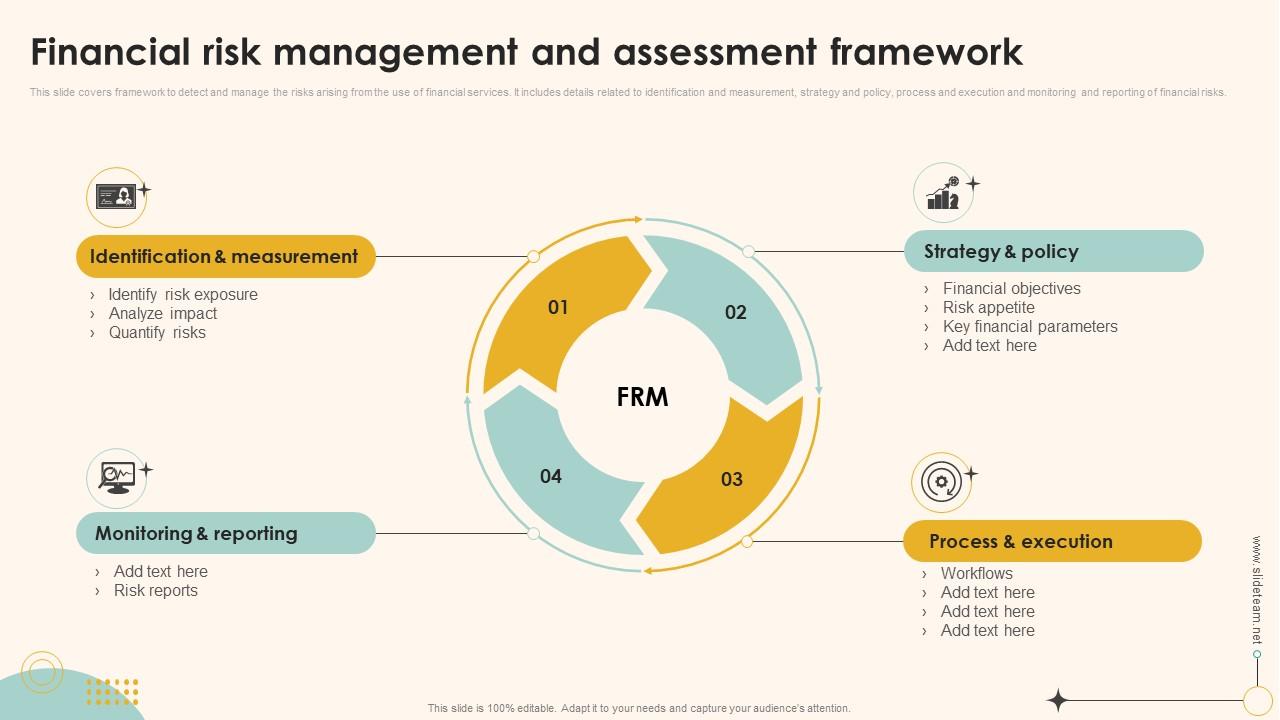
Most people approach this topic by looking for a formula that spits out a number they can report to a board. That rarely works in practice because markets don't behave the way textbooks assume, and the gap between what a model says and what actually happens is where real losses live. Financial Analysis And Risk Management is better understood as a continuous loop of measuring, challenging, and adjusting rather than a one-time calculation. I start with the positions I'm responsible for, pull daily returns over at least two full market cycles, and build a basic VaR model using historical simulation. I then immediately stress that same portfolio against March 2020, the 2008 financial crisis period, and a custom scenario where bond yields jump 200 basis points while credit spreads widen another 150. I compare the model output to what actually happened in those periods. If the model understates losses by more than 40%, I stop trusting it for sizing decisions and adjust my confidence level or switch to Expected Shortfall instead. I learned this the hard way a couple years ago when a client had a concentrated position in mid-cap technology names that looked fine on standard VaR. The model assumed correlations would stay below 0.6. They didn't. During a liquidity event in late 2022, every single holding in that basket moved together at 0.92 correlation. My initial VaR estimate missed the actual peak drawdown by roughly $18 million on a $60 million portfolio. The fix wasn't a better model. It was switching to a stress-test-first workflow where the VaR number became a secondary reference point rather than the primary decision driver.
The mechanics I actually use
Step one: Define the universe. You can't manage risk for something you haven't explicitly listed. Every position, every derivative, every contingent liability goes on the same spreadsheet. Omitting off-balance-sheet exposures is the single most common error I see. It's usually an accounting decision, not a risk oversight, but the result is the same. Step two: Calculate sensitivities. Delta, gamma, vega, theta for derivatives. Duration, key rate duration, convexity for bonds. Beta and factor exposure for equities. This takes longer than most people expect because the inputs matter more than the formulas. A mispriced volatility surface or an incorrect yield curve interpolation will corrupt the entire sensitivity analysis regardless of how elegant the rest of the model is. Step three: Build the correlation structure. This is where most models fail. Standard historical correlation matrices assume stationarity. Markets aren't stationary. I use a combination of rolling window correlations with a two-month lookback and a regime-switching adjustment that weights recent observations more heavily. It's not perfect but it's materially better than a single static matrix.
Step four: Run the numbers and interpret them correctly. A 99% one-day VaR of $500,000 doesn't mean you'll lose $500,000 once a hundred days. It means there's a one percent daily probability of exceeding that loss. The Expected Shortfall at that confidence level might be $1.2 million, which is the number that actually matters for capital allocation.
Get the Full Details
Where the standard approach breaks down
VaR models implicitly assume that the past is a reasonable proxy for the future distribution of returns. That assumption is wrong almost all the time and devastatingly wrong when it matters. Credit risk models based on historical default rates systematically underestimate tail risk because they condition on survival. If you're in a recession, the companies you're modeling are already struggling, and the historical baseline is biased downward. Liquidity risk is another area where standard frameworks quietly fail. A position might be perfectly hedged in normal markets and completely unhedgeable the day you need it to be. I keep a separate illiquidity overlay on top of every VaR model that adjusts position limits based on average daily volume, bid-ask spreads, and market depth rather than just volatility. The liquidity-adjusted VaR is almost always higher, sometimes significantly so. Financial Analysis And Risk Management tools that claim to solve this automatically should be treated with suspicion. The best free resources I've found are open-source Python libraries like VaRCalc and riskfolio-lib, and the NIST Handbook section on financial risk metrics. They require actual understanding of what they're doing, which is the point.
The counter-intuitive part most people miss
Lower portfolio volatility does not mean lower risk. A portfolio of low-volatility stocks can have massive downside risk if they all respond to the same systemic factor. Conversely, a volatile portfolio with negative skewness protection through options can have lower tail risk than a boring-looking one. The metric that matters is Expected Shortfall, not standard deviation. Standard deviation measures dispersion in both directions equally. Tail risk lives in only one direction. Another thing: correlation is not a constant. It increases during downturns. This is called correlation breakdown or correlation convergence and it's one of the most important concepts in risk management because it invalidates most diversification benefits precisely when diversification should matter most. I track the rolling correlation between my largest positions and treat any correlation above 0.8 as a warning signal, not a confirmation of diversification.
What I actually check before trusting any model
First, I backtest it. Not against a single period but across multiple periods with different characteristics. Second, I check sensitivity to input changes. If shifting the volatility assumption by five percent changes the VaR by thirty percent, the model is too fragile for real decisions. Third, I look at the residuals. If they're not normally distributed and they don't have fat tails, the model is missing something. Markets always have fat tails. A model that doesn't capture that is underestimating risk. The practical outcome of all this is that I rarely rely on a single risk number. I present a range: base case VaR, stressed VaR, Expected Shortfall under multiple scenarios, and liquidity-adjusted estimates. The differences between those numbers are where the actual risk lives, and ignoring the spread between them is how people lose money.