What actually goes into a Financial Analysis Business Plan
A Financial Analysis Business Plan is not a special document. It is a business plan with a heavier emphasis on the numbers side of things. You need revenue projections, cost breakdowns, cash flow forecasts, balance sheet estimates, and break-even analysis. That is the core of it. Investors and lenders use it to determine whether a business can actually survive past year one. Most plans fail because the financials are copy-pasted from someone else's template. I learned this the hard way. A few years back I worked with a client who was opening a mid-scale logistics warehouse. They came to me with a five-year pro forma that showed steady revenue growth from month one. The plan looked clean on paper. Then we dug into the actual lease terms, equipment financing schedules, and the fact that their largest potential client operated on a 90-day payment cycle. The cash flow forecast they had built collapsed within four months of actual operations. They ran out of operating capital before they hit break-even. The fix was straightforward once we stopped guessing. We rebuilt the working capital model around the real payment terms, added a three-month buffer for accounts receivable delays, and structured the equipment financing to match the revenue ramp rather than assuming immediate full utilization. The revised Financial Analysis Business Plan showed a cash crunch in months 5 and 6. That turned out to be the most valuable thing about the entire document, because it told them exactly where they needed a contingency line of credit before signing the lease.
Here is how you build one properly without recreating that mess. Start with your revenue model. Be specific about pricing, volume assumptions, and seasonality. If you sell B2B services, factor in average contract length and renewal rates. If you sell products, include inventory turnover and supplier lead times. General rules of thumb like "industry average growth of 10 percent" do not work for individual businesses. I have seen too many models bake in growth rates from market reports and wonder why the actual numbers come in half that amount. Next, build the cost structure in two layers. Fixed costs are things like rent, salaried positions, insurance, and software subscriptions. Variable costs are materials, shipping, commission payments, and transaction fees. The mistake people make is lumping everything together. When you need to make a cut during a downturn, you need to know exactly which costs disappear with revenue and which stay. That distinction shows up in your gross margin versus operating margin calculations and matters a great deal to anyone reading your plan.
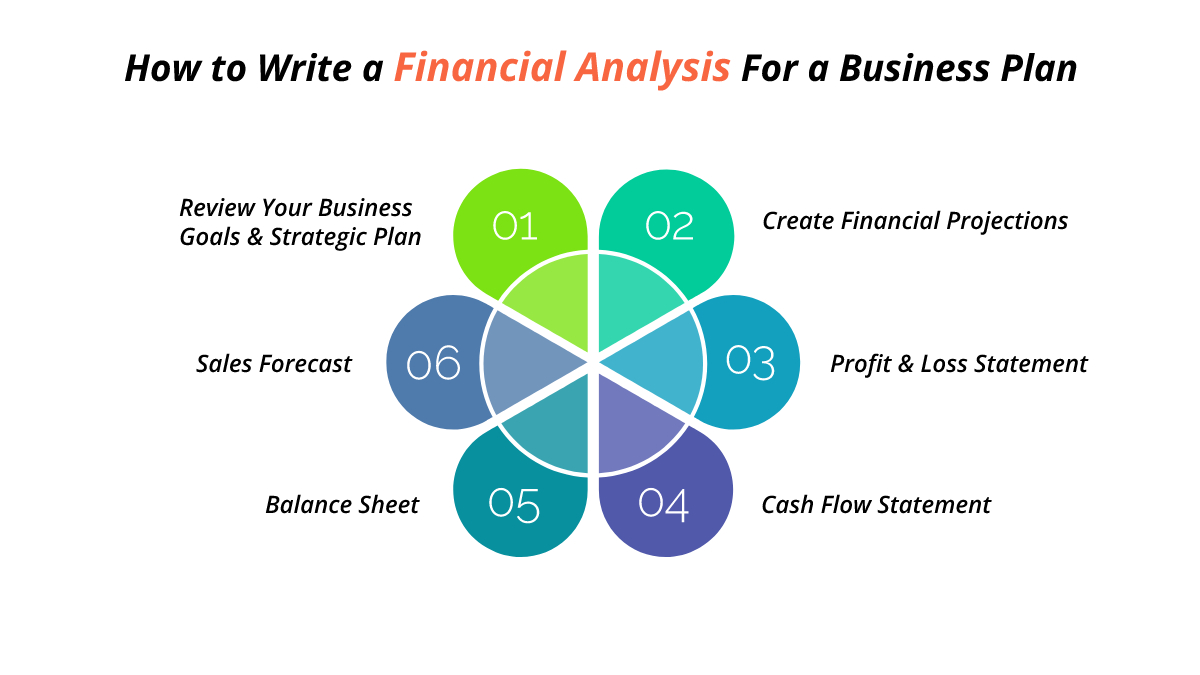
Now the cash flow statement. This is where most people get tripped up. Revenue on an accrual basis is not the same as cash in the bank. If you invoice a client today and they pay in 60 days, your profit and loss statement looks fine but your cash flow statement will show a gap you need to cover. Build a monthly cash flow projection for at least the first 18 months. Include when you expect to receive payment and when you owe money. Account for payroll timing, tax deposits, and any seasonal spikes in expenses. Your balance sheet estimate should follow from the P&L and cash flow work. Track assets, liabilities, and equity as they change each month. You do not need perfect precision at this stage, but you do need the major line items to connect logically. Retained earnings should flow from your net income. Debt balances should match your loan assumptions. Anything that does not tie out will raise eyebrows immediately. Run three scenarios: base case, optimistic, and pessimistic. The pessimistic case is the one that gets you through to funding. I keep seeing business plans that only model the base case and then act surprised when a key assumption shifts. Lenders and grant committees look for stress testing. Show them you understand what happens if revenue comes in 20 percent below projection or if a major supplier increases prices. It does not need to be glamorous. It needs to be honest.
Get the Full Details
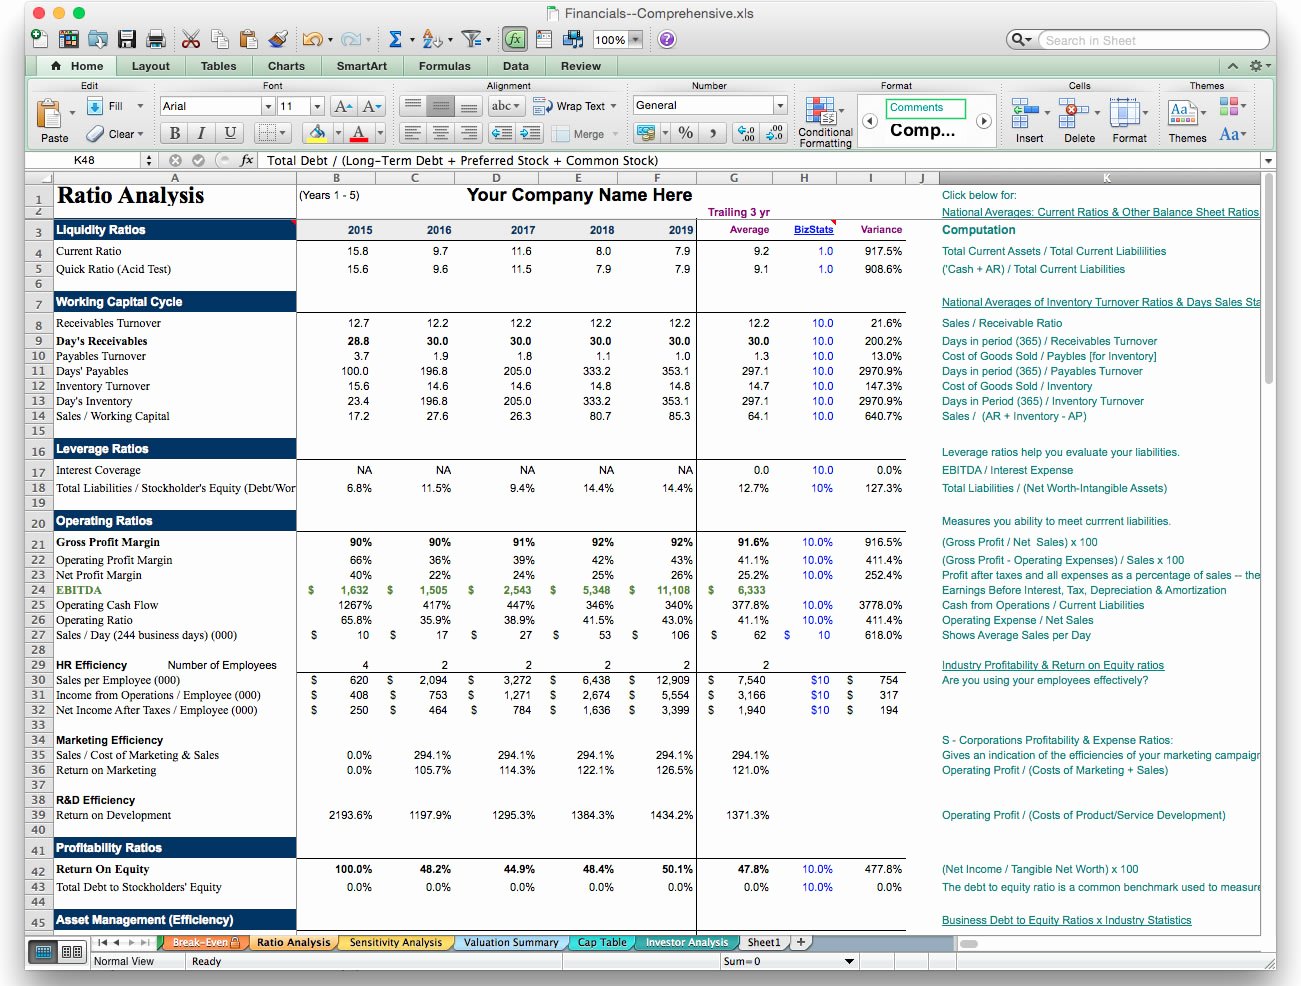
Key metrics to include in your Financial Analysis Business Plan are gross margin percentage, net margin, EBITDA, burn rate, runway in months, customer acquisition cost versus lifetime value, and the break-even point in units or revenue. Put them in a summary table so readers do not have to hunt for them. They will look at that table before they look at anything else. There is a counter-intuitive point about break-even analysis that people often miss. Break-even on a per-unit basis assumes constant pricing and constant variable costs across all volume levels. That is rarely true. Volume discounts on materials, tiered shipping rates, and commission structures that kick in at certain thresholds all shift the break-even point. Run your break-even calculation at multiple volume levels rather than assuming a single static number. It takes about ten minutes and makes the analysis significantly more credible. Another thing beginners get wrong is discount rate selection for any NPV or valuation work in the plan. Using a single percentage across all five years implies your risk profile does not change over time. It does. Early years carry execution risk, market risk, and concentration risk. Later years carry different risks. A reasonable approach is to use a higher discount rate for years one and two and reduce it gradually as you reach more stable operations. The exact rates depend on your industry, but the principle matters more than getting the numbers perfectly right.
If you need a starting template, search for financial analysis business plan template Excel or financial analysis business plan download. There are free options from SBA-affiliated resources and paid options from business plan software providers. The template itself is secondary to the assumptions you build into it. A well-reasoned model in a basic spreadsheet beats a beautifully formatted one built on weak assumptions every time. The main limitation of this approach is that it only works if you are willing to sit with the assumptions and challenge them. A Financial Analysis Business Plan will not save you from a fundamentally flawed business model. It will surface the flaws faster than guessing, but it cannot fix bad product-market fit or unrealistic pricing. If your unit economics do not work at scale, no amount of spreadsheet formatting will make them work. In that case, reconsider the model before you spend weeks refining a plan that investors will reject on day one. Another practical bottleneck is data availability. Early-stage businesses often lack historical data to justify their projections. The workaround is to anchor assumptions in comparable company data, industry benchmarks, and small-scale pilot results rather than pure speculation. Cite your sources in the assumptions section. It adds credibility and gives reviewers something to challenge instead of just your conclusions.
Keep the document tight. Eighteen to twenty-five pages for the full plan, with the financial section taking up roughly half of that. Appendices for detailed tables and supporting calculations. Nobody reads 60-page appendices. They glance at the summary and judge from there. Make the summary accurate enough that a second look is not humiliating.