What actually happens when you try to analyze a nonprofit's finances
You pull the numbers and everything looks fine until you realize grant revenue got recognized in the wrong bucket, the board thinks you're "in the black" because of a one-time donation spike, and your liquidity ratios are completely wrong because you included restricted funds in your operating reserves. I've sat through enough of these reconciliations to know the standard for-profit playbook doesn't translate cleanly here. Financial Analysis For Nonprofit Organizations requires a different mental model from the start. You're not looking at profit margins or return on equity. You're looking at operational sustainability, fund restriction compliance, and whether the organization can meet its obligations without burning through its endowment or relying on a single grant cycle. The mechanics are similar. The framework is entirely different.
Financial Analysis For Nonprofit Organizations: what changes and why
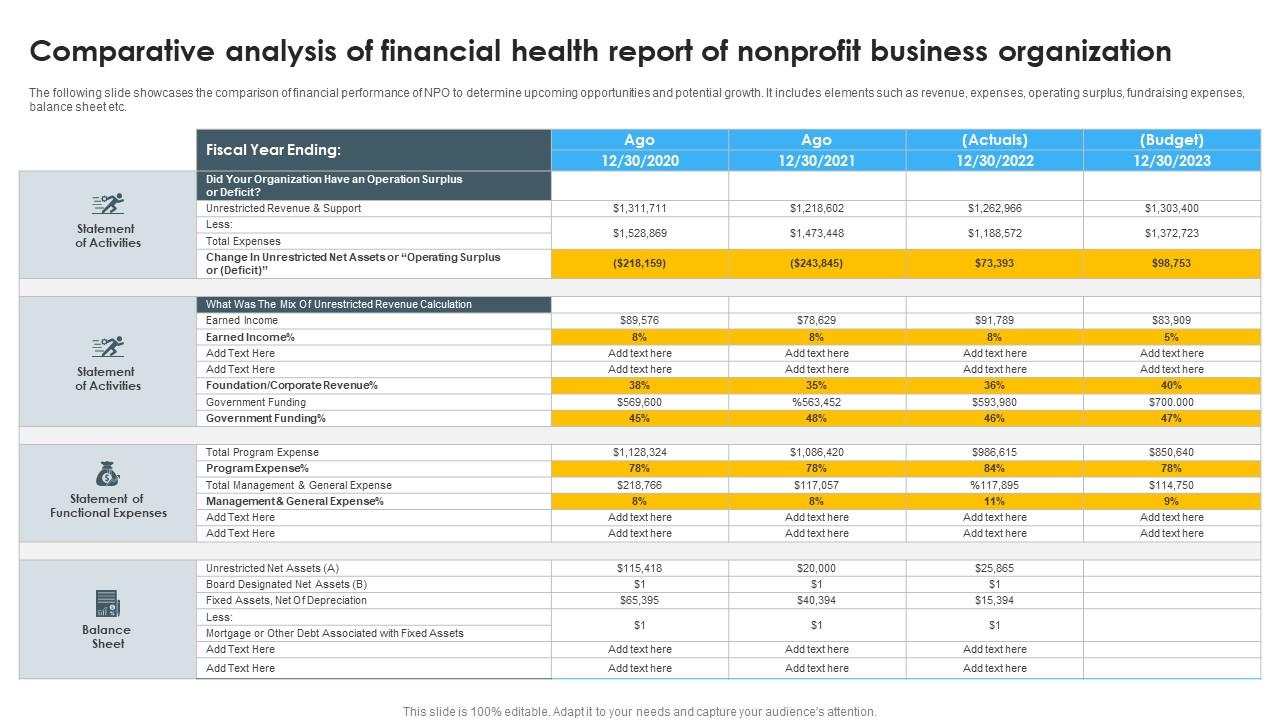
Three core shifts define this. First, revenue recognition follows contribution timing and donor restrictions, not earned income cycles. A $500,000 grant hits your statement in March but may need to be spent over two years. Second, net asset classification replaces retained earnings with three categories: unrestricted, temporarily restricted, and permanently restricted. Third, expense categorization matters more than cost structure alone. Program services versus supporting activities isn't just accounting detail — it directly affects your program service ratio, which donors and evaluators treat as a proxy for organizational effectiveness. Start with the statement of financial position. Don't rush past it. This is where most errors originate. Go through each line item and verify the net asset classification. If you find restricted cash that's been sitting for more than eighteen months without being spent, that's either a restriction that should have been released or a sign the program never got funded properly. Both issues need fixing, but they require different responses. The first is a release of restriction problem. The second is a fundraising or execution problem. Next, pull the statement of activities for at least the last three fiscal years. Year-over-year revenue trends matter more than any single year. A nonprofit that grew from $800,000 to $1.2 million to $950,000 is signaling something. Most people only look at the latest year and miss the volatility entirely. Chart it yourself. You'll catch the decline that the general ledger software won't flag because the ending balance still looks positive.
Then examine the statement of functional expenses. The 990 format forces program versus supporting activity allocation. But here's where it gets messy in practice. Shared costs like facilities and IT don't allocate cleanly. If your director split these expenses proportionally based on headcount across departments, the resulting ratios could be off by 15 to 20 percent depending on how staff time is distributed. I learned this the hard way when I reviewed a nonprofit that reported a 78 percent program service ratio but our reallocation analysis showed it was closer to 64 percent. The difference came from how they handled the CFO's time. They allocated 100 percent to management and general, but she spent roughly 40 percent of her hours overseeing the direct service program. That 40 percent, multiplied by her fully loaded cost, shifted about 14 percentage points.
Get the Full Details

The ratios that actually matter
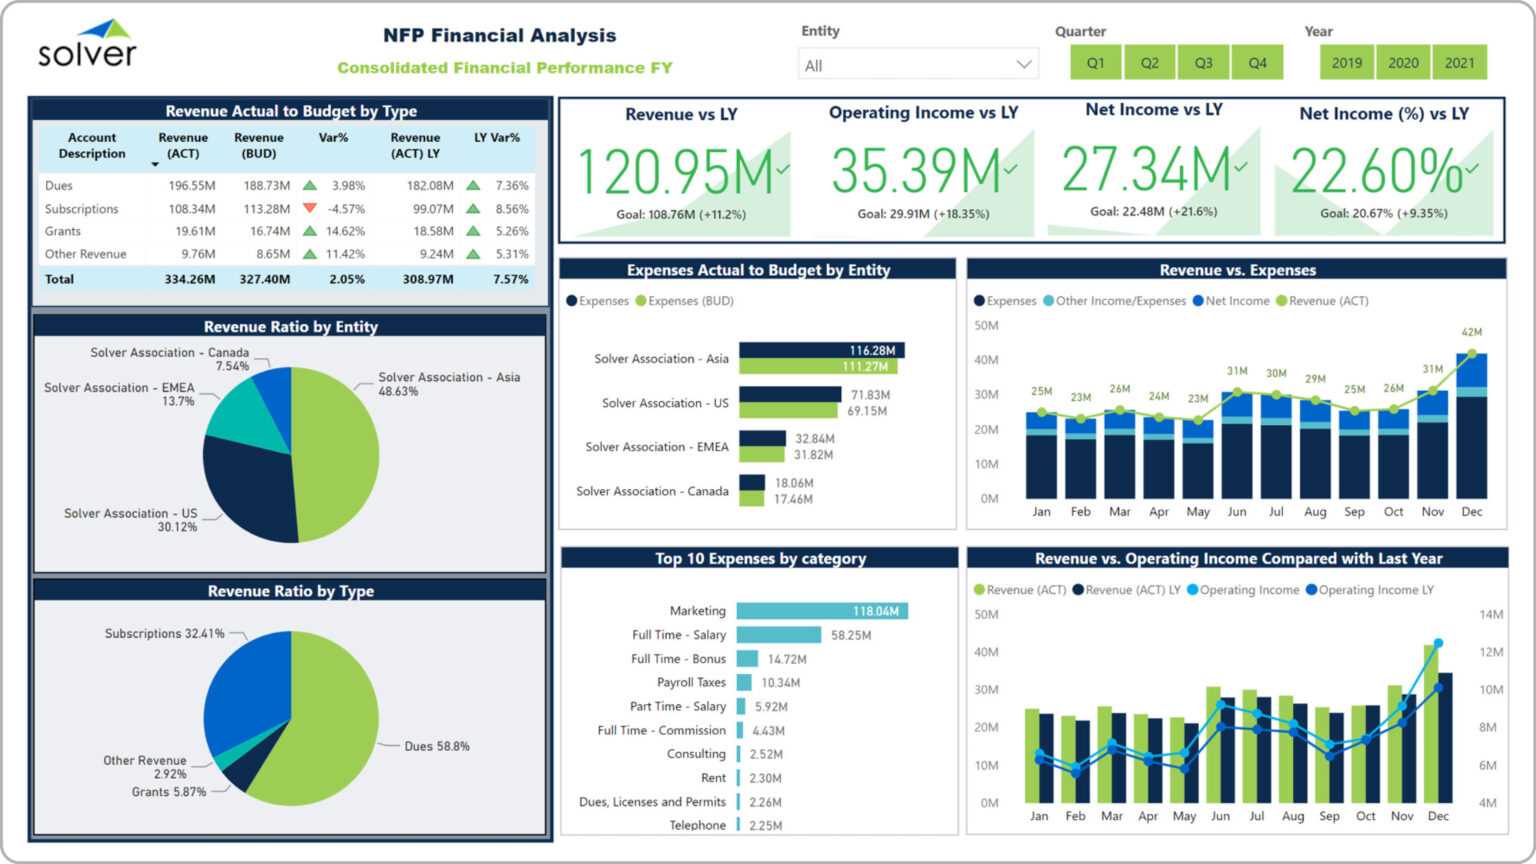
Liquidity ratio: unrestricted current assets divided by unrestricted current liabilities. For nonprofits this is more meaningful than for for-profits because restricted funds can't be touched for operations. If you include them, you get a misleading cushion number. A ratio below 1.5 for a small nonprofit suggests real operational fragility. Above 3.0 might indicate hoarding rather than prudence. The optimal range depends heavily on revenue predictability. An organization with three years of committed government contracts can sustain a lower ratio than one relying on annual private donations. Operating margin: excess of revenues over expenses divided by total revenues. Nonprofits often report this as a percentage of total support and revenue. Unlike for-profits, a thin or negative margin isn't automatically alarming if the organization is making strategic investments. But sustained losses above 5 percent for two consecutive years without a documented turnaround plan are a red flag. I worked with a behavioral health nonprofit that ran operating margins near zero for four years while expanding service capacity. Their approach was defensible because the expansion was board-approved and grant-funded. Still, their liquidity dropped below 1.2 during the build phase, which required a line of credit to avoid payroll issues. That shouldn't be common practice. It's an exception that should be monitored closely. Program service ratio: program expenses divided by total expenses. This is the number everyone quotes. It's also the number most manipulated. Don't use it as a standalone quality indicator. A high ratio could mean operational efficiency. It could also mean the organization underfunds development or administration to boost the appearance. Look at the trend alongside operating margin and board spending. If the ratio climbs while operating margin deteriorates, the organization may be sacrificing long-term sustainability for short-term optics.
Grant dependency analysis
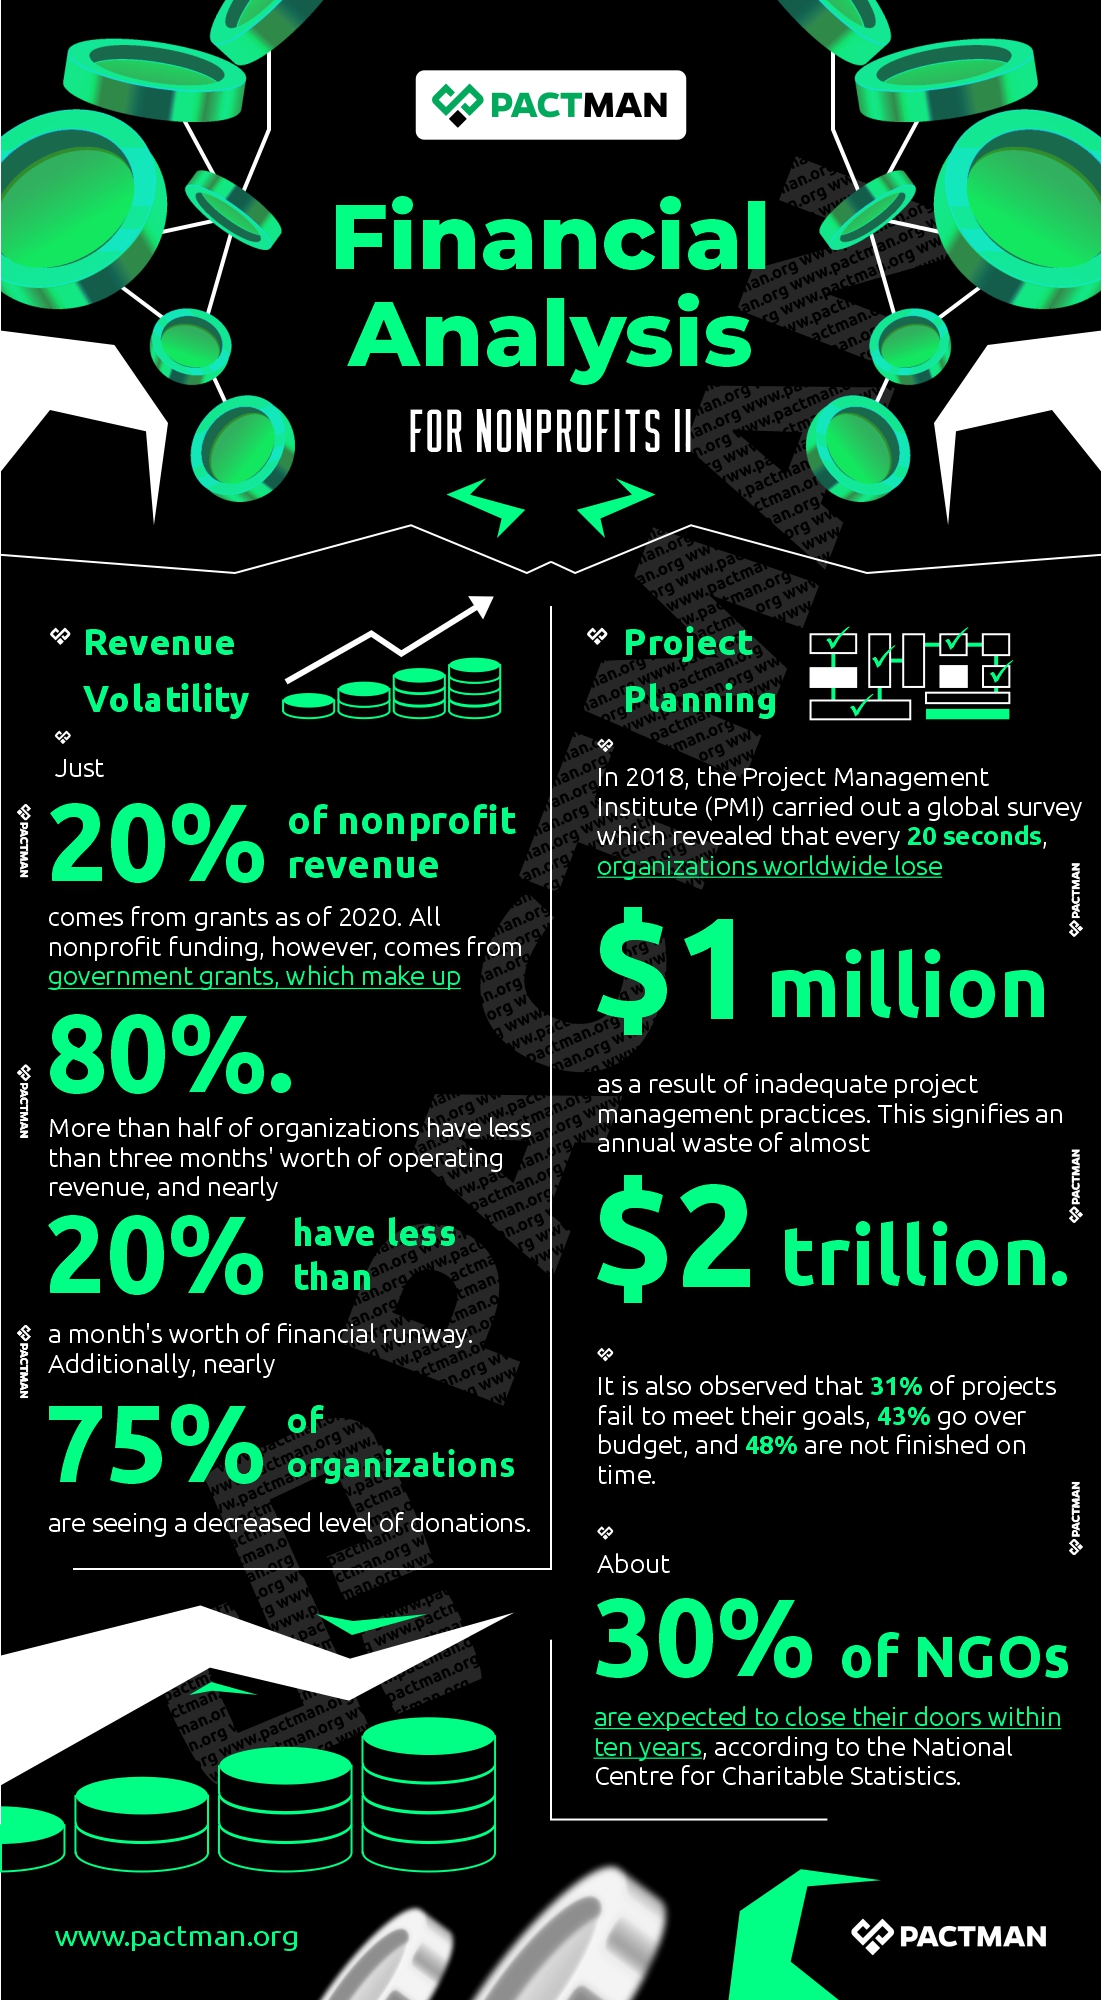
This section separates amateur reviews from professional ones. Identify the top three to five funders by revenue contribution. Calculate what happens if each one terminates funding. Most nonprofits cannot survive the loss of their primary funder without restructuring. You need to know this before the funder does. I reviewed an arts organization where a single state arts council grant represented 34 percent of total revenue. They had no contingency plan. When the council revised its eligibility criteria, the organization lost that funding and couldn't recover within two fiscal years. The financial analysis would have flagged this concentration risk immediately. Instead, the board's strategic planning process treated the grant as guaranteed income. Track grant duration, renewal probability, and restriction timelines. Short-term grants (one to two years) require constant renewal effort. Multi-year commitments should be verified in writing, not assumed from verbal conversations. I've seen organizations treat preliminary award letters as binding revenue, which led to shortfalls when the formal contracts included amendments the teams didn't read closely enough.
Board and governance financial literacy
Your analysis will reach a ceiling determined by the board's engagement level. I've worked with board members who confused cash basis and accrual basis reporting, and others who approved budgets without understanding the difference between restricted and unrestricted net assets. The practical impact is that financial recommendations get ignored or misapplied. Ensure the board receives quarterly reports that include the three statements plus a brief narrative explaining the month-over-month variances. Don't just send spreadsheets. Add a paragraph noting whether revenue trends align with projections and whether any expense categories areby more than 10 percent from budget. This level of detail catches problems six to nine months earlier than annual reviews do.
Tools and what actually works
Most nonprofits use QuickBooks or similar platforms. These work for day-to-day bookkeeping but require manual adjustment for proper financial analysis. The standard reports don't separate net asset classes automatically. You'll need to set up custom classes or tags for each fund restriction and build a reporting layer on top. For more sophisticated analysis, I recommend downloading the Nonprofit Financial Analysis Workbook template I've compiled based on the framework above. It includes the ratio calculations, grant dependency modeling, and the expense reallocation logic that caught that 14-point program service ratio error I mentioned. The template is built in Google Sheets so it's accessible without additional software costs.
Limitations and when this breaks down
Financial analysis for nonprofits has real blind spots. Historical data doesn't predict future sustainability when funding landscapes shift rapidly. A four-year trend of stable government contracts can become irrelevant overnight if legislative priorities change. The methodology also struggles with in-kind contributions, which are recorded at fair market value but are often difficult to value reliably. Volunteered professional services, donated equipment, and space contributions can materially affect expense reporting but introduce estimation errors that are hard to audit. Organizations with multiple legal entities or complex partnership structures require consolidated analysis that goes beyond standard financial statements. Individual entity numbers may look healthy while the consolidated picture shows structural weakness. If your organization operates through affiliated corporations or joint ventures, you'll need to pull together inter-entity transactions separately. Finally, be aware that this analysis is backward-looking. It shows what happened, not what's likely to happen. Scenario planning and stress testing against realistic funding reductions are necessary complements. A nonprofit that passes every ratio check but has no plan for a 25 percent revenue decline is still vulnerable. The numbers tell part of the story. The governance decisions and operational flexibility tell the rest.