Setting Up a Proper Financial Model in Excel
Most people approach Financial Analysis Using Excel the wrong way. They open a blank workbook, start typing numbers, and hope formulas hold together by the end of the month. That rarely works. A model that survives a quarterly close is built differently from day one. Here is how it actually gets done in practice. Start by separating your inputs from your calculations. I keep a dedicated sheet called "Assumptions" or "Inputs" where every rate, growth percentage, and one-time figure lives. The rest of the workbook references that sheet exclusively. When a finance manager asks you to revise the WACC from 9.2% to 8.7%, you change it in one cell instead of hunting through twelve different calculation sheets. This alone prevents the kind of errors that show up when half your model uses the old rate and the other half uses the new one. Next, build your structure in a top-down order. Revenue goes at the top, then operating expenses, then EBITDA, then interest and tax, then free cash flow. Do not reverse this sequence because Excel lets you, which means something. Forward-chaining models are far easier to audit. Someone reading your work should be able to follow the logic from gross revenue down to net income without jumping between five different tabs. Backward-chaining structures, where you bake in a target IRR first and work backward to implied revenue, are fine for deal screening. They are terrible for operational reporting.
Hardcode as little as possible. Every number you type directly into a formula cell is a future bug waiting to happen. If your model contains something like =A5*0.08, that 0.08 needs to live in a labeled cell somewhere, and your formula should reference that cell. It takes maybe thirty seconds longer to set up and it saves three hours of debugging later when the discount rate changes mid-year.
Common Pitfalls in Financial Analysis Using Excel
The first thing that breaks in most spreadsheets is circular references. Excel will eventually calculate them through iterative approximation, but the results are opaque and silently wrong if your iteration settings are off. I once built a revolving credit facility model where the interest expense depended on the average debt balance, which depended on the cash flow, which depended on the interest expense. Excel's default iteration limit of 100 produced a result that was off by four hundred thousand dollars because the convergence was too coarse. I resolved it by writing a manual averaging loop using a helper column with a @INDIRECT reference that stepped the calculation forward in discrete periods instead of relying on the built-in iterative engine. The fix was not elegant, but it was transparent and auditable, which is what actually matters when someone from audit is looking over your shoulder. Another issue that nobody warns you about is date handling. Excel stores dates as serial numbers, and mixing date formats across regional settings will silently corrupt your time-series alignment. I inherited a model where the fiscal year alignment was broken because one sheet used US date format and another used European format, and the VLOOKUP matching on dates returned null values across an entire quarter of data. The workaround was to convert every date to a consistent YYYYMM integer key using the YEAR and MONTH functions, then match on that key instead of the raw date value. It is slightly less readable but it eliminates an entire category of silent error. You should also avoid merging cells in any sheet that feeds into a calculation. Merged cells break macro recording, they confuse Power Query import routines, and they make sorting impossible. It is a formatting convenience that costs more in maintenance than it saves in presentation. Unmerge everything in your data area and use "Center Across Selection" from the Format Cells dialog instead. It looks identical on screen and does not corrupt the underlying grid.
Get the Full Details
Building a Three-Statement Model
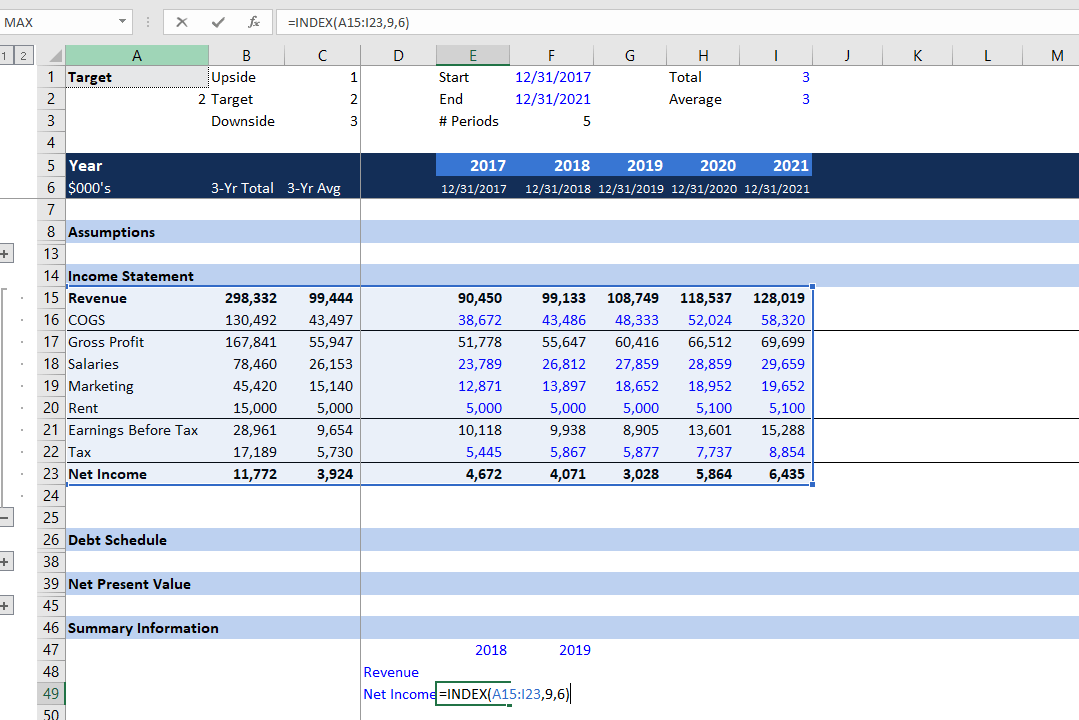
A three-statement model links the income statement, balance sheet, and cash flow statement so that changes in one automatically flow into the others. The mechanics are straightforward once you accept that the balance sheet must always balance, which means the cash flow statement is essentially the plug that makes that happen. For the income statement, you model revenue growth as a percentage derived from your assumptions sheet, then apply margins for COGS, operating expenses, and depreciation. Keep depreciation separate from amortization. Mixing them obscures the cash flow impact because depreciation is a non-cash charge while amortization may have different tax treatment depending on your jurisdiction. For the balance sheet, link working capital accounts to the income statement using turnover ratios. Accounts receivable divided by revenue gives you days sales outstanding. If DSO is 45 days, your AR balance is revenue times 45 divided by 365. Changes in these balances flow into the cash flow statement automatically. Fixed assets connect through your capex assumptions and depreciation schedule. Debt connects through your financing assumptions, and equity connects through retained earnings, which is net income minus dividends.
The cash flow statement reconciles the change in cash between the beginning and ending balance sheet. Operating cash flow starts with net income, adds back depreciation and amortization, then adjusts for changes in working capital. Investing cash flow captures capex and asset sales. Financing cash flow captures debt draws, repayments, dividends, and equity issuances. The sum of all three plus the opening cash balance must equal the closing cash balance. If it does not, you have a linkage error somewhere. I have seen models where the balance sheet did not balance by as much as fifty dollars due to rounding differences across thousand-cell ranges. The fix is to use a single rounding convention across the entire model. Round at the final display level, not at every intermediate calculation. Excel's rounding behavior with the ROUND function applied selectively creates drift that compounds across periods. Let the raw precision carry through and format cells to two decimal places for presentation only.
Sensitivity and Scenario Analysis
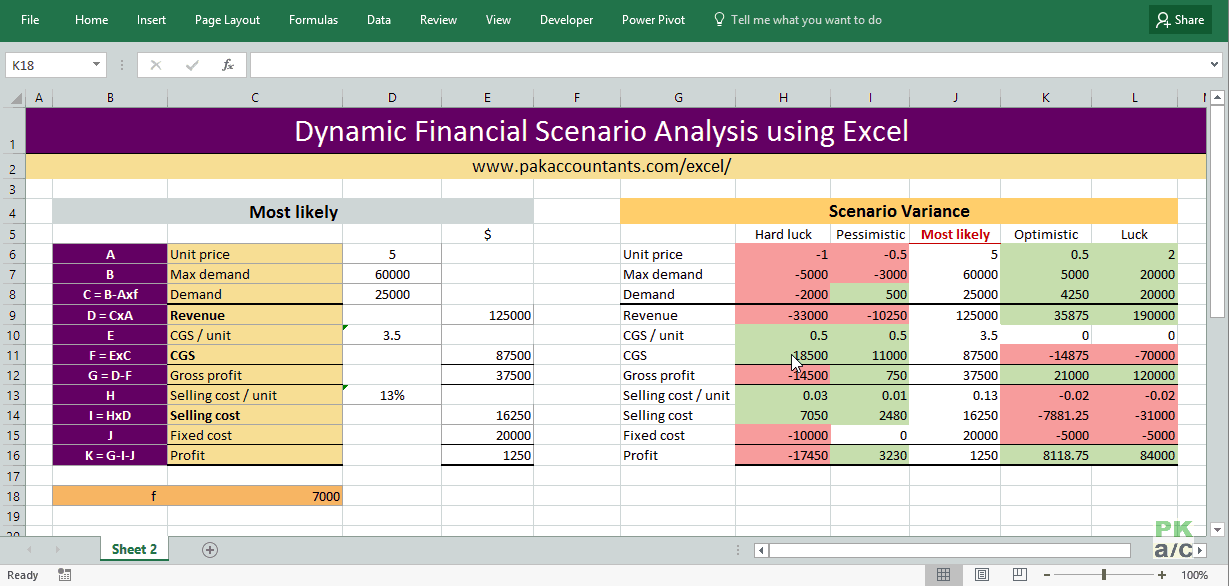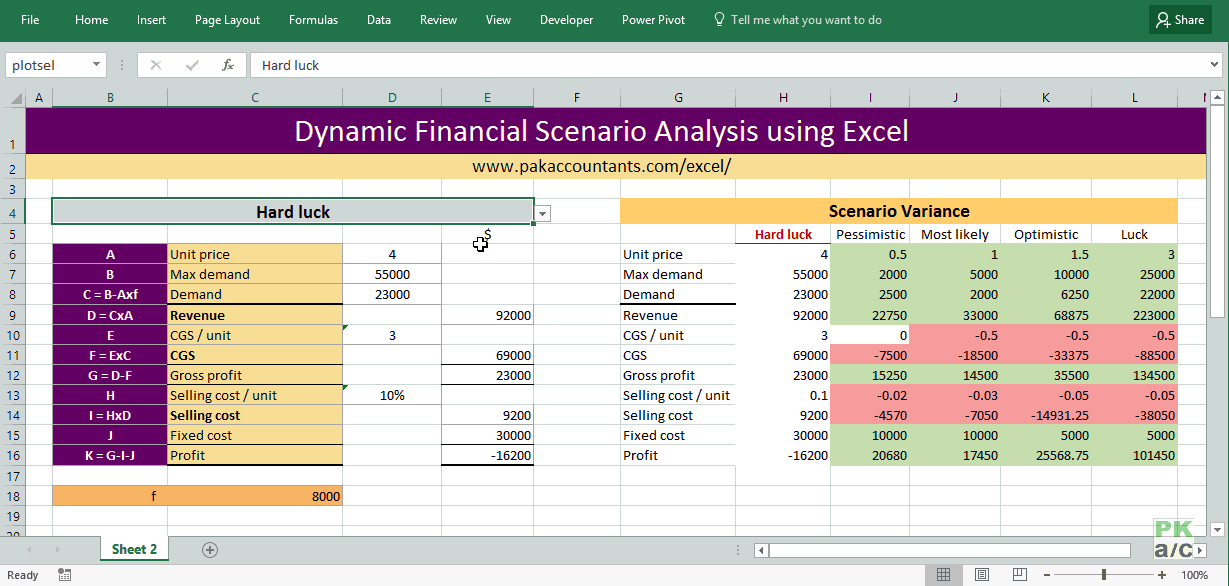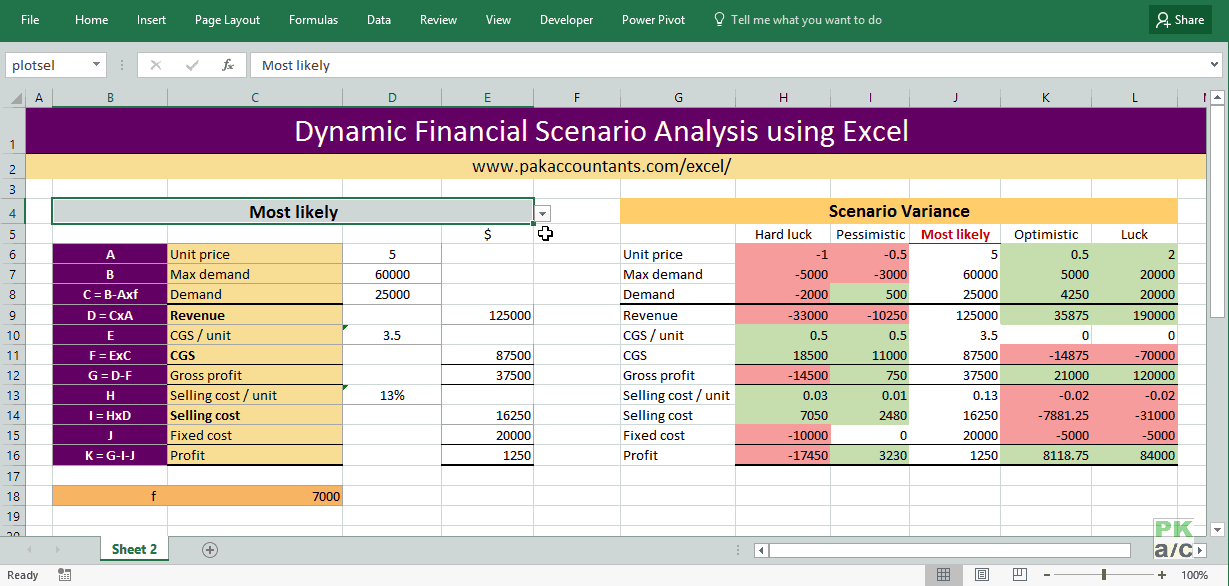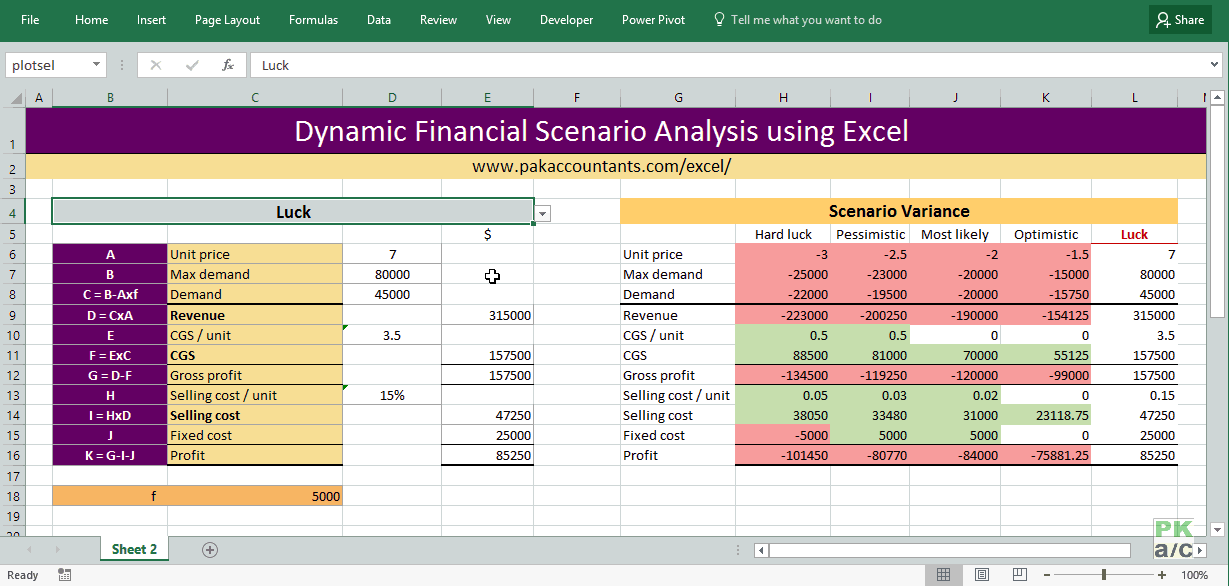
Once your base case model is working, you need to understand how sensitive your outputs are to changes in key assumptions. The Data Table feature in Excel is the standard tool for this, but it has a quirk that catches people off guard. Data Tables force volatile recalculation even when nothing has changed, which can slow down a large model significantly. I keep my Data Tables on a separate sheet with no other calculations, and I set calculation mode to manual when building and testing. Switch to automatic only when reviewing final outputs. For scenario analysis, use named ranges to label each set of assumptions. Create a scenario manager setup with Base, Conservative, and Aggressive variants. The key insight most people miss is that scenario analysis in Excel is really just a structured way to swap out input values, not a true probabilistic tool. If your revenue assumption follows a normal distribution with a standard deviation of fifteen percent, the scenario manager cannot capture that. For that you need @RISK or a Monte Carlo simulation. Scenario analysis tells you what happens at discrete points. It does not tell you the probability distribution of outcomes. I once needed to present a range of possible NPV outcomes to a investment committee. My three-scenario setup showed a spread from negative three million to positive twelve million, which looked dramatic. But when I ran a quick Monte Carlo simulation with ten thousand iterations, the actual distribution was heavily right-skewed. The downside was bounded but the upside had a long tail. Presenting only the three scenarios would have misrepresented the risk profile. The committee needed to see the full distribution, not just three arbitrary points.
Automation and Maintenance
VBA macros save time on repetitive tasks, but they introduce version dependency and maintenance overhead. A macro written in Excel 2016 may behave differently in Excel 365, especially around calendar functions and dynamic array behavior. Use macros sparingly and document every one with a comment block at the top explaining what it does, what inputs it expects, and when it was last tested. I keep a simple changelog sheet in every model I build. It is not glamorous but it prevents the situation where you inherit a workbook from someone who left six months ago and cannot remember why a particular macro exists. Power Query is worth learning if you pull data from multiple sources. It replaces the manual copy-paste routine that consumes most of a financial analyst's month-end closing time. I used to spend roughly two hours each period importing trial balance data, cleaning column headers, and matching account codes. After setting up a Power Query connection to the general ledger export, the same process runs in about eight minutes with a single refresh. The initial setup takes a few hours, but it pays for itself within the first two reporting cycles. One limitation you should be aware of: Excel is not a database. If your model grows beyond fifteen thousand rows of data or requires concurrent access from multiple users, you will hit performance walls that no amount of optimization will resolve. In those cases, moving the calculation engine to a proper data platform and using Excel only as a presentation layer is the correct architecture. I have seen teams try to force Excel to handle transaction-level data for a mid-size subsidiary with forty thousand journal entries per month. The file became unstable, calculations queued for hours, and the model eventually failed during a critical reporting deadline. Switching to a database-backed solution with a simplified Excel front-end resolved the issue completely.
When Financial Analysis Using Excel Is the Wrong Tool
Excel breaks down in three specific situations. First, when you need real-time data feeds from multiple external systems and the latency of manual refresh becomes a bottleneck. Second, when collaborative editing is required across a team, because Excel's version control is primitive compared to purpose-built planning platforms. Third, when regulatory or audit requirements demand an auditable calculation trail that Excel cannot reliably provide, since formulas can be overwritten without any record of what changed and when. In those cases, tools like Anaplan, Planful, or even a custom Python-based pipeline are more appropriate. Excel remains the best tool for individual analysis, prototyping, and small to medium models where flexibility matters more than governance. Knowing when to stop using it is as important as knowing how to use it well. The single most useful habit you can develop is testing every model before you share it. Run the numbers through a full fiscal year at minimum. Check that the balance sheet balances in every period. Verify that year-over-year changes make sense. Look for negative values where they should not exist. A model that passes these basic sanity checks is already ahead of most spreadsheets you will encounter in practice.