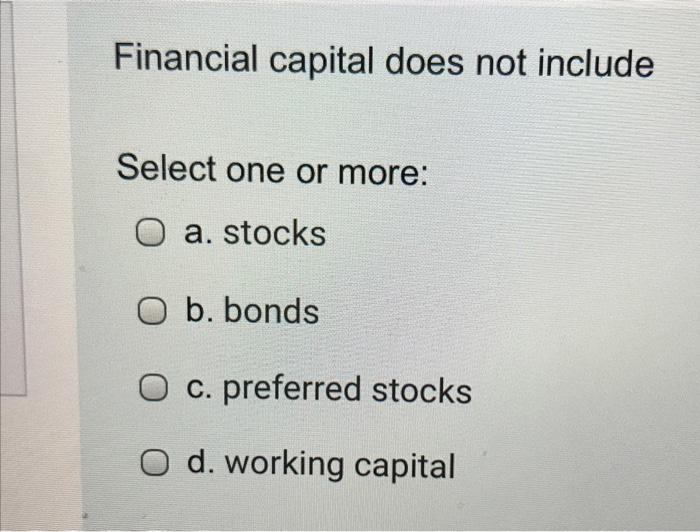
Understanding What Doesn't Count As Financial Capital
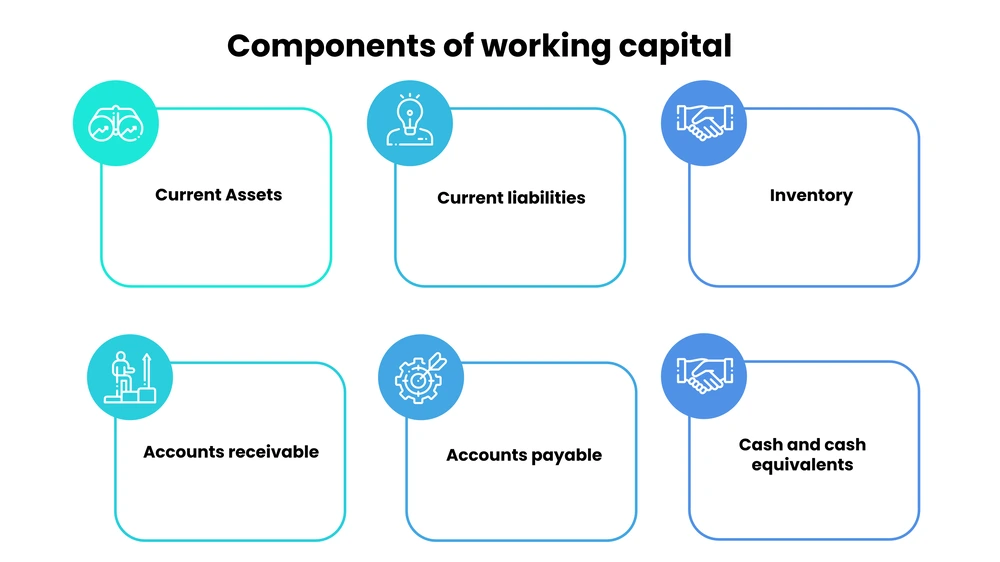
I ran into this question repeatedly when helping companies prepare balance sheets and internal audits. People get tripped up because they conflate everything of value with financial capital. It is a common mistake, and it has real consequences when you are trying to raise funding or present financials to investors. Financial capital refers strictly to monetary resources available for investment or operational use. This means cash, stocks, bonds, retained earnings, and lines of credit. That is the core definition. Everything else exists in separate categories on the balance sheet, even though all of it contributes to the overall value of a business. Physical assets like machinery, buildings, and inventory are recorded separately as fixed assets or current assets. They have book value and fair market value, but they are not financial capital. If you own a factory worth two million dollars, that does not mean you have two million dollars in financial capital to deploy elsewhere. I learned this the hard way early in my career. A client once tried to use the appraised value of their equipment as leverage for a working capital loan. The lender laughed them out of the room. Equipment is collateral at best. It is not liquidity. The workaround in that situation was to refinance through a secured equipment loan instead, which took about three weeks longer but actually got the capital deployed.
Natural resources fall into the same trap. Timber reserves, mineral rights, oil deposits — these are real assets with real value, but they sit in completely different accounting categories. They are subject to depletion schedules, not depreciation. Valuation is speculative until extraction begins. A mine might be worth billions on paper, but if there is no production revenue yet, it contributes zero to financial capital. Human capital is the most misunderstood category. Employee expertise, institutional knowledge, leadership quality — all valuable, all critical to performance, and all invisible on the balance sheet under standard accounting principles. You cannot borrow against your best engineer. I have seen startups try to pitch their talent roster as an asset base during fundraising rounds. It helps emotionally with investors, but it does not change the numbers. Financial capital is quantified. Human capital is qualitative, and that distinction matters when you are running ratios or calculating return on equity. Intellectual property is another area where people get confused. Patents, trademarks, and proprietary technology absolutely have financial value, and under certain conditions they can be capitalized. But they are not financial capital. They are intangible assets. The difference matters because intangible assets face impairment testing, amortization requirements, and valuation uncertainty. A patent portfolio might be worth millions, but it cannot pay payroll next month. Financial capital can. The only exception I will note is when IP is pledged as collateral for a loan — then it indirectly generates financial capital through debt financing, but that is a transactional conversion, not an inherent equivalence.
The counter-intuitive part that beginners miss is that financial capital can actually decrease while the company grows. This happens when you reinvest retained earnings into physical or intangible assets. Your total asset base expands, but your liquid financial capital shrinks. I have watched healthy companies face cash crunches precisely because their growth consumed their financial capital faster than it was replenished through operations. The fix is usually either factoring receivables or establishing a committed line of credit before the shortage hits, rather than trying to secure one when you are already short. Another nuance that gets overlooked involves lease obligations under ASC 842. Operating leases now appear on the balance sheet as right-of-use assets and lease liabilities, but they do not constitute financial capital. They are financing obligations that consume cash flow. When lenders calculate debt service coverage ratios, they look at your actual cash position, not your lease assets. A company can have a massive balance sheet full of leased equipment and still have negative financial capital if its cash reserves are depleted. The practical takeaway is straightforward. When you are preparing financial statements, raising capital, or presenting to stakeholders, keep the categories separate. Financial capital is the liquid, deployable money. Everything else is an asset of a different type with its own accounting treatment, its own risks, and its own valuation methods. Mixing them up will cost you time, credibility, and sometimes funding. I recommend running a quick reconciliation each quarter where you list all asset categories side by side and explicitly note which portion qualifies as financial capital. This habit catches misclassifications before they become problems and takes maybe twenty minutes per quarter depending on company size.
Get the Full Details
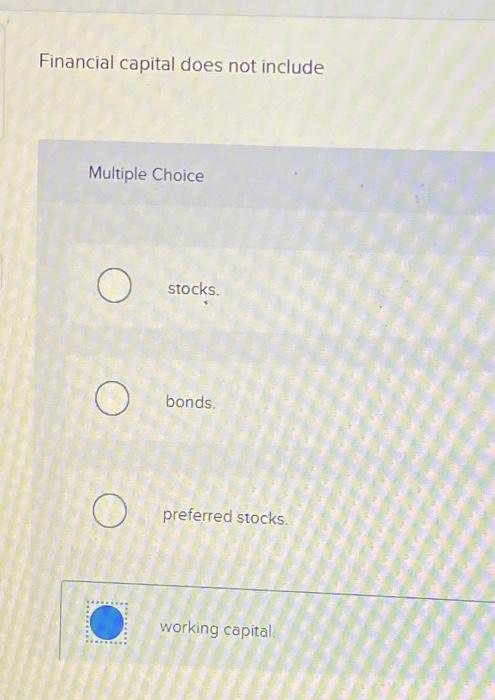
Why the Distinction Matters in Practice
The reason this classification matters beyond accounting purity is that every financial decision maps differently depending on whether you are working with financial capital or another asset class. Taking a loan increases financial capital but adds a liability. Selling equipment converts a fixed asset into financial capital but reduces your productive capacity. Issuing stock increases financial capital and equity simultaneously but dilutes ownership. Each move has a different impact on your capital structure, your risk profile, and your control. If you are building a financial model or preparing for an audit, spending ten minutes clarifying what falls into each category prevents hours of back-and-forth with auditors and lenders who will ask for breakdowns. The process is not complicated, but it requires discipline. Most errors happen because someone copies a line item from one section of the balance sheet into another without checking the classification rules first. That is an easy mistake to make and a costly one to correct later.