What Actually Matters in a Financial Controller's Dashboard
Most organizations track the same five or six metrics and call it a day. That's fine for baseline reporting, but it leaves a lot on the table. The real work of a financial controller sits somewhere between pure accounting and operational strategy, and your KPIs should reflect that without turning into a 40-item spreadsheet nobody opens.
I've sat through more than a few board meetings where someone presented twenty-one KPIs and then we spent twenty minutes arguing about which denominator to use for days sales outstanding. You'll save yourself that headache by starting narrow and expanding only when you actually need the signal.
Financial Controller Kpi Examples
Here are the ones I typically see hold up under scrutiny versus the ones that quietly become noise.
- Operating Cash Flow Margin — Operating cash flow divided by revenue. This tells you whether the business model actually converts sales into cash or just into receivables. A lot of companies post healthy net income and still get squeezed because AR growth outpaces revenue growth.
- Days Sales Outstanding (DSO) — Standard but essential. Track it by customer segment, not as a single blended number. One large account that's thirty days past terms will flatten your average and hide the real collection problem.
- Monthly Variance Rate — The percentage of P&L line items that move more than a set threshold from budget. If this number is consistently near zero, your budget is wrong, not your performance. I've seen this happen repeatedly with companies using static annual budgets in fast-moving environments.
- Cost per Transaction Processed — Relevant if you're running accounts payable or accounts receivable in-house. Cuts down dramatically when you automate matching, but plateaus once you hit about eighty percent automation. Beyond that point, the remaining twenty percent costs more to chase than the system saves.
- Financial Close Cycle Time — Calendar days from period end to finalized books. Anything under ten business days in a mid-market company is solid. The bottleneck is almost never the journal entries themselves; it's the wait for subsidiary data and intercompany reconciliations.
- Capex as Percentage of Revenue — Helps flag whether the business is over- or under-investing relative to its sector norms. Worth tracking quarterly rather than monthly since capex is lumpy and timing distorts the picture.
- Headcount Cost Efficiency — Total compensation divided by headcount, broken down by department. Useful for spotting comp creep before it shows up in the P&L. I flagged one division where average comp was rising four percent year-over-year while output was flat, which saved us from an unpleasant surprise at year-end.
None of these require expensive tools. Most finance teams run them out of Excel or whatever BI layer they already have. The difference between a KPI that informs decisions and one that becomes decorative usually comes down to how frequently it's reviewed and whether it's tied to a clear owner.
How to Actually Implement These Without Burning Out
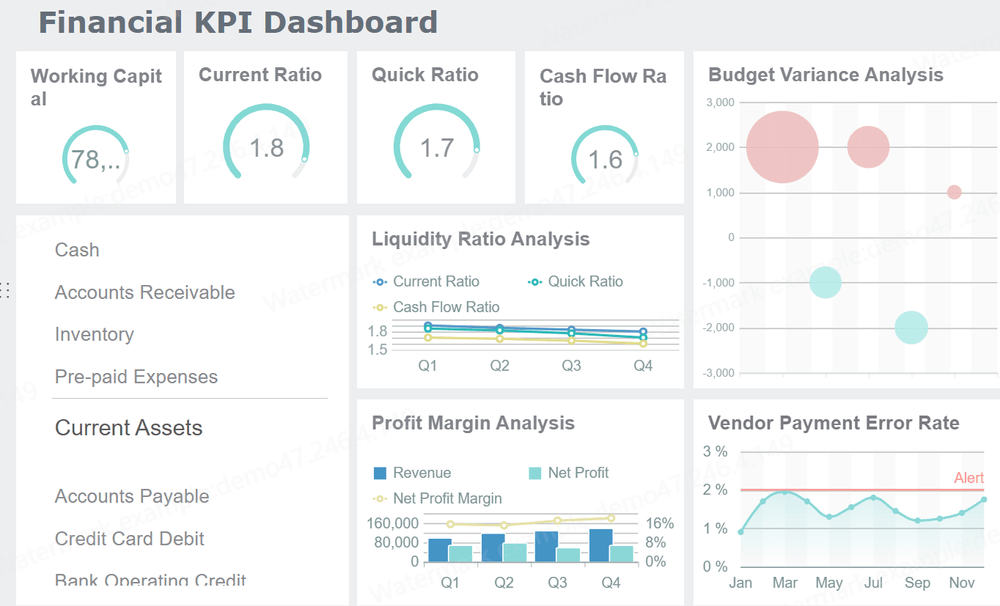
Start with three. Pick the ones where you already have the data source and the leadership team actually asks about the metric quarterly. Roll them out together with a single-page dashboard that shows trend, not just a snapshot. When people can see whether a number is improving or deteriorating across six months, they make different decisions than when they're looking at a single month's figure.
Build the definitions into a one-page glossary and send it around before you launch anything. Ambiguity around what counts as "revenue" or whether you're including or excluding a specific expense line will create more debates than insights within the first two reporting cycles.
I ran into a specific problem last year where our DSO calculation included a few intercompany balances that shouldn't have been there. The numbers looked fine at first glance, but when I cross-referenced the subledger detail, I found that three entities were netting their payables against their receivables internally, which compressed DSO by about nine days. That looked good until you realized it masked a genuine collection slowdown in our external customer base. The fix was straightforward: strip all intercompany from the DSO formula and report it separately. It also meant the external DSO jumped to a level that forced us to take a harder look at our credit terms for our top five accounts.
Common Pitfalls I Keep Seeing
Tracking too many KPIs at once is the biggest one. People treat it like a volume game. More metrics means more coverage but also more noise and diluted accountability. I've watched teams drop a metric within sixty days because nobody could remember which department was responsible for moving it.
Another trap is optimizing for the number instead of the outcome. If you set a target of reducing close cycle time to seven days and your controllers start cutting corners on review steps to hit it, you've created a control weakness. Tie the metric to a quality gate. Close speed doesn't count if the auditors come back with findings.
Budget rigidity also wrecks variance analysis. I worked with a manufacturing client where the budget was set in January and never updated despite a forty percent commodity price swing in March. Their monthly variance report looked alarming every single month, but the variance wasn't operational; it was structural. They switched to a rolling three-month forecast after that and the variance conversation became productive again instead of just defensive.
What These Metrics Miss
KPIs are lagging indicators by nature. They tell you what happened, not why. A DSO increase doesn't explain whether it's bad weather in the Gulf Coast delaying shipments, a new customer on net-90 terms, or a single billing error in your invoicing system. You need to pair the number with a brief qualitative note each period so the context stays attached to the data.
They also don't capture forward-looking risk well. Financial Controller Kpi Examples like operating cash flow margin are excellent for assessing current health, but they won't warn you about a customer concentration issue or a looming covenant breach until the damage is already visible on the statements. Adding a simple customer concentration ratio and a covenant compliance tracker alongside the standard KPIs gives you much earlier signals.
If you're in a high-growth environment where traditional accrual metrics distort reality, you might be better off leading with cash burn rate and runway rather than net income. Those two numbers tell the actual story in that context. Net income gets you to an answer nobody's asking.