Getting Through Credit Union Support Without Losing Your Mind
Most people think credit union customer service is basically the same as a bank's call center, just friendlier. That is not quite right. The differences matter if you actually need help and want it resolved without spending three hours on hold. I dealt with this head-on when I was trying to get a credit dispute resolved for a member. The credit union in question had layered their dispute resolution through a completely separate department that was not listed on any phone menu. You would call the main number, get routed to the general service line, and then spend twenty minutes explaining the problem to someone who could not access the disputes system at all. They told me the only way was to write a certified letter. I tried that. It took six weeks to get a response, and by then the dispute window was closing. The workaround was finding the specific director of member relations for our region on LinkedIn, sending them a direct message with the case number, and asking them to escalate internally. That got it moved to the right team within forty-eight hours. It is not a great system, but knowing how to sidestep it makes a huge difference.
What Financial Credit Union Customer Service Actually Covers
At a basic level, credit union customer service handles account inquiries, loan questions, card issues, and dispute resolution. But the operational structure is where things get interesting. Unlike banks, credit unions are member-owned, which means their service model is supposed to be more member-centric. In practice, that translates to shorter wait times on the phone and representatives who sometimes have more authority to make exceptions without escalating to a manager. There is a tradeoff though. Many credit unions operate on legacy core banking platforms that are not very modern. When I was troubleshooting a recurring automatic payment error for a client, the representative could see the transaction in the system but had no ability to modify the recurring schedule through their interface. They had to submit a back-office request form that took five to seven business days to process. A major bank would have likely handled that in real-time through a different platform. The services breakdown tends to go like this. Phone support is your first line. Email support exists but response times vary wildly depending on the credit union's size. A 50,000-member credit union might respond to emails in two days. A 500,000-member one might take a week. Mobile chat features are becoming more common but are usually limited to simple questions like balance checks or card activation. Complex issues still require a phone call or an in-branch visit.
One thing that catches people off guard is that many credit unions do not have 24/7 phone support. Their live agent hours are typically Monday through Friday, 8 AM to 6 PM local time. If you lose your debit card on a Saturday night, your options are limited. Some credit unions offer a recorded hotline for reporting lost cards after hours, but that only covers the initial freeze. Getting a replacement card issued usually requires waiting until the next business day.
Get the Full Details
Practical Steps When You Need Help
Call during the least busy windows if you can. Early morning between 8 and 9 AM right when they open tends to have shorter hold times. Mid-afternoon on weekdays is also usually lighter. Avoid the end of the month and the beginning of the month when payment cycles create spikes in call volume. I have seen hold times stretch to forty-five minutes during those windows compared to about six minutes at other times. Have your account information ready before you dial. Full account number, the last four digits of your Social Security number, and a government-issued ID. Credit unions tend to be stricter about verification than big banks because of their fiduciary relationship with members. They will ask for multiple pieces of information and will not budge if you cannot provide them. I once spent an hour on hold trying to verify an account because the email address on file was outdated and they would not proceed without it. Getting that updated through a secure message in their online banking portal resolved the issue, but it cost me the entire day. When dealing with disputes, always request a case or reference number. Write it down. Follow up in writing within forty-eight hours referencing that number. Verbal promises from representatives are not binding in most cases, and the paper trail is what moves things forward. I handled a fraudulent charge dispute where the representative verbally confirmed the charge was reversed. Two weeks later, the charge was still showing on my statement. I pulled up the case number, called back, and had the entire claim re-opened and processed within four business days. The difference was having the documentation to reference.
For loan-related issues, which is one of the areas where credit union service tends to stand out, you should ask for a dedicated loan officer rather than routing through general support. Loan questions often require knowledge of underwriting guidelines and rate lock policies that general service reps do not have. Being transferred three times and having to repeat your situation each time is common. Asking upfront for the loan department directly saves significant time.
When Phone Support Is Not the Answer
Some credit unions have moved toward digital-first support models. This can mean better response times for simple issues and worse ones for complex problems. If your credit union offers an in-app messaging feature, use it for non-urgent matters. Document everything through the app so you have a timestamped record of the conversation. Phone calls leave no written record unless you record them, and not all states allow that. Branch visits are still relevant. If you have a recurring issue that phone support cannot resolve after two or three attempts, going in person with documentation often forces a resolution. Branch managers typically have more authority than call center representatives. I resolved a long-standing overcharge on a auto loan by walking into a branch with my payment history printed out. The manager reviewed it, identified the error, and processed a refund check the same day. That same issue had gone unresolved for three months over the phone. The downside to credit union customer service that nobody really talks about is staffing. Smaller credit unions frequently operate with lean teams. If your regular representative calls in sick or quits, you may not know who your new contact is. This is especially problematic for long-term relationships like mortgages or investment accounts. There is no centralized account management system that tracks your interaction history across staff changes. The onus is on you to maintain your own records of who you spoke with, when, and what was agreed to.
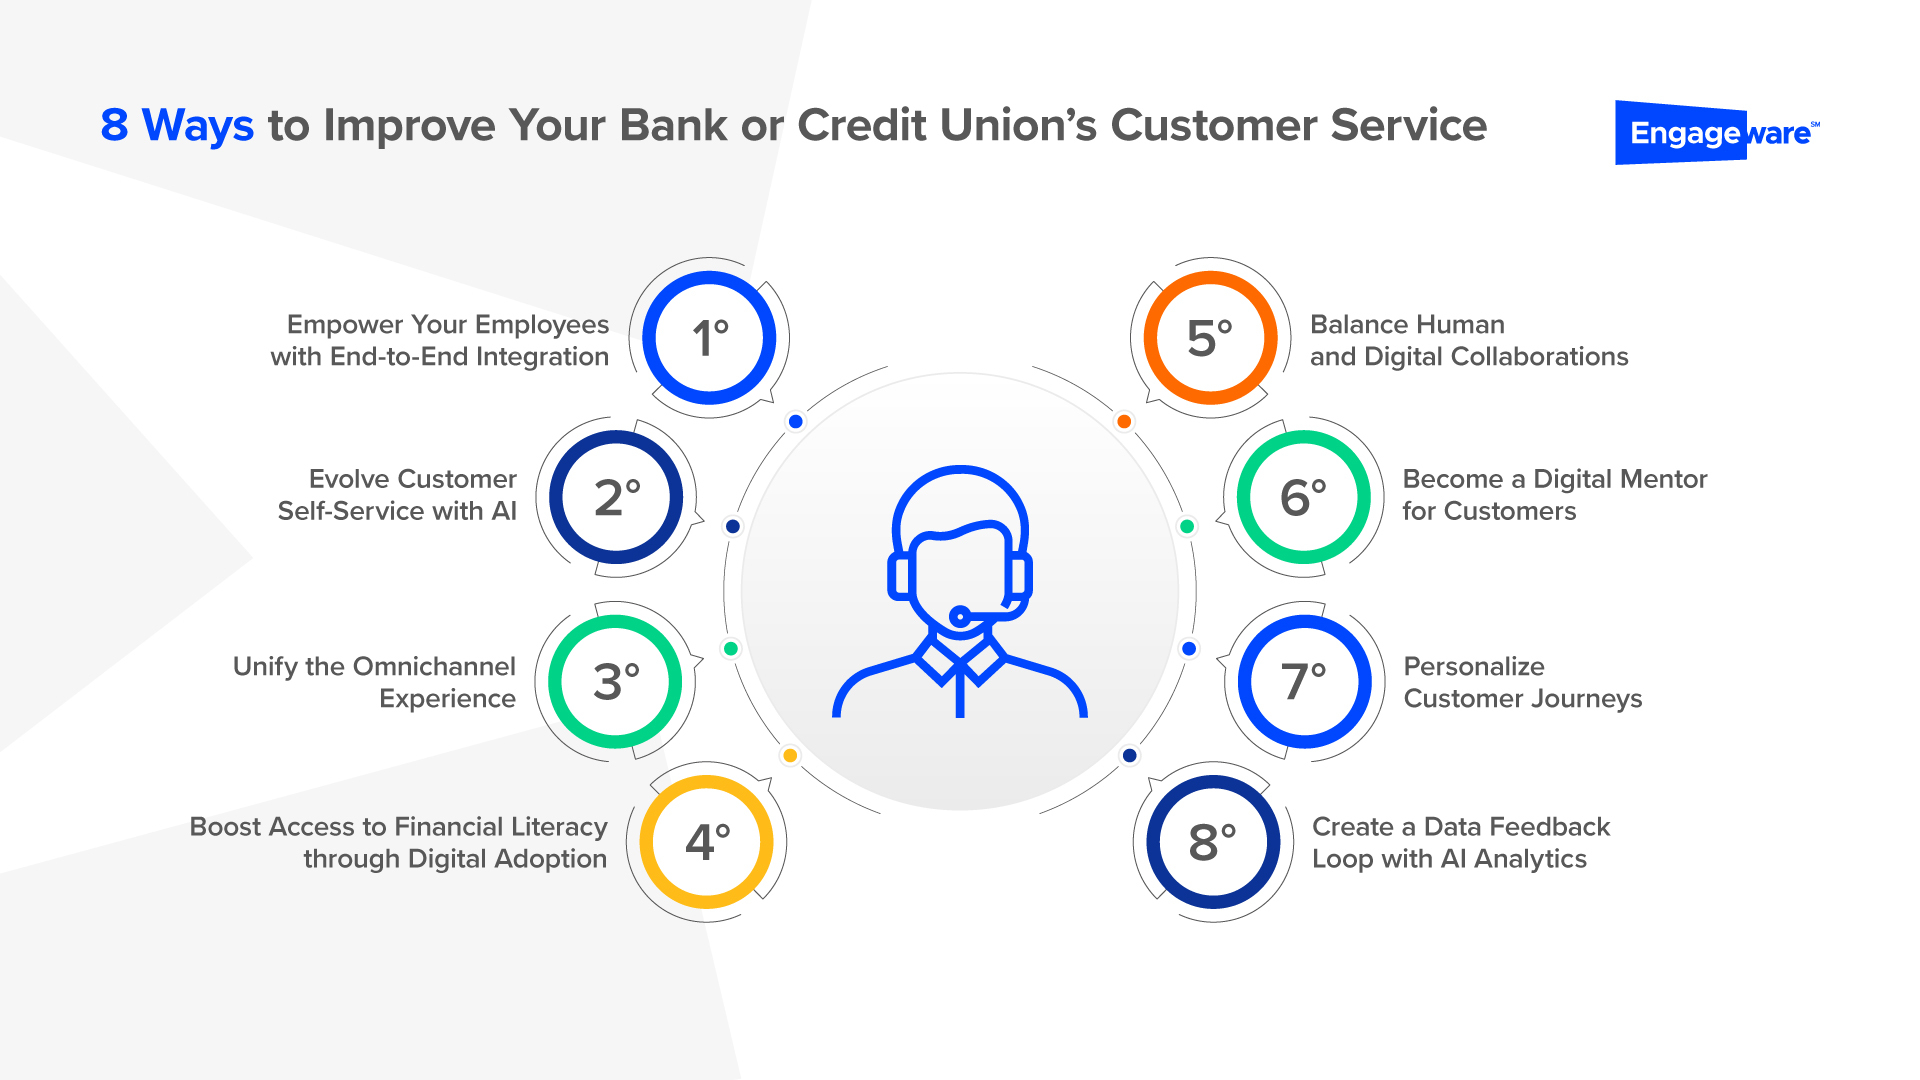
Another structural limitation is that many credit unions do not offer live chat support for security reasons. You might see a chat icon on their website, but it could be a basic bot that only answers FAQs about branch locations and hours. Escalating to a human through chat is not typically available. This is different from many digital-only banks that offer real-time chat with agents. If real-time text support is important to you, this is a factor to consider when choosing a credit union.
Counter-Intuitive Things Nobody Tells You
Being a credit union member does not automatically grant you priority support. I assumed it worked that way. It does not. Your membership status determines eligibility for products and rates, not service tier. If you want faster resolution, you need to advocate for it yourself. Ask for a supervisor when a representative cannot help you. Ask how long a typical resolution timeline is. Ask for your case to be documented in writing. Representatives are generally accommodating if you are polite but firm about wanting clarity. Another thing that surprises people is that credit unions often have longer processing times for certain transactions, even though they market themselves as more personal. A wire transfer that a big bank might complete same-day could take two to three business days at a credit union. This is because many smaller credit unions route their wire processing through third-party vendors rather than handling it in-house. It is worth asking about processing times before initiating any urgent transfers. Fee structures related to customer service interactions also differ. Some credit unions charge no fees for dispute investigations. Others charge a fee that is refunded only if the dispute is validated. I discovered this the hard way when a credit union charged me a twenty-five dollar investigation fee for a fraudulent charge claim. The dispute was ultimately validated, and the fee was refunded, but the delay in understanding this policy cost me patience and additional stress. Always ask about fees before initiating a formal dispute.
The biggest practical limitation of credit union customer service is geographic scope. If you travel frequently or live in multiple locations, many credit unions have limited branch networks. Out-of-network support can be difficult to access. Some credit unions partner with shared branching networks that allow you to conduct basic transactions at other credit union branches, but this does not extend to complex customer service requests. You may still need to contact your home branch for most issues, which becomes inconvenient if you are not in the area. If you are looking for alternatives, community banks are worth considering. They tend to have similar service models but may offer broader geographic coverage and more modern technology stacks. For purely digital needs, online banks provide faster support channels but sacrifice the personal relationship aspect that credit unions are known for. There is no perfect option. The best approach is understanding what you value most and choosing accordingly.