Why Most Financial Goal Setting Worksheets Fail Before They Even Start
I spent three years managing finances for a group of small business owners before I stopped trying to impress anyone with spreadsheet beauty. Here's the unvarnished truth: a Financial Goal Setting Worksheet isn't a motivational tool. It's a planning constraint engine. If you treat it like a vision board, you'll abandon it within sixty days. The actual value comes from forcing every goal into three fields: target amount, deadline, and monthly contribution. That's it. Everything else is noise. People add columns for "why this matters," inspirational images, progress bars, and color coding. None of that changes the math. The math is merciless and indifferent to your feelings about it.
Building a Financial Goal Setting Worksheet That Actually Works
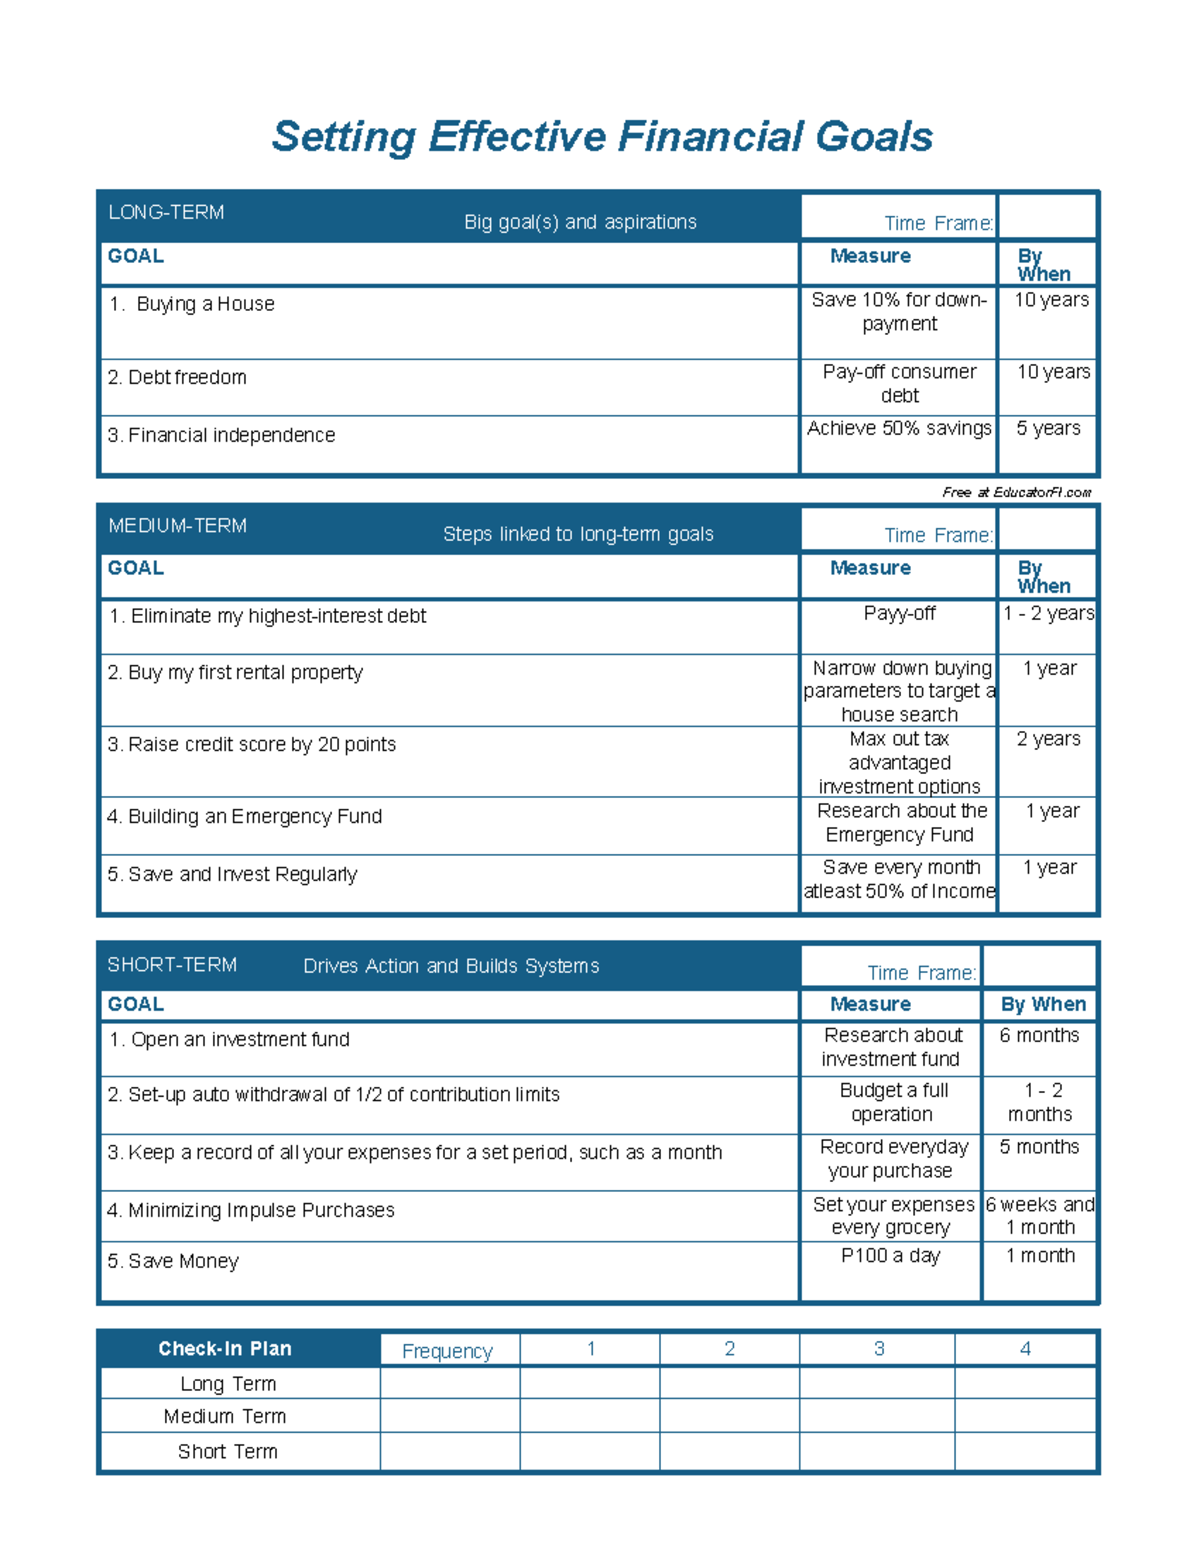
Open a blank spreadsheet. Set up these five columns at minimum: Goal Name, Target Amount, Deadline, Monthly Contribution Required, and Status. That's five columns, not fifteen. Anything beyond that is usually vanity formatting someone copied from a Pinterest template. Populate the rows with every financial thing you're trying to achieve. House down payment. Emergency fund. Debt elimination. Retirement catch-up. Business equipment purchase. Each row is independent until you get to the monthly contribution column, which is where most worksheets become useless. Here's the part nobody mentions: the monthly contribution column is a sum, not separate allocations. When you add up every monthly requirement across all your goals, you'll almost certainly get a number larger than your discretionary income. That's not a failure of the worksheet. That's the worksheet doing its job. It's showing you that your goals exceed your means, and you need to make decisions.
Some people hit a wall here and just stop. Others cut goals instead of adjusting timelines. I once had a client with seven active goals who wanted to hit every single deadline simultaneously. The math said no. What worked instead was grouping goals into tiers. Tier one got full funding. Tier two got partial funding at current rates. Tier three got deferred to a future date. This isn't giving up. This is resource allocation, which is literally what finance is. The worksheet should auto-calculate the monthly contribution based on a future value formula so you don't have to manually compute anything. For a simple savings goal, the formula is straightforward: divide the target amount by the number of months until the deadline, then adjust for any existing balance and expected interest rate. If your interest assumptions are rough, factor in a ten percent buffer on the monthly contribution to account for underperformance. Status should be a dropdown: Active, On Track, Adjusting, or Paused. You'll use this constantly. When an unexpected expense hits, you don't delete the goal. You move it to Adjusting, recalculate the monthly contribution for the remaining timeline, and resume when cash flow allows. This is where most people's systems break because they treat every change as a restart instead of a recalibration.
Get the Full Details

A Specific Problem That Broke My Workflow (And How I Fixed It)
About two years ago, I was running a Financial Goal Setting Worksheet for a client who had a variable-income side business. Standard monthly contribution calculations assumed steady cash flow. His didn't. The worksheet kept showing he should be putting away $2,400 per month toward his goals. His actual available cash averaged around $1,100 per month with a standard deviation of $800. The math on paper looked fine. The reality was he'd miss the target every single month and then feel guilty and abandon the system. The workaround was straightforward once I found it. I added a "Base Contribution" column and a "Variable Buffer" column. The base contribution was set to $800 per month — the amount he could reliably pay regardless of income fluctuation. The variable buffer absorbed the surplus from high-income months, capped at $600 to prevent overcommitment during outlier months. He stopped missing targets. Guilt disappeared. The system worked because it matched his actual behavior instead of his aspirational behavior. If you have irregular income, do not calculate monthly contributions based on your best-case month. Calculate based on your median month, then build in a buffer. Your worksheet will be more accurate and you'll actually use it.
Counter-Intuitive Things About Financial Goal Setting Worksheets
First, adding more goals to the worksheet often reduces execution quality. There's a cognitive load ceiling. Once you have more than six to eight active financial goals tracked simultaneously, the maintenance burden outweighs the planning benefit. People don't realize this until they've been updating thirty-seven-row spreadsheets for four months and still can't remember what row twelve was for. Cut goals. Move some to a separate long-term list that you review quarterly instead of monthly. Keep the worksheet lean. Second, including a "current balance" column is frequently more valuable than the target amount column itself. Most worksheets emphasize where you want to go and forget to track where you actually are. A gap between your current position and your target is the most important data point on the page. Without it, you're flying blind. Third, and this is the one most people miss: your worksheet should include a "constraint" column that notes what is preventing faster progress. For a debt payoff goal, the constraint might be minimum payment requirements. For a savings goal, it might be a hard cap on discretionary income. For retirement contributions, it might be employer match limits. Identifying the binding constraint on each goal tells you exactly where to apply additional resources. Without this, you're just throwing money at everything and wondering why nothing moves fast enough.
Where This Approach Completely Falls Apart
A Financial Goal Setting Worksheet is a static planning tool. It cannot adapt to market volatility in investment-based goals. If you're using the worksheet for retirement projections, those future value estimates assume consistent returns that don't exist in practice. A market downturn in year two of a ten-year goal doesn't show up in the worksheet until you manually adjust the numbers. The worksheet will continue displaying the same monthly contribution requirement even though the underlying assumptions have shifted. Similarly, the worksheet doesn't handle correlated risk. If two of your goals depend on the same income source and that source disappears, both goals fail simultaneously. The worksheet treats each row as independent. It won't warn you about this until it's too late. Run a separate stress test at least once a quarter where you remove one major income stream and see how many goals collapse. Finally, the worksheet encourages a false sense of precision. Entering "Target Amount: $47,320" sounds authoritative. It's arbitrary to the nearest dollar. No financial outcome is that precise. Round your targets. A target of $50,000 is easier to track, easier to adjust, and functionally identical to $47,320. The precision illusion makes you think you're in control when you're really just performing accuracy theater.

If you're looking for something more dynamic than a spreadsheet, consider pairing the worksheet with an automated budgeting tool that pulls actual account balances and adjusts projections in real time. The worksheet stays for planning. The automation handles the tracking. They complement each other. Using either alone leaves gaps.
Quick Walkthrough of One Complete Row
Goal Name: Emergency Fund
Target Amount: $15,000
Current Balance: $3,200
Deadline: 18 months from now
Monthly Contribution Required: $644 (calculated as ($15,000 - $3,200) / 18, adjusted for an assumed 4% annual return)
Constraint: Minimum wage job with no overtime availability
Status: On Track Notice the constraint column. That single entry tells you everything you need to know about why this goal might slip. If the constraint isn't addressed — whether through a raise, a second job, or a longer timeline — the monthly contribution is just a wish. Recording it makes the problem visible instead of hidden.
Download Template
I've put together a basic template with the five core columns, auto-calculated monthly contributions, and the constraint and status fields built in. It includes the future value formula for savings goals and a simple buffer row for variable income situations. You can download it here and fill in your own numbers. It's not polished. It works. The real work starts after you populate the first row. Updating it weekly takes about ten minutes. Ignoring it for three months and then trying to catch up usually takes two hours and ends with you deleting half the rows because you've lost track of which goals are still relevant. Keep it simple. Update it often. Adjust it ruthlessly when reality diverges from the plan. The worksheet is a tool, not a commitment device. It serves you. You don't serve it.