Writing a Financial Hardship Letter That Actually Gets Results
A financial hardship letter is a formal document you send to a creditor, lender, or collection agency explaining that you cannot meet your current payment obligations due to circumstances beyond your control. It is usually the first step toward requesting a modified payment plan, a temporary forbearance, or a reduction in interest. Most people think this is just a cover letter for a negotiation. It is not. It is evidence. I spent about four years working collections before moving to the borrower advocacy side. What I learned is that most hardship letters get rejected or ignored because they read like emotional pleas instead of documented requests. The lender already knows you are hurting. They need to know why their specific policy applies to your situation.
What Goes Into a Financial Hardship Letter
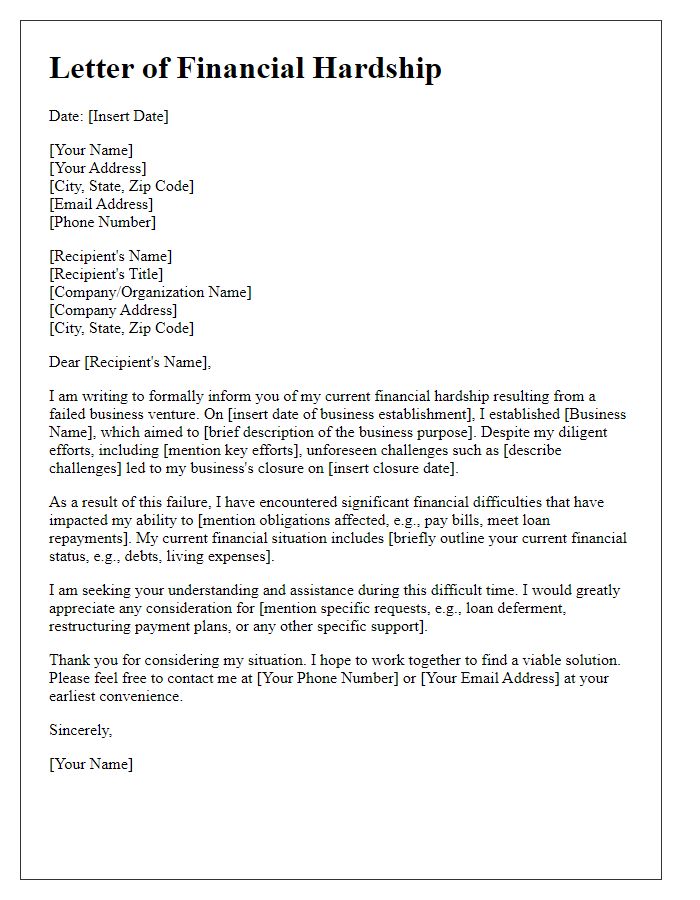
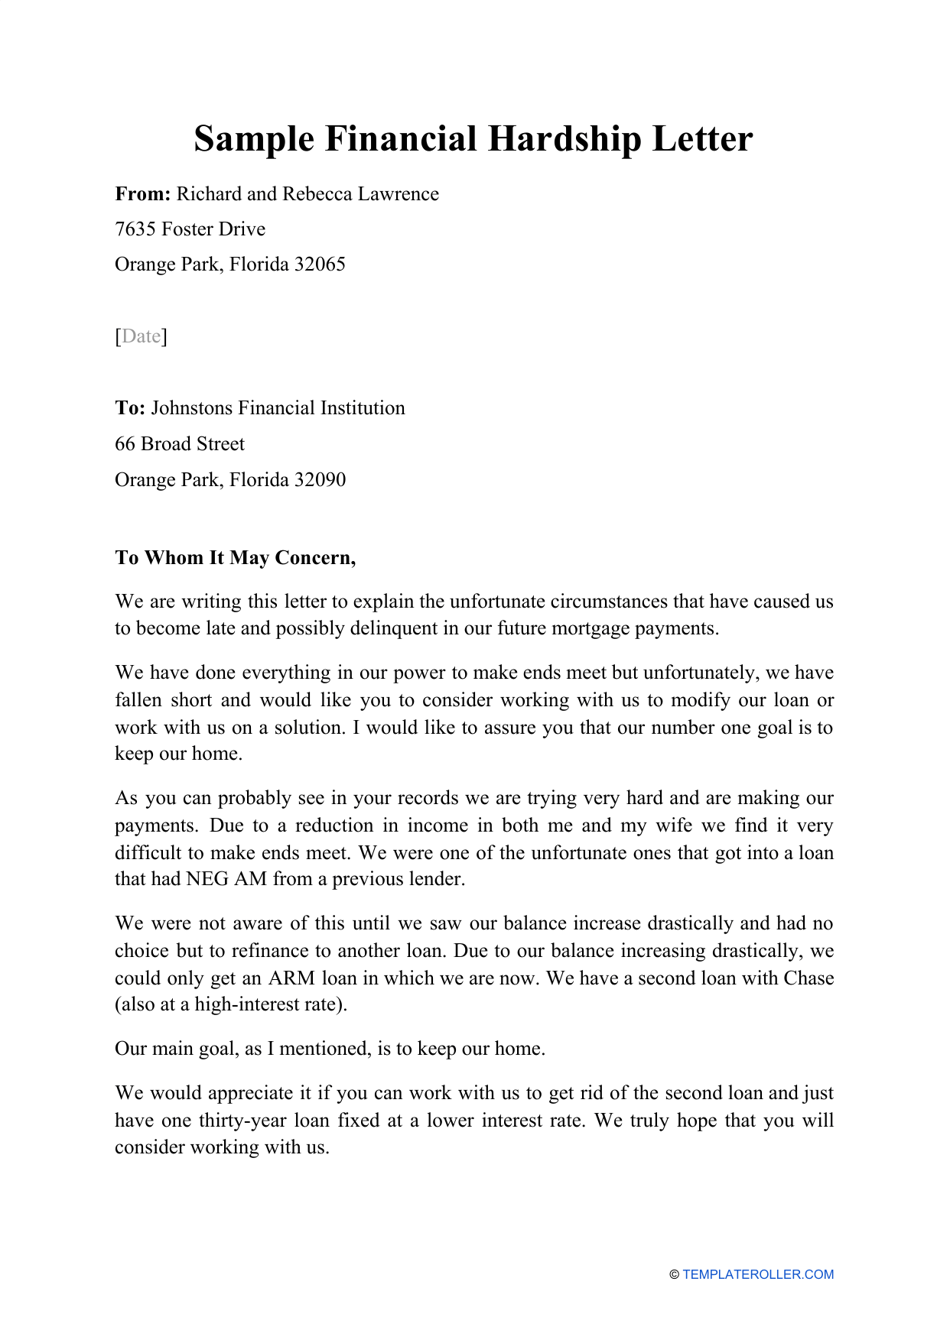
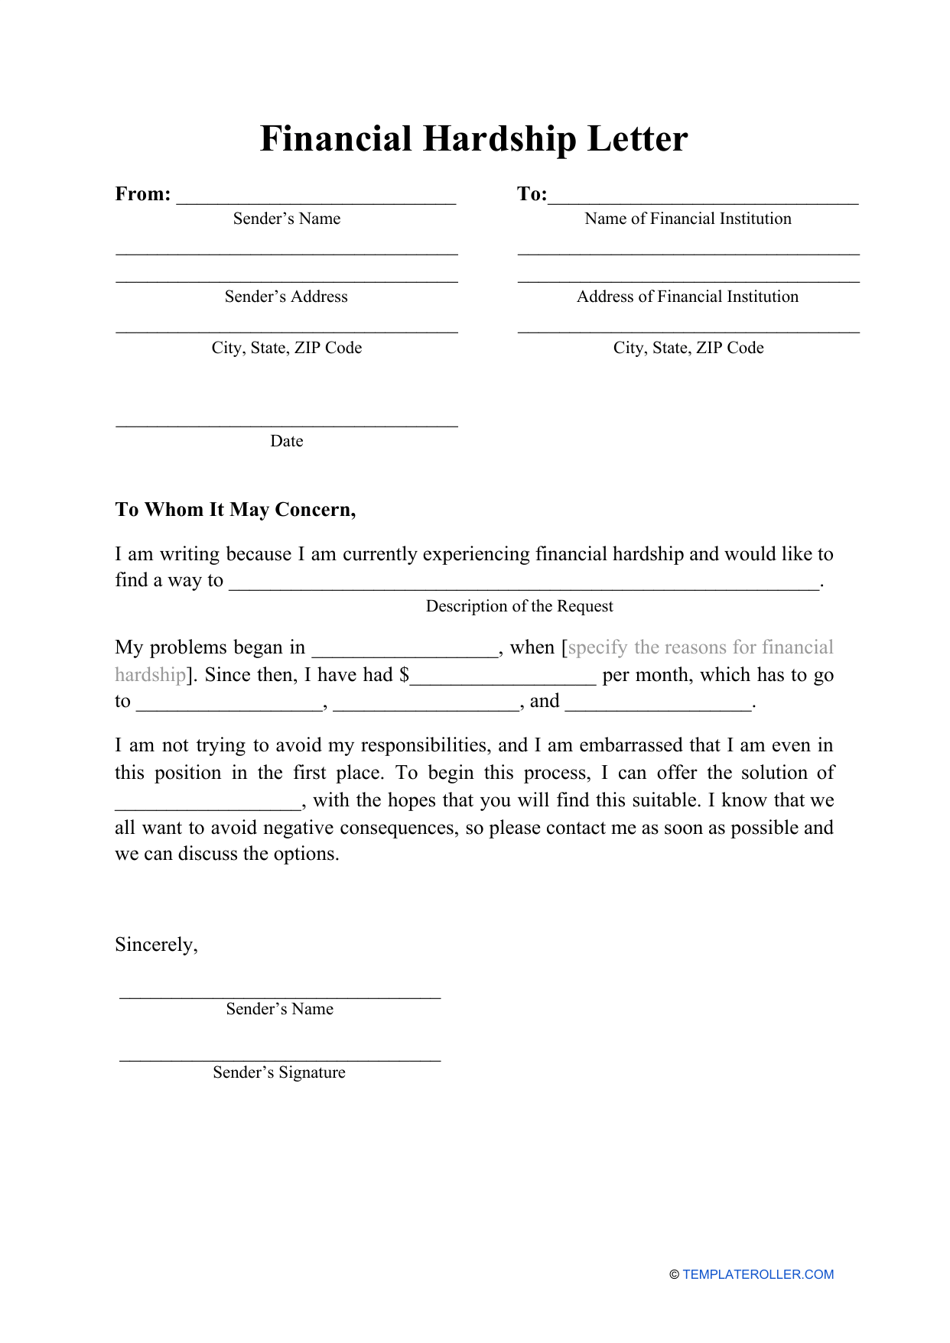
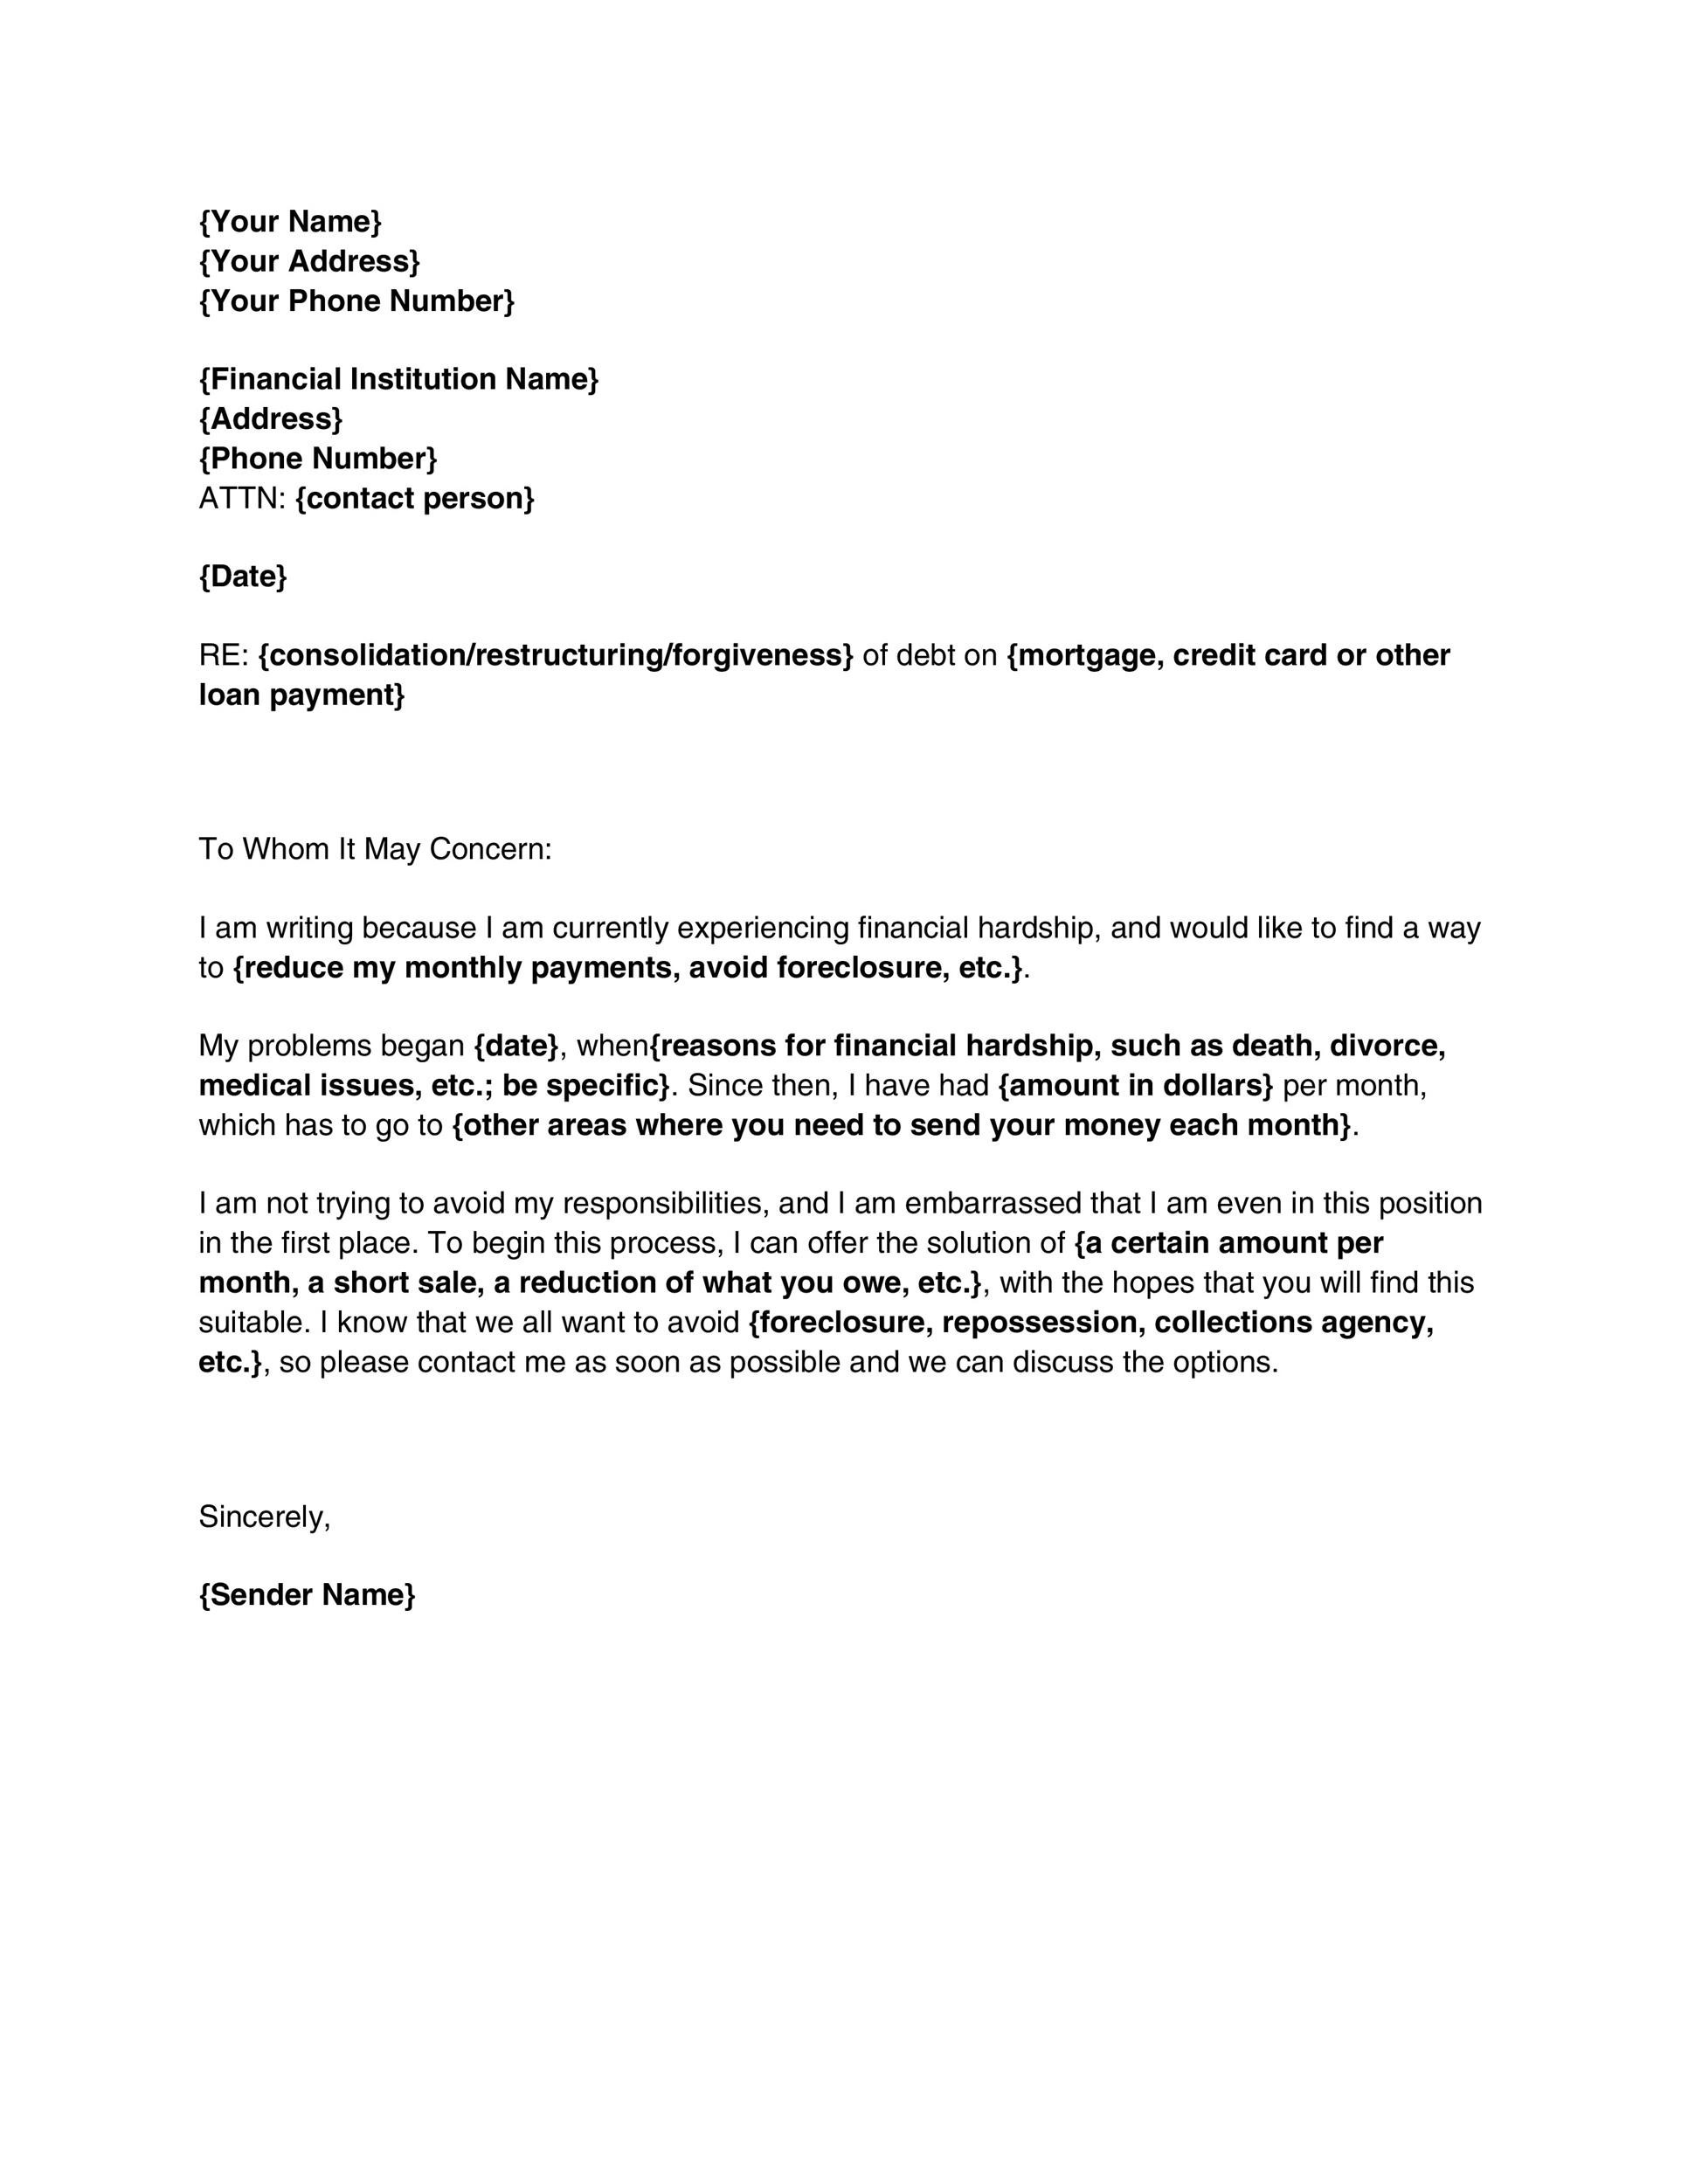
A standard hardship letter needs five things, in this order, with no fluff between them. 1. Your account information. Full name, account number, and the exact address on file. If you have multiple accounts with the same lender, list each one separately. Missing even one digit is enough for them to delay processing by two to three weeks while they look you up manually. 2. The hardship event. State what happened. Medical emergency, job loss, divorce, death in the family, natural disaster. One sentence. No storytelling. "I was laid off from my position as a regional logistics coordinator on March 12, 2024" works. "I went through such a terrible time and it felt like everything fell apart all at once" gets deleted.
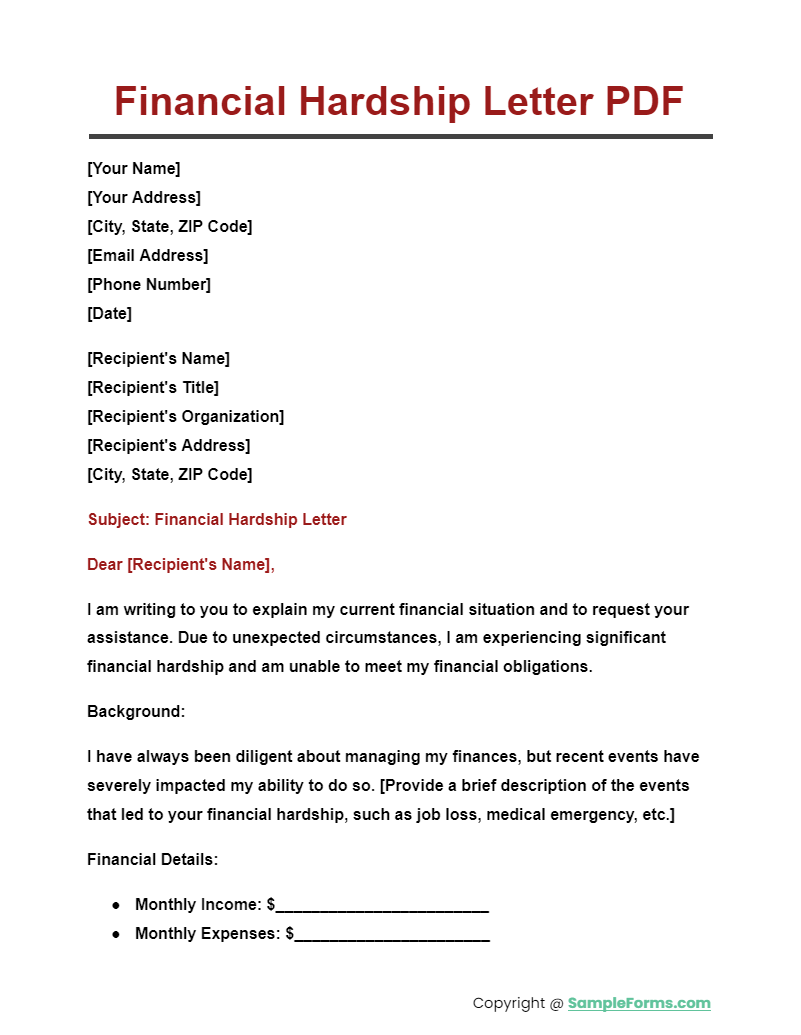
3. The financial impact. This is where most people mess up. You need to show the delta between your monthly income and expenses before and after the hardship event. Include a simple table if it helps. Here is what I typically tell clients to include: Monthly income before hardship: $4,200
Monthly income after hardship: $1,100 (unemployment)
Essential monthly expenses: $3,800
Shortfall: $2,700 per month 4. The specific relief you are requesting. Do not ask for "help." Ask for a 12-month payment deferral, a reduction to $150 per month for six months, or a partial principal forgiveness. Vague requests get vague rejections or worse, automatic denials. Specific requests can be approved, modified, or denied — which means you actually get a decision.
Get the Full Details
5. Supporting documentation references. Attach a termination letter, a doctor's note, a death certificate, or a bankruptcy filing notice. Reference each attachment by name in the letter itself. "Please find attached my termination letter dated March 15, 2024." This signals that you have organized everything and makes the adjuster's job easier, which increases the chance they process your letter quickly instead of shelving it. I once had a client who sent a three-page narrative about her husband's cancer treatment and how it affected their entire family. She never mentioned his account number in the body of the letter. They denied it on the grounds that they could not verify the account associated with the hardship. We resubmitted with the account number in the first sentence and a two-page summary attached. It was approved within 11 business days.
The Process Nobody Talks About
Writing the letter is the easy part. Getting it reviewed by someone with decision-making authority is where it falls apart. Most lenders route hardship letters through an automated intake system first. The system scans for keywords like "hardship," "financial difficulty," "request modification." If your letter does not contain the right language, it gets routed to a general customer service queue, which typically has zero authority to modify terms. Your letter sits there for 30 to 45 days while someone reads it and sends a form-letter denial. The workaround is to address the letter directly to the "Loss Mitigation Department" or "Hardship Assistance Unit" and mark it "Attn: Loss Mitigation Specialist." Use certified mail with return receipt requested if you are mailing a physical copy. If you are submitting online, request a confirmation number and note it in the letter. Follow up by phone on day 10. Say exactly this: "I submitted a hardship letter on [date] with confirmation number [number]. Has it been assigned to a loss mitigation specialist yet?" Most of the time the answer is no, and then you can escalate it yourself before it gets buried.
I also recommend calling the lender's main line and asking for the direct phone number of the department that handles hardship applications. Not the retention team. Not the collections team. The hardship or loss mitigation department. Write that number down. Reference it in your letter. It creates a paper trail that proves you attempted direct contact, which matters if you ever need to dispute a denial later.
When a Financial Hardship Letter Is Not Enough
There are situations where a hardship letter will not change anything. If you are behind on payments and the account has already been charged off and sold to a third-party collection agency, the original creditor no longer owns your debt. They cannot modify your terms. The new owner operates under completely different policies, and most of them do not have a loss mitigation department at all. They make one offer, take it or leave it, and move on. If your account is in active default and the lender has already initiated foreclosure or repossession proceedings, a hardship letter may pause the process for 30 to 60 days, but it will not stop it permanently. In those cases, you need to pair the letter with a formal workout application or a legal motion, depending on your jurisdiction and the type of debt. Another common failure point: creditors sometimes deny hardship letters if the hardship does not appear permanent or long-term. A two-week delay due to a delayed paycheck is not a hardship in their framework. They are looking for events that will affect your ability to pay for at least three to six months. A temporary cash flow issue gets a different response — usually a suggestion to set up a one-time payment plan, not a formal hardship modification.
If the hardship letter gets denied, you are not out of options. You can appeal the denial in writing within 30 days, provide additional documentation, or request a review by a different specialist. Some lenders allow you to resubmit with corrected or supplemental materials. Others require you to start the entire process over. Check your original denial letter carefully — it should cite the specific policy reason for the denial, and that reason determines whether an appeal is worth pursuing.
What to Expect After You Submit It
Processing times vary widely. A well-documented letter submitted to a large bank through their online portal typically receives an initial response within 15 to 30 business days. Credit unions and smaller community banks may take longer because they have fewer staff in the loss mitigation department. Online lenders and fintech companies sometimes respond faster, but their approval criteria are narrower and their modification options are limited. Do not assume silence means rejection. I have seen letters sit in processing queues for 45 days because the adjustor was waiting for a second verification document. Keep a log of every interaction — dates, names, confirmation numbers. If you do not hear back within 30 days, call and ask for a status update. Reference your submission date and confirmation number. If they still have not assigned it, ask to speak to a supervisor and request that it be expedited. When you do get a response, read it carefully. An approval letter should specify the new payment amount, the duration of the modified terms, whether interest will continue to accrue, and what happens to any past-due balance. If anything is unclear, do not sign and return the agreement until you get it clarified in writing. Verbal assurances mean nothing if the written contract says something different.
A denial is not the end of the conversation either, but it changes what you do next. Before you appeal or try another approach, understand exactly why it was denied. Was it insufficient documentation? Did the hardship not meet their definition? Was the account already in foreclosure? The reason determines the next step. If it was insufficient documentation, gather what is missing and resubmit. If the hardship did not meet their definition, consider whether a different program might apply, such as a general payment plan or a settlement offer instead of a formal hardship modification.