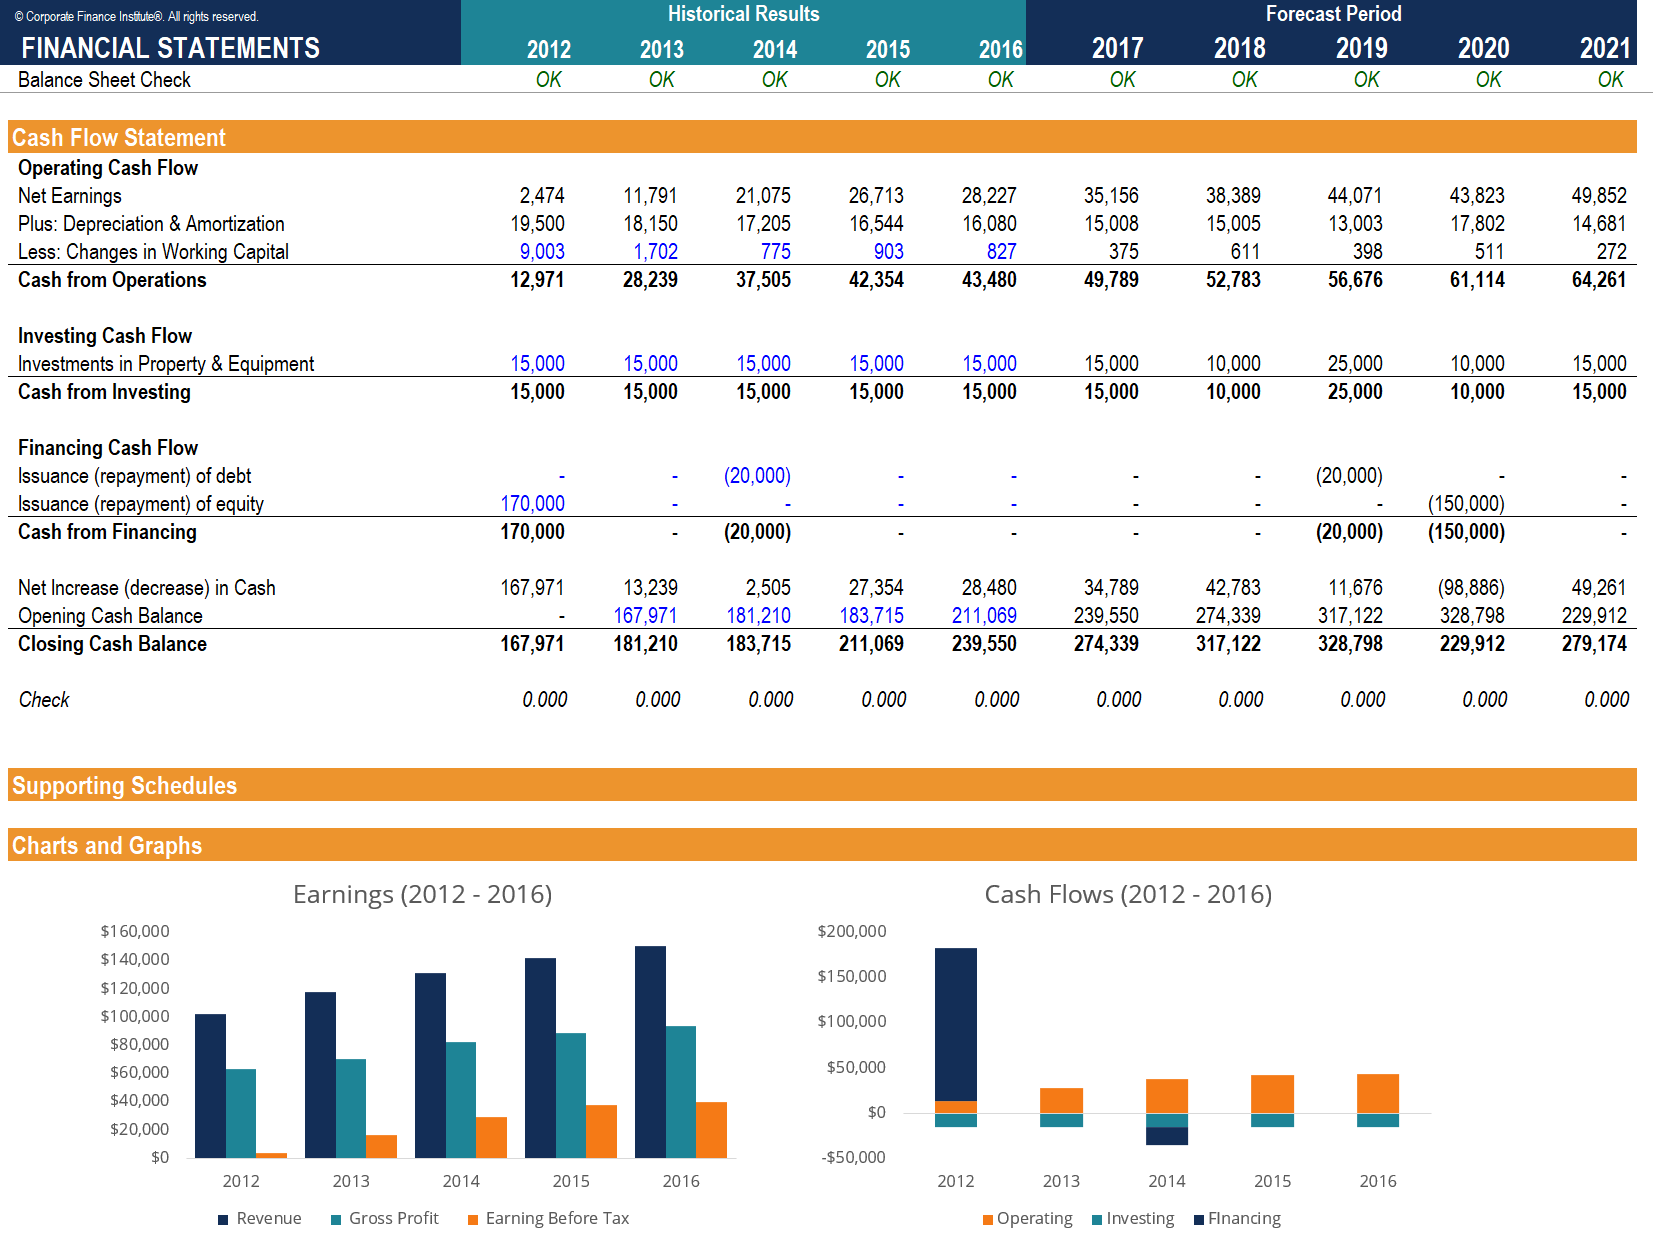
Building financial models without getting bogged down in spreadsheet hell
Product managers don't need to become accountants, but they do need to build models that survive a product review with finance. The real problem isn't knowing what NPV means. It's building something that doesn't fall apart when someone changes an assumption halfway through. I learned this the hard way three years ago when I built a customer acquisition cost model for a subscription product. I had everything in one sheet—revenue projections, churn assumptions, CAC by channel, and LTV calculations all tangled together. Finance asked me to change the monthly churn rate from 4.2% to 5.1%, and suddenly my entire model was broken because three separate LTV formulas pulled from different cells that I'd already updated inconsistently. I spent six hours fixing it. Now I separate the assumption layer from the calculation layer strictly. Every input goes into a dedicated section at the top of the sheet, color-coded differently, and every formula below references those cells only. Changed one assumption, everything updates automatically. Takes about five minutes longer upfront to set up. Saved me countless hours after that.
The practical process most people skip
Before you open Excel, write down the specific question the model needs to answer. Not "should we launch this feature?" but "will adding this pricing tier generate enough incremental revenue to cover the estimated engineering costs within 18 months, assuming a 30% adoption rate among existing users?" That specificity determines everything about how you structure the model. A yes/no feasibility check needs a completely different shape than a multi-year forecast. Financial Modeling For Product Managers is basically just translating product decisions into numbers that map to business outcomes. You identify the key variables, estimate them with the best data you have, link them together, and stress-test the result. That's it. The skill is in the variables you choose and how you handle uncertainty. Here's what actually happens in practice. You pull historical data if it exists—conversion rates, engagement metrics, cohort retention. If you're modeling something new with no history, you make your best guess and flag it clearly. Then you build the model in stages: assumptions, revenue side, cost side, and output. Each stage should be visible and auditable. The output isn't a single number. It's a range with stated assumptions attached.
Building the model structure
Start with a clean, blank spreadsheet. Don't start from a template. Templates are someone else's assumptions dressed up as convenience. Set up these columns: one for the base case, one for optimistic, one for pessimistic. Three scenarios is the minimum. More than five and nobody will read it. Finance will ask you to merge them anyway. Label every single input cell. Not "Churn" but "Monthly churn rate, assumed from Q2 cohort data." Not "Growth" but "Expected month-over-month user growth, based on current pipeline velocity." The day someone asks where a number came from, you want to be able to point at a label and read it back without reconstructing your thought process from memory. The revenue section is usually the hardest part for product managers because it's where guesses multiply. Your active users times your conversion rate times your price point. Each of those three numbers has its own uncertainty range. Multiply them together and you get a number that looks precise but could easily be off by 40% in either direction. Document that. Write it directly on the sheet as a comment in the cell. "Estimated range: 12% to 18%, point estimate 15%." That alone will make your model more credible than any perfectly formatted spreadsheet with no context.
Get the Full Details
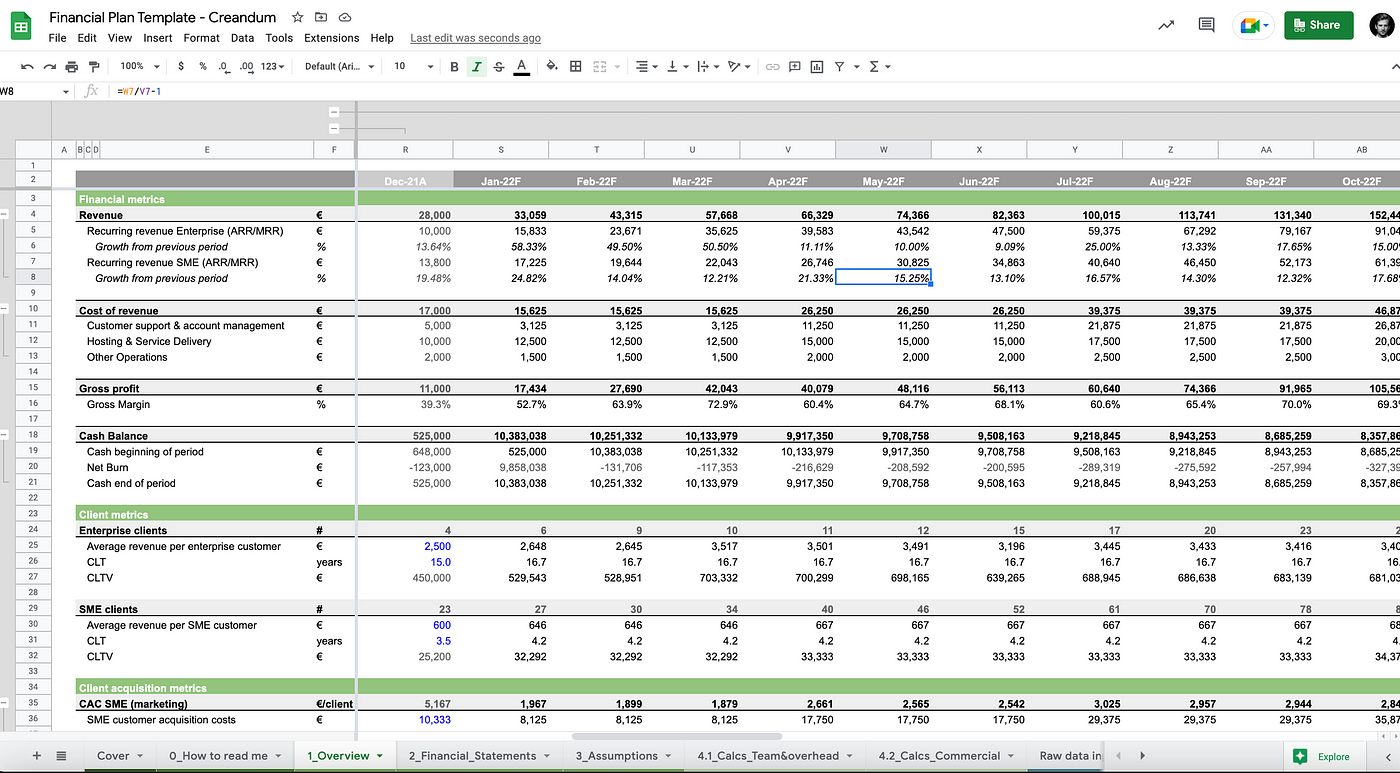
Costs are simpler but more dangerous because teams tend to underestimate them. Engineering hours, cloud infrastructure, customer support load, marketing spend tied to the launch. I once missed a customer support cost increase entirely. A new feature drove ticket volume up 34% in the first month, and nobody on the product team had modeled it. We just assumed support headcount would scale linearly. It didn't. We needed an additional contractor for two months. Factor in the indirect costs. Add a line item for "unforeseen operational impact" even if it feels redundant. It won't feel redundant when it's useful.
Common mistakes and how to avoid them
The biggest mistake I see is building a model that's too precise. Ten decimal places on your conversion rate creates a false sense of accuracy. Round your inputs. A conversion rate of 3.27% should be 3.3% or even 3%. The output precision should never exceed the input precision. If your inputs are rough estimates, your final numbers should look rough. A model that shows "$1,247,893 in projected revenue" is less trustworthy than one that says "$1.2M to $1.6M depending on adoption assumptions." Another mistake is confusing correlation with causation in your assumptions. Just because users who signed up during a promotional period converted at a higher rate doesn't mean your future organic users will perform the same. Treat each assumption as independent unless you have a specific reason to link them. Break your model every quarter. Intentionally change one assumption and see what breaks. You'll find cells that are hard-coded, formulas that reference the wrong ranges, scenario sheets that aren't actually tied to the base case. Fix it. This usually takes 15 to 20 minutes and prevents a much larger headache during an actual review.
When models fail you
Financial models are useful until they're not. They fail when the market shifts in ways that make your assumptions irrelevant. I built a model for a freemium product where the conversion assumption was based on industry benchmarks from two years prior. We launched, and the actual conversion was a quarter of the estimate. The model wasn't wrong given the data available. It was just stale. The workaround was setting a trigger—whenever a real metric diverged from the model by more than 20%, re-run the assumptions with fresh data instead of treating the original model as gospel. Models also fail when they're used as weapons. I've seen product managers use overly optimistic projections to push features through leadership. Finance noticed, the model lost credibility, and every future request had to fight through deeper skepticism. It's faster to be honest about uncertainty than to build confidence on a foundation of wishful thinking. If you need a starting point, there are basic template structures you can adapt—Revenue Build-Up model, Unit Economics model, and Scenario Analysis model are the standard three. Build yours from scratch using your own numbers. A template you didn't build yourself is just a spreadsheet full of assumptions you inherited without understanding them.