Understanding the Basics of Business Finance
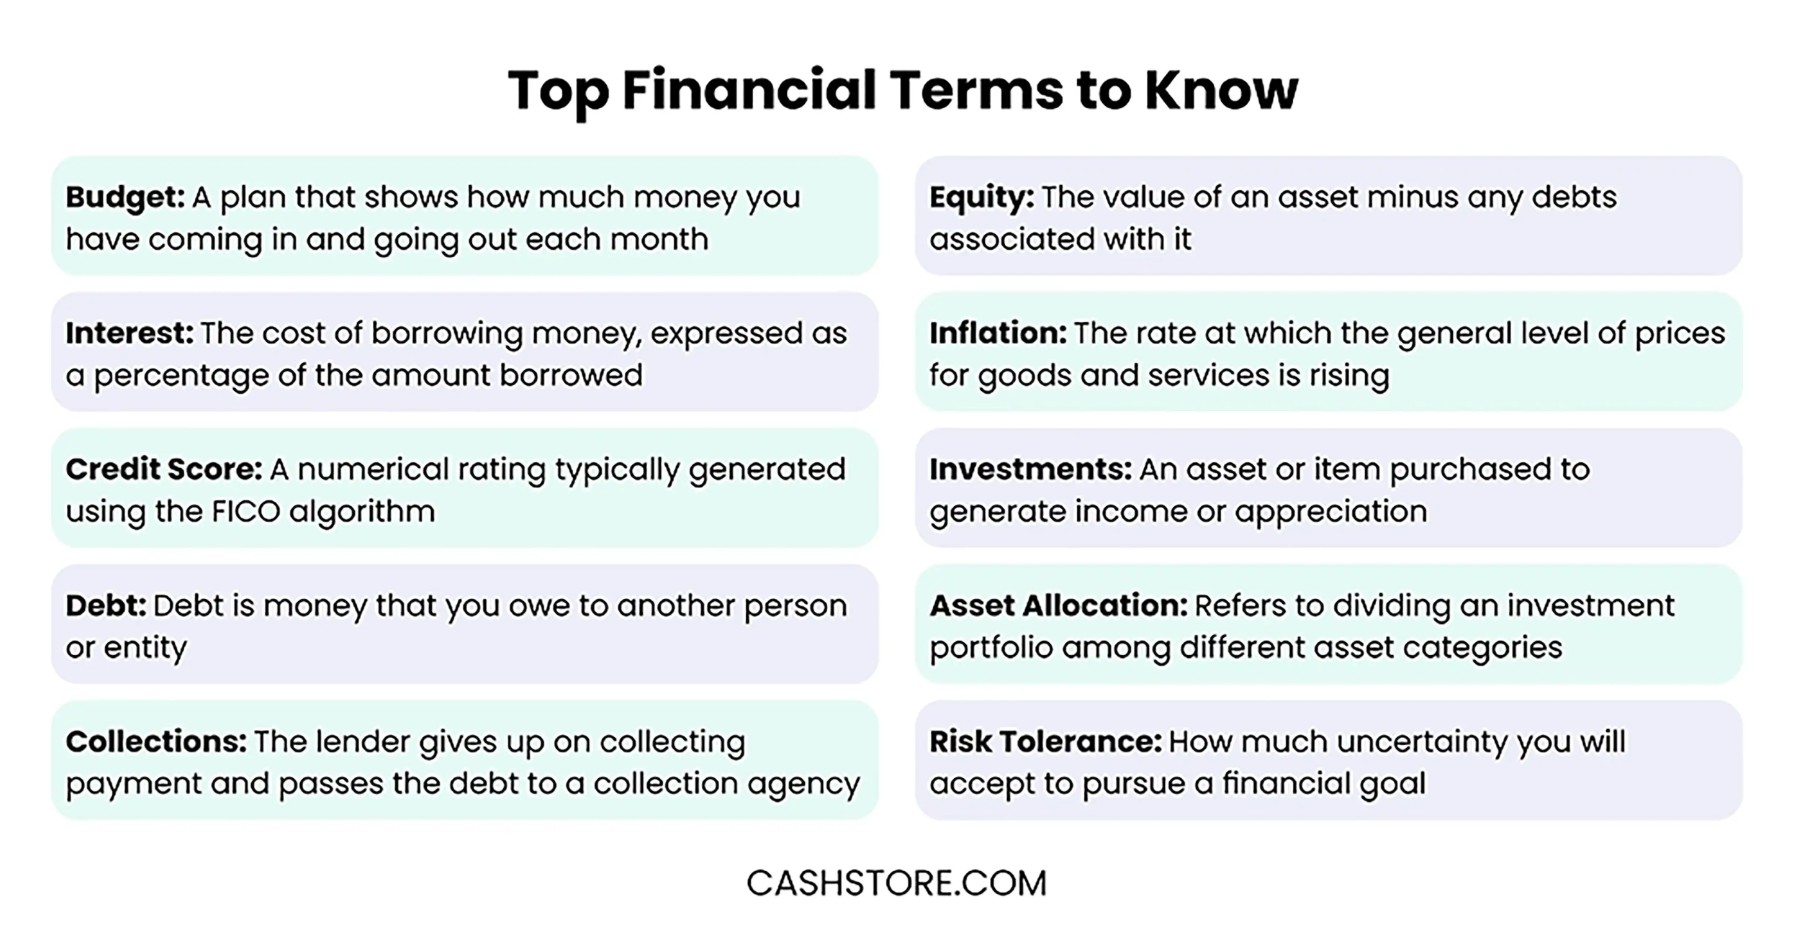
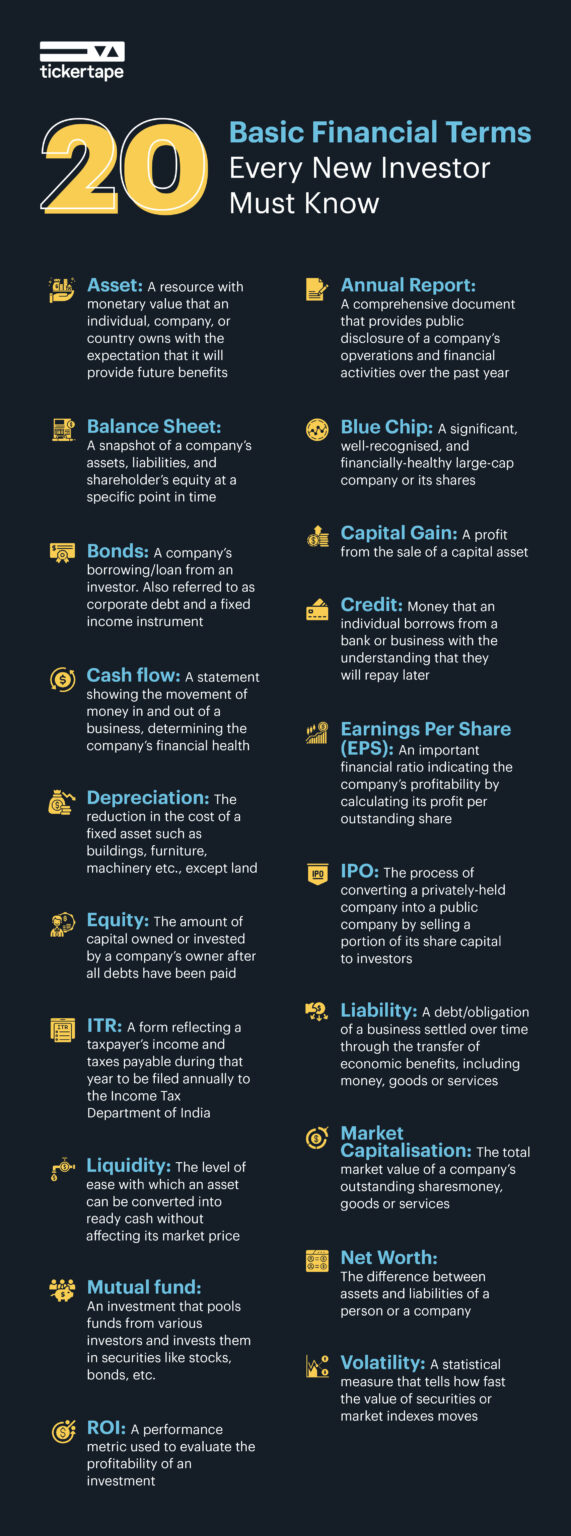
You don't need an MBA to read a balance sheet, but you do need to know what the numbers actually mean. Financial Terms To Know In Business aren't just words from a textbook—they're the tools you use every time someone asks whether your company is profitable or just looks good on paper. Let's start with EBITDA. Everyone throws this term around in meetings, and most people who use it don't fully understand it. EBITDA stands for Earnings Before Interest, Taxes, Depreciation, and Amortization. It's supposed to give you a clean view of operating profitability by stripping away financing decisions and accounting choices. Here's what nobody tells you: EBITDA can be manipulated easily because there's no standard definition. A company can exclude almost anything they want from their "adjusted EBITDA" calculation. I once reviewed a deal where the seller's adjusted EBITDA included a one-time legal settlement they claimed was "non-recurring" even though they'd had similar settlements every year for five years. The real operating earnings were 22 percent lower than what they reported. My workaround was simple—I went straight to free cash flow and calculated it from the actual bank statements. Cash doesn't lie the way adjusted earnings do. Now let's talk about working capital. This is current assets minus current liabilities, and it's the single most important number for understanding whether a business can pay its bills next month. A positive working capital sounds good until you realize it could be sitting in unsold inventory or unpaid invoices. I spent three weeks investigating a company that reported healthy working capital of about $400,000. When I dug into the receivables, I found that nearly $200,000 was over 90 days past due. The payables were all current and due within 30 days. Their working capital looked fine on a balance sheet snapshot. In reality, they were one supplier payment away from a cash crisis. The lesson here is that you need to look at the quality of working capital, not just the amount.
Accounting Methods That Actually Matter
Cash basis versus accrual basis accounting changes everything. Under cash basis, you record revenue when you receive money and expenses when you pay them. Under accrual, you record them when they're earned or incurred regardless of when the cash moves. Most small businesses start on cash basis because it's simpler. Then they grow, get audited, or try to get a loan, and they realize their numbers have been wrong this whole time. The problem with cash basis accounting is that it creates timing mismatches that hide real performance. If you close a big deal in December but don't get paid until February, cash basis shows zero revenue for that quarter. Accrual shows it when you earned it. Both are technically correct depending on your goal. But if you're making decisions based on cash basis numbers during a growth phase, you'll make bad hiring and purchasing decisions because the revenue picture is distorted. Depreciation is another area where people get confused. Straight-line depreciation spreads the cost of an asset evenly over its useful life. Double-declining balance accelerates it, taking more expense in early years. The choice affects your taxable income and your reported profit. A business buying equipment will show higher expenses and lower profits in early years under double-declining balance, which means lower taxes initially. That's a legitimate tax strategy, not accounting fraud. I worked with a restaurant owner who switched his depreciation method and suddenly had enough tax savings to fund a second location. The equipment wasn't any different, but the timing of his deductions changed everything about his cash flow.
Profitability Metrics That Separate Good Businesses From Bad Ones
Gross margin tells you what percentage of each dollar after subtracting the cost of goods sold. A SaaS company might have 80 percent gross margin while a grocery store runs 25 percent. Both can be profitable. Neither is inherently better. What matters is whether your gross margin covers your operating expenses and still leaves room for profit. Net profit margin is what's left after everything—COGS, operating expenses, interest, and taxes. This is the bottom line number that matters to investors. But here's the counter-intuitive part: a low net profit margin isn't always bad if your asset turnover is high enough. A dollar store making 3 percent net margin on $10 million in sales has the same annual profit as a consulting firm making 20 percent margin on $2 million in sales. The dollar store needs much more volume, but both generate $300,000 in profit. Understanding the DuPont breakdown—net margin times asset turnover times equity multiplier—gives you a complete picture of how a company actually creates returns. Return on equity and return on invested capital are two metrics that tell different stories about the same company. ROE measures profit relative to shareholder equity. ROIC measures profit relative to all capital provided by debt holders and equity holders combined. A company can have a high ROE but a terrible ROIC if it's loaded with debt. I've seen this repeatedly in private equity deals where the sponsor loads the acquired company with debt to boost ROE while the underlying business performance stays flat or declines. ROIC is the more honest measure because it accounts for the full capital structure. If ROIC is below your weighted average cost of capital, the company is destroying value even if it appears profitable on the surface.
Get the Full Details
Valuation Concepts You Can't Ignore
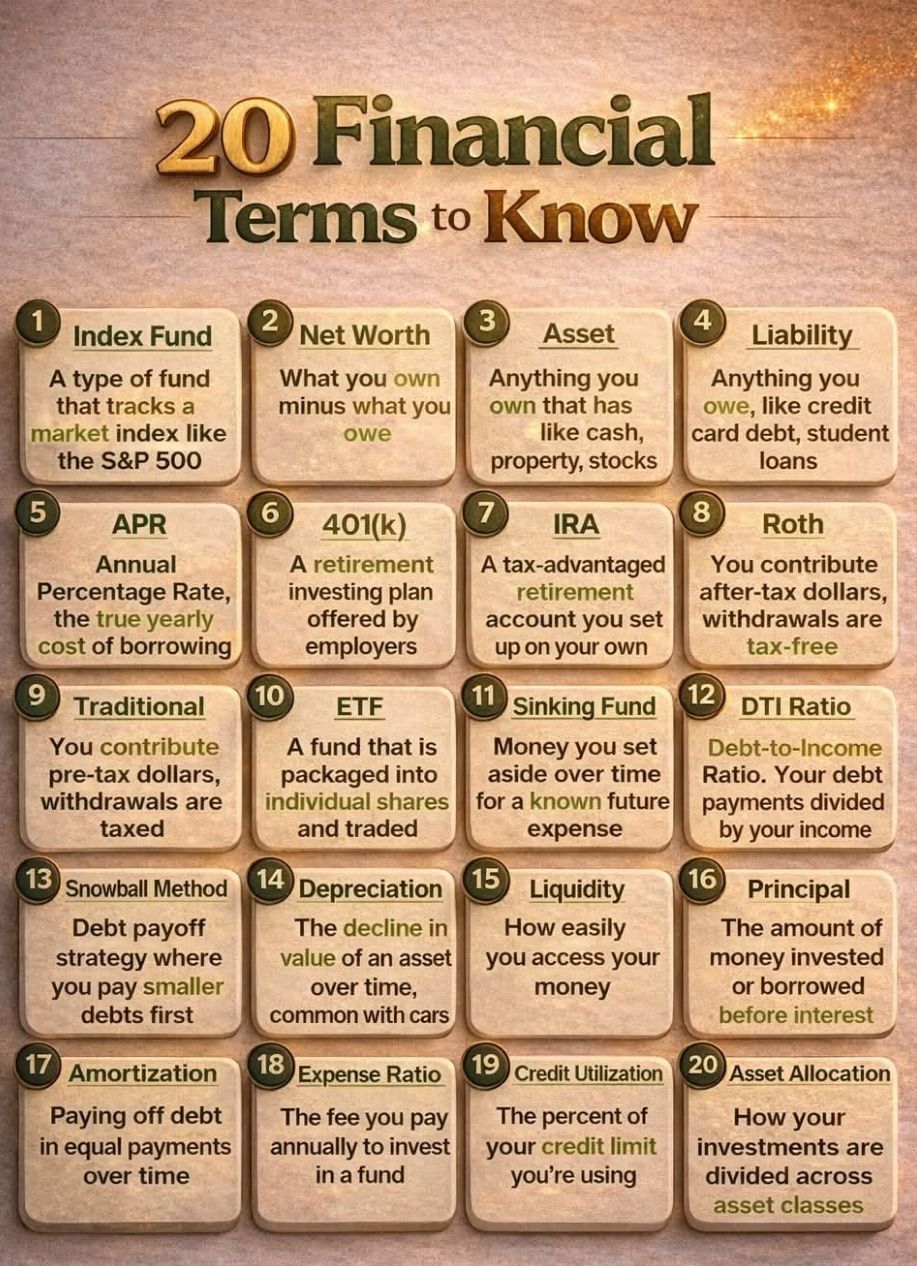
Enterprise value is the total price of a company including debt and excluding cash. Market cap is just equity value—the price of the shares. The difference matters enormously when you're looking at an acquisition. A company trading at a $50 million market cap might actually cost you $65 million to buy if it has $20 million in debt and only $5 million in cash. Enterprise value captures the true cost of the acquisition. I remember a situation where two companies had similar market caps but wildly different enterprise values because one carried significantly more debt. The one with more debt actually looked cheaper on a P/E basis but was far riskier once you accounted for the debt service obligations. Valuation multiples without context are misleading at best and dangerous at worst. Free cash flow to the firm is what's left after operating expenses, taxes, capital expenditures, and changes in working capital. This is the cash available to all investors, not just shareholders. Discounted cash flow valuation uses this number to estimate what a business is worth today based on expected future cash flows. The theory is solid. The practice is messy because small changes in your growth assumptions or discount rate create enormous differences in valuation. A 1 percent change in your terminal growth rate can swing your valuation by 15 percent or more. I learned this the hard way when I valued a client's business using a 3 percent terminal growth rate and got a result that was $2 million higher than what I got using 2 percent. Both assumptions were defensible. The range between them was just too wide to be useful for a negotiation.
Common Mistakes That Cost Real Money
One mistake I see constantly is confusing revenue with cash. A company can report $1 million in revenue and still go bankrupt if all that revenue is tied up in receivables. Another is ignoring the difference between operating profit and cash profit. Depreciation reduces operating profit but doesn't reduce cash. Companies that treat operating profit as if it were cash available for spending regularly find themselves unable to pay payroll. Seasonality is another factor that destroys naive financial analysis. A retail business might show strong Q4 numbers and look profitable on an annual basis. But if Q1 through Q3 are deeply negative, the business might be underwater for nine months of the year. I reviewed a holiday decoration company that appeared profitable annually but had run through three lines of credit by February each year. They survived only because they had relationships with lenders who understood their cycle. Without those relationships, they would have defaulted every single year. Finally, don't trust a single quarter of data. One good or bad month can distort your entire analysis. Look at at least four quarters, ideally two years, to smooth out anomalies. A single quarter might include a one-time sale, a delayed expense, or an accounting adjustment that shouldn't define your view of the business. Financial Terms To Know In Business aren't just definitions—they're lenses that either reveal or hide the truth depending on how carefully you use them.